How Do I Decide What Price to Offer on a House?
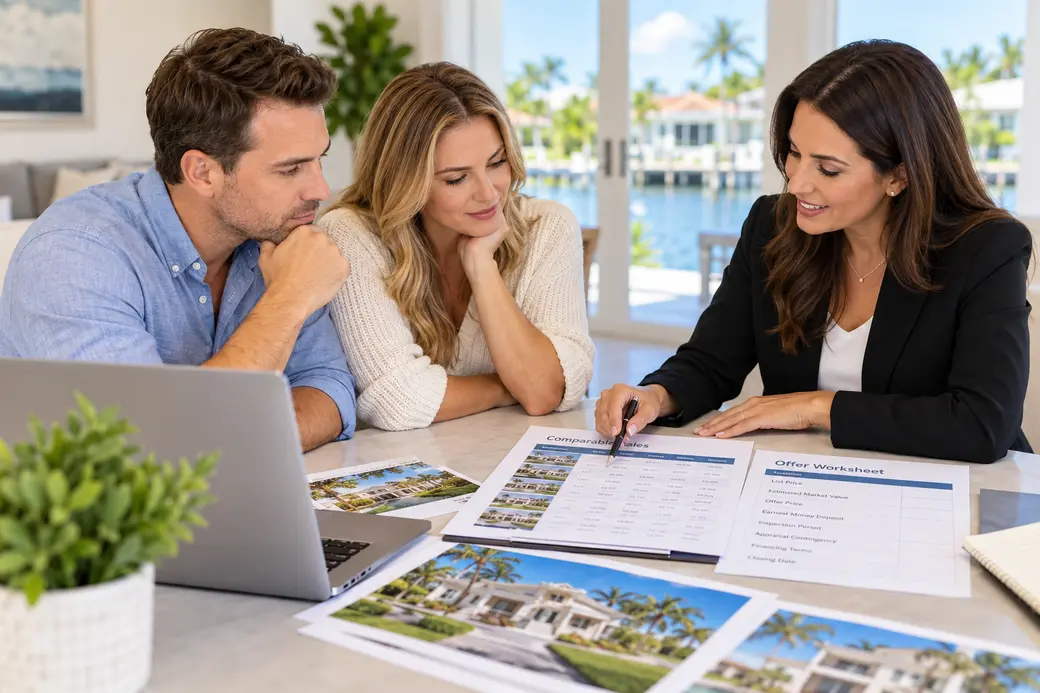
The best price to offer on a house is usually based on recent comparable sales, the home's condition, listing history, competing inventory, current buyer demand and what the property is worth to you within your budget. The asking price is a seller's requested price, not an automatic measure of market value and not a formula for your offer. A house listed at $600,000 could justify an offer near asking, below asking or, in a highly competitive situation, above asking. The useful question is not simply, "How much can I negotiate?" It is, "What price and terms make sense for this specific property?"
A licensed real estate professional can help organize the market evidence, while your mortgage lender can explain how a proposed price affects financing, cash requirements and appraisal considerations. Inspection, insurance, title, tax and legal questions should be reviewed with the appropriate qualified professionals when those issues could materially affect your decision.
Quick Answers About Deciding What Price to Offer on a House
Should I Automatically Offer Below the Asking Price?
No. There is no reliable rule that says every buyer should offer 5%, 10% or another fixed amount below asking. A reasonable offer depends on comparable sales, listing history, condition, competition and the property's current market position.
What Is the Most Important Information to Review Before Making an Offer?
Start with recent comparable closed sales, current competing listings, the home's original and current asking price, days on market and material condition differences. Those facts provide a stronger basis for an offer than simply choosing a discount from the list price.
Does a Longer Time on Market Mean I Should Offer Less?
A longer market time can create negotiating leverage, but it does not automatically establish how much a seller will accept. Review why the property has remained available, including its pricing history, condition, competing inventory and any previous contract activity that can be verified.
Should My Maximum Offer Equal What the Bank Will Lend Me?
Not necessarily. The amount a lender is willing to finance is different from the amount that fits comfortably within your complete household budget. Buyers should also consider property taxes, insurance, association costs, maintenance, closing costs and the cash they want to preserve after closing.
What Happens if the Appraisal Is Lower Than My Offer?
A low appraisal can affect the amount a lender is willing to finance. What happens next depends on the purchase contract, financing and any appraisal provisions. Buyers should understand their appraisal exposure before signing and review financing questions with their lender and contract questions with an appropriate Florida real estate attorney when legal interpretation is needed.
Can I Negotiate Something Other Than Price?
Yes. Depending on the transaction, buyers may negotiate seller concessions, closing timing, repairs, credits and other contract terms. Financing programs can limit the type or amount of allowable seller concessions, so proposed credits should be reviewed with the buyer's lender.
Should I Offer More if I Really Love the House?
Your personal value for the property can influence the maximum price you are willing to pay, but that decision should still be informed by market evidence, affordability and appraisal risk. Decide in advance what price you would be comfortable paying and what outcome you could accept if the seller declines.
Start With the House's Market Position, Not an Arbitrary Discount
One of the most common mistakes buyers make is deciding in advance that they will always offer a fixed percentage below asking. Hunt Brothers Realty's guide to how much you can negotiate on a Florida house explains why that approach can produce poor results.
Consider two houses listed at $600,000. One may have recently entered the market, be in good condition and be supported by several comparable sales around $600,000. The other may have started at $675,000, received multiple price reductions, require substantial repairs and compete against similar homes priced around $550,000.
Offering exactly 5% below asking on both properties would ignore the facts that actually influence value and seller leverage.
How Do Comparable Sales Help Determine an Offer Price?
Recent comparable closed sales provide evidence of what buyers actually paid for similar properties. Freddie Mac identifies recent sales prices of similar homes, property condition and buyer affordability among the important considerations when deciding what to offer.
Good comparables are not simply any homes that sold in the same ZIP code. The most useful properties generally share important characteristics with the home being evaluated.
- Location and neighborhood
- Property type
- Living area
- Bedrooms and bathrooms
- Lot characteristics
- Age and construction
- Condition and renovation level
- Garage and parking
- Pool or other major amenities
- Waterfront access or views when applicable
- Association structure and amenities when relevant
A real estate professional can help buyers organize these differences into a comparative market analysis. That analysis is useful for offer preparation, but it is not the same thing as a lender-ordered appraisal.
Why Should I Review Active Listings Too?
Closed sales show what buyers paid in completed transactions, while active listings show what alternatives today's buyer can currently choose. Both matter.
If five similar houses are available and several appear more competitively priced, a seller may have less leverage. If the home you want is the only well-maintained property available in the neighborhood at its price point, the negotiation can look very different.
Hunt Brothers Realty's guide to what a buyer's market means for Florida homebuyers explains why negotiating leverage often depends more on the seller's direct competition than on broad market labels.
How Does Listing History Affect What I Should Offer?
Listing history can reveal information that the current asking price alone does not show. Look at the original list price, price reductions, time on market and, when available, whether the property previously went under contract and returned to market.
What Do Multiple Price Reductions Tell Me?
Repeated price reductions can indicate that earlier buyers did not support the seller's original pricing. That does not prove the seller will accept another large reduction, but it provides useful context for determining whether the current asking price aligns more closely with market evidence.
Does Long Market Time Give Buyers More Leverage?
Sometimes. A property that has been available much longer than competing homes may give a seller more reason to negotiate. The useful question is why the home has remained unsold. Pricing, condition, insurance concerns, association costs, location and competition can all affect market time.
How Much Below Asking Price Should I Offer?
There is no universal percentage. Hunt Brothers Realty's current Florida negotiation guidance emphasizes that buyers should use property-specific evidence rather than automatically offering 5% or 10% below list price.
An offer materially below asking may be supported when comparable sales are lower, the property needs significant work, the seller has already made repeated reductions, the home has substantial carrying costs or there is considerable competing inventory.
A correctly priced property that has just entered the market and is generating strong activity may offer very little negotiating room. The percentage difference from list price matters less than whether the offer is defensible based on the market evidence and the buyer's priorities.
How Should the Condition of the House Affect My Offer?
Condition can materially affect what a buyer is willing to pay, but repair costs should be evaluated carefully rather than estimated casually. A home needing a roof, HVAC replacement, electrical work or substantial updating can have a very different value proposition from a renovated comparable sale.
Cosmetic preferences should also be distinguished from actual defects. A buyer may dislike flooring or kitchen cabinets, but personal remodeling preferences do not automatically reduce market value dollar for dollar.
Should I Subtract Estimated Repair Costs From the Asking Price?
Not automatically. First determine whether the asking price already reflects the property's condition and whether comparable sales had similar repair needs. Inspection findings and repair estimates should be reviewed with qualified inspectors, contractors, engineers or other appropriate professionals before buyers rely on them for a financial decision.
Why Does My Own Budget Matter as Much as Market Value?
A house can be fairly priced and still be too expensive for a particular buyer. Your offer ceiling should account for the complete cost of ownership, not just whether a lender will approve the loan.
The Consumer Financial Protection Bureau specifically distinguishes between what a lender will allow a borrower to finance and what the borrower can comfortably afford based on their broader budget. In addition to principal and interest, housing costs can include property taxes, homeowners insurance, flood insurance when applicable, mortgage insurance, association fees, utilities and maintenance.
Do Not Use Every Dollar for the Purchase Price
Buyers also need to consider their cash to close and what they want left after closing. The CFPB recommends accounting for moving costs, renovations, furnishings and an emergency cushion rather than directing all available savings toward the down payment.
Your mortgage lender can help estimate the loan payment and cash requirements associated with different offer prices. Financial planning and tax questions should be reviewed with appropriately qualified financial or tax professionals when individualized guidance is needed.
How Does the Appraisal Affect My Offer?
When a mortgage is involved, the lender will generally order an appraisal to obtain an independent opinion of the property's market value. Freddie Mac explains that the appraisal primarily helps the lender evaluate the home being used as collateral for the loan.
The appraisal is separate from the market analysis you use to prepare the offer. It also occurs after the parties have already agreed to a contract price.
What Is Appraisal Risk?
If the appraisal is lower than the contract price, the lender may calculate financing using the lower appraised value according to the loan program and underwriting requirements. That can create a financial gap between the agreed price and the lender-supported value.
What options the buyer has depends on the contract and applicable appraisal provisions. An appraisal contingency or other contractual language may provide rights under specified circumstances, but buyers should understand exactly what their contract says before signing.
Hunt Brothers Realty's guide to contingencies in a home offer explains why appraisal, financing, inspection and insurance provisions should be evaluated based on the individual transaction rather than treated as standard boilerplate.
Does the Highest Offer Always Win?
No. A seller can evaluate the entire offer rather than purchase price alone. Hunt Brothers Realty's guide to comparing home offers identifies financing, contingencies, deposits, seller concessions, closing timing and transaction certainty as additional factors sellers may consider.
For example, sellers may evaluate:
- Purchase price
- Financing type
- Preapproval or proof of funds
- Deposit structure
- Requested seller concessions
- Inspection terms
- Financing contingency
- Appraisal terms
- Closing date
- Possession timing
- Other transaction-specific conditions
A higher price accompanied by substantial credits or more uncertainty can produce a different seller outcome from a slightly lower price with different terms. Buyers should understand the tradeoffs instead of assuming that price is the only variable.
Should I Make My Offer Stronger by Removing Contingencies?
Removing a contingency can change the seller's perception of an offer, but it can also change the buyer's contractual rights and financial exposure. A contingency should not be removed simply because another buyer might submit a cleaner offer.
Common areas that may involve contingency or contract protections include:
- Financing
- Appraisal
- Property inspections
- Insurance availability
- Flood insurance when relevant
- Sale of another property
- Other property or transaction-specific conditions
Contract wording, deadlines and remedies matter. Buyers should understand the specific form being used and have individualized legal questions reviewed by a qualified Florida real estate attorney before changing protections that could carry significant consequences.
Should I Ask for Seller Concessions Instead of a Lower Price?
Sometimes the structure of the transaction can matter as much as the headline purchase price. Seller concessions may potentially help with allowable closing costs, prepaid expenses, discount points, rate buydowns or other permitted expenses depending on the financing program and transaction.
Hunt Brothers Realty's Florida seller concessions guide explains that lender limits can depend on loan type, down payment, occupancy, actual closing costs and underwriting requirements.
The Consumer Financial Protection Bureau also notes that seller credits can reduce a buyer's cash due at closing, although the economic tradeoff may include a different purchase price. A mortgage professional can model the actual loan and cash effects of different structures before the buyer decides what to request.
How Should Insurance, Flood Risk and HOA Costs Affect My Offer?
The purchase price is only one part of what a property costs to own. In Florida, insurance, flood exposure and association obligations can materially change the financial picture between two similarly priced homes.
Before stretching to a higher offer, buyers may need to investigate:
- Homeowners insurance availability and premium estimates
- Flood-zone information and flood insurance when applicable
- Roof age and wind-mitigation characteristics
- HOA or condominium assessments
- Known or proposed special assessments
- Association reserves where relevant
- CDD assessments in applicable communities
- Maintenance that the owner will be responsible for after closing
Insurance availability, coverage and premiums can vary substantially by property. Buyers should obtain property-specific quotes and review coverage with a qualified insurance professional before making a purchasing decision. Association documents and financial records should likewise be reviewed carefully when buying within an HOA or condominium.
How Do I Decide My Maximum Offer?
Your maximum offer is not necessarily the same as your opening offer. It is the highest price and overall transaction structure you would be comfortable accepting after considering the market evidence, affordability, property condition and the possibility that another buyer may pay more.
One practical way to think about the decision is to answer four separate questions:
- What does the market evidence support? Review comparable sales, current competition and listing history.
- What will this specific home cost to own? Consider financing, taxes, insurance, association expenses, repairs and maintenance.
- What risks come with the proposed price? Consider appraisal exposure, inspection issues and the amount of cash required.
- At what price would I be comfortable walking away? Decide before negotiations become emotional.
That final question can be especially useful in a multiple-offer situation. The goal is not to predict another buyer's number. It is to know your own boundaries before you are asked to make a quick decision.
What Does a Buyer's Agent Do When Helping With an Offer?
A buyer's agent can help organize the factual information surrounding a property so the buyer can make an informed decision. Hunt Brothers Realty's guide to what a Florida buyer's agent actually does identifies pricing analysis as part of that process.
Useful research can include:
- Comparable closed sales
- Current competing listings
- Listing and price-change history
- Market time
- Property disclosures
- Known association fees or assessments
- Material property differences
- Offer terms and seller priorities when known
A real estate agent is not a substitute for a lender, appraiser, inspector, insurance agent, attorney, engineer, tax professional or title professional. Those specialists should address issues within their respective areas when individualized expertise is necessary.
A Simple Example of How Offer Analysis Works
Assume a home is listed at $625,000. Recent similar homes sold around $600,000 to $620,000. The property has been listed for 75 days, was originally offered at $660,000 and needs an older roof replaced relatively soon. Several similar homes are also available.
Those facts could support a different negotiation than another $625,000 home that was listed yesterday, has a newer roof, was recently renovated and has comparable sales near or above asking. The list price is identical, but the evidence surrounding the two properties is not.
This example is illustrative only. Actual offer decisions depend on verified property information, current market conditions, financing and the buyer's priorities.
Frequently Asked Questions About Making a Home Offer
Is Offering 10% Below Asking Insulting?
The more useful question is whether the offer is supported by the property and market evidence. A 10% reduction could be reasonable on an overpriced property with weak demand, or unrealistic on a correctly priced new listing with multiple interested buyers.
Should I Start Low So I Have Room to Negotiate?
That approach carries tradeoffs. A lower opening offer can create room for a counteroffer, but it can also be rejected, especially when the property is competitively priced or another buyer submits stronger terms. Choose an opening position based on the specific negotiation rather than a universal tactic.
Can I Change My Offer After an Inspection?
What a buyer can request or do after an inspection depends on the contract language, inspection provisions, deadlines and the findings themselves. Buyers should understand the specific contract they sign and have legal questions reviewed by a qualified Florida real estate attorney.
Should I Offer the Maximum Amount I Am Preapproved For?
Not simply because the financing is available. Your preapproval reflects what a lender may be willing to finance subject to underwriting, while your personal budget should account for monthly expenses, closing costs, repairs, maintenance and financial reserves.
Can a Seller Reject My Offer Without Countering?
Yes. A seller may accept, reject or respond with different proposed terms, subject to the circumstances and applicable contract process. Buyers should not assume every offer will produce a counteroffer.
Should I Know My Walk-Away Price Before Making an Offer?
It can be useful to decide your financial and practical limit before negotiations intensify. That limit may reflect comparable values, affordability, appraisal exposure, repair needs and how difficult it would be to find another suitable home.
The Best Offer Price Comes From Evidence, Budget and Priorities
Deciding what to offer on a house is not about finding the perfect percentage below asking. It is about combining market evidence with the property's condition, competition, financing, appraisal exposure, ownership costs and your personal limits.
A useful offer starts with recent comparable sales and the home's position in the current market. From there, evaluate what the property will cost to own, which contract protections matter, how much cash you want to preserve and what price you would be comfortable paying if the seller accepts immediately.
Prepare Your Florida Home Offer With Hunt Brothers Realty
Hunt Brothers Realty helps Florida Gulf Coast buyers evaluate comparable sales, current competition, listing history and property characteristics before deciding how to structure an offer. Start with the Florida Buyer Resource Center, read the guide to making an offer on a Florida home, or contact Hunt Brothers Realty to discuss a property you are considering.
Informational notice: This article provides general real estate and educational information only and is not individualized legal, financial, tax, lending, appraisal, insurance, inspection or other professional advice. The appropriate offer price and contract structure depend on the specific property, market, financing and buyer circumstances. Buyers should review financing with a qualified mortgage professional, property condition with appropriately licensed inspectors or contractors, insurance with a qualified insurance professional, tax questions with a qualified tax professional, and contract or legal questions with a qualified Florida real estate attorney before making decisions that require individualized professional guidance.
Sources
- Hunt Brothers Realty, How Much Can You Negotiate on a Florida House?
- Hunt Brothers Realty, How to Make an Offer on a Florida Home
- Hunt Brothers Realty, What Contingencies Should I Include in a Home Offer?
- Hunt Brothers Realty, Seller Concessions in Florida
- Hunt Brothers Realty, What Does a Florida Buyer's Agent Actually Do?
- Freddie Mac, Making Your Offer on a Home
- Freddie Mac, What Homebuyers Can Expect With an Appraisal
- Consumer Financial Protection Bureau, Figure Out How Much You Want to Spend
- Consumer Financial Protection Bureau, Loan Estimate Explainer
Contact Hunt Brothers Realty
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3
Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1706
- Anna Maria Island 81
- Bird Key 3
- Bradenton 190
- Buying a Home 826
- Casey Key 2
- Clearwater 6
- Condos & HOA Living 726
- Ellenton 4
- Englewood 5
- First Time Homebuyers 912
- Foreclosures 3
- Homeownership 907
- Lakewood Ranch 16
- Lido Key 27
- Longboat Key 76
- Luxury/Waterfront Properties 844
- Market Updates & Trends 440
- Mortgages & Financing 37
- Move-Up Buyers 20
- Neighborhood Guides 585
- New Construction 28
- Palmetto 2
- Parrish 5
- Port Charlotte 9
- Punta Gorda 13
- Real Estate Investing 774
- Relocation to Florida 823
- Safety Harbor 2
- Sarasota 35
- Sarasota - Downtown 146
- Selling a Home 140
- Siesta Key 88
- St. Petersburg 4
- Tierra Verde 4
- Vacation & Second Homes 959
- Venice 22
- Wellen Park 7
Recent Posts