How Do I Know if a House Is Priced Fairly?
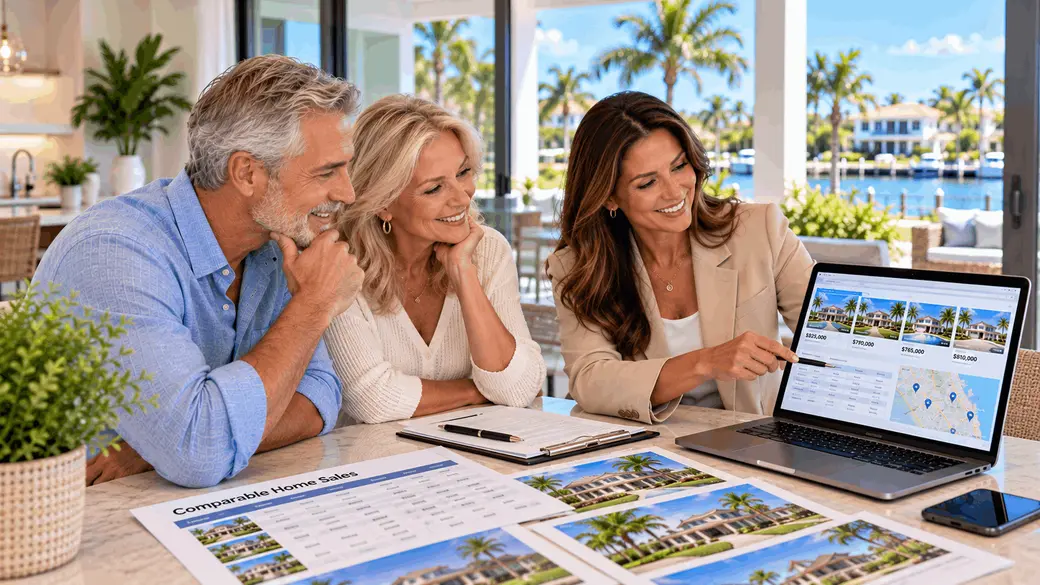
A house is more likely to be priced fairly when its asking price is reasonably supported by recent comparable sales, current competing homes, location, condition, size, features, and current market conditions. Do not assume a home is fairly priced simply because it was just listed, and do not assume it is overpriced simply because the seller is asking more than a nearby home sold for. The strongest analysis compares genuinely similar properties and accounts for meaningful differences. A real estate professional can help you review market evidence, while an appraisal may provide a separate professional opinion of value when financing requires one.
If you are preparing to buy in Florida, the Hunt Brothers Realty Florida Buyer Resource Center provides additional guidance on comparing properties, financing, contracts, and buyer representation.
Quick Answers About Whether a House Is Priced Fairly
Is the asking price the same as the home's market value?
No. The asking price is what the seller is requesting. Market value is an opinion of what the property is likely to bring under relevant market conditions. A seller can price a home above, below, or close to what current market evidence supports.
What is the best way to tell if a house is overpriced?
Start with recent comparable closed sales. Then compare the home with current competing listings, its listing and price history, condition, location, lot, renovations, major systems, and other features. A large unexplained gap between the asking price and relevant market evidence deserves closer analysis.
How recent should comparable home sales be?
More recent sales are generally more useful because they reflect more current market conditions, but relevance matters too. A somewhat older sale of a highly comparable property can sometimes provide useful context that a very recent but substantially different property cannot. The appropriate comparable set depends on the property and available market data.
Does price per square foot tell me if a house is priced fairly?
Not by itself. Price per square foot can provide context, but it does not fully account for condition, lot characteristics, renovations, pools, garages, views, waterfront access, floor plans, association costs, or other differences. It is most useful as one data point rather than a stand-alone valuation method.
Does an appraisal prove what a house is worth?
An appraisal is a professional opinion of value, not a guarantee of what every buyer would pay. Fannie Mae explains that appraisers consider factors such as recent comparable sales, location, condition, size, design, views, features, and market trends. Different valuation methods can sometimes produce different results.
Should I automatically offer less than the asking price?
No. There is no standard percentage every buyer should subtract from a home's asking price. Hunt Brothers Realty's guide to how much you can negotiate on a Florida house explains why offers should be based on property-specific evidence rather than an automatic discount.
What if the appraisal comes in below my contract price?
A low appraisal can affect financing and may require the buyer and seller to address the difference. Your options depend on the purchase contract, financing terms, appraisal provisions, and the parties' decisions. Discuss loan consequences with your lender and contract-specific rights with the appropriate real estate professional or a qualified Florida real estate attorney.
The Asking Price Is a Starting Point, Not Proof of Value
One of the most important ideas for a home buyer to understand is that a listing price is chosen before the property sells.
The seller and listing professional may have carefully analyzed comparable properties before establishing that price. The home may be positioned very close to current market evidence.
But the asking price can also reflect a seller's expectations, a pricing strategy, improvements the seller values highly, or an attempt to test what buyers will pay.
That is why the useful question is not, "Is this seller asking too much?" It is, "What does the available market evidence say about this particular property?"
Start With Recent Comparable Closed Sales
Comparable sales, commonly called comps, are among the most useful pieces of information when evaluating a home's price.
The goal is not to find every house that recently sold in the ZIP code. The goal is to identify properties that buyers would reasonably consider comparable to the home you are evaluating.
Depending on the property, relevant comparisons may include:
- Location and neighborhood
- Property type
- Living area
- Number of bedrooms and bathrooms
- Age and architectural characteristics
- Overall condition
- Renovation quality
- Lot size and characteristics
- Garage configuration
- Pool and outdoor improvements
- Waterfront, preserve, golf, or other views
- Water access when applicable
- Community and association characteristics
Two houses with similar square footage can have substantially different market positions when these characteristics differ.
Closed Sales and Active Listings Answer Different Questions
Closed sales show what buyers and sellers recently agreed to in completed transactions. Current listings show what today's sellers are asking and what alternatives today's buyers can choose instead.
Both are useful, but they should not be confused.
Suppose a house is listed for $600,000 and three similar active homes are also listed near $600,000. That tells you something about the seller competition, but it does not prove buyers are actually paying $600,000.
If recent comparable closed sales are clustered closer to $550,000, the difference deserves investigation. Perhaps the market has changed. Perhaps the $600,000 home is substantially better. Or perhaps several sellers are simply asking more than recent buyers have been willing to pay.
Look at the Property's Entire Listing History
The current asking price tells only part of the story.
Review information that may include:
- Original listing price
- Current asking price
- Previous price reductions
- Days on market
- Previous listing periods when available
- Whether the property previously went under contract and returned to market
These details do not automatically prove that a property is overpriced or that a seller will negotiate. They are signals that can help you understand how the market has responded to the property.
As Hunt Brothers Realty explains in its guide to what a buyer's market means for Florida homebuyers, longer market time, price reductions, competing inventory, condition, and gaps between asking prices and comparable sales can justify closer analysis, but none guarantees seller flexibility.
Property Condition Can Change the Pricing Analysis
A renovated home and a similar-sized home needing substantial work should not automatically receive the same valuation simply because they are located nearby.
Condition-related considerations can include:
- Roof age and condition
- HVAC equipment
- Electrical system
- Plumbing
- Windows and doors
- Kitchen and bathroom renovations
- Flooring and interior finishes
- Pool and pool equipment
- Exterior condition
- Visible deferred maintenance
- Permit history for relevant improvements
Do not estimate repair costs or structural implications solely from a showing. Inspection findings and property-condition questions should be evaluated by the appropriate licensed inspector, contractor, engineer, or other qualified professional before they materially influence a purchasing decision.
Why Price Per Square Foot Can Be Misleading
Price per square foot is appealing because it turns home valuation into a simple calculation. Unfortunately, real properties are not interchangeable units of living area.
Consider two 2,000-square-foot Florida homes in the same general area. One may have a newer roof, renovated kitchen, pool, three-car garage, premium lot, and desirable view. The other may have original finishes, deferred maintenance, a smaller garage, and a less desirable lot position.
Applying the same price per square foot to both properties ignores characteristics buyers may value differently.
Use price per square foot as supporting context, not as a substitute for a property-specific comparison.
Florida Homes Can Have Value Differences That Are Easy to Miss
Florida properties can look similar online while having materially different characteristics.
Depending on the property, investigate differences such as:
- Waterfront versus water view
- Gulf, bay, Intracoastal, canal, lake, or pond frontage
- Actual boating access
- Dock and seawall condition or rights
- Flood considerations
- Storm-protection features
- Association fees and services
- Condominium assessments
- CDD assessments
- Lot orientation and views
- Renovation quality and permitting
- Parking and storage arrangements
These factors can also be property-specific. Do not assume that a dock, view, parking space, storage area, rental permission, or other feature applies to every property within the same neighborhood or condominium.
A Fair Purchase Price Is Not the Same as a Low Purchase Price
Buyers understandably want a good deal, but "fairly priced" does not necessarily mean "priced below the market."
A newly listed home could be priced close to recent comparable sales and compete favorably with everything else available. In that situation, the asking price may be well supported even if the seller offers little room for negotiation.
Another property may have been listed for months, reduced several times, require significant work, and still be priced above similar recent sales. That home may require a very different strategy.
The objective is not automatically to pay less than asking. It is to understand whether the price you are considering is supported by the individual property's market evidence.
Do Online Home-Value Estimates Tell You What to Pay?
Online estimates can be useful as an initial reference, but they should not be treated as a definitive answer about a property's value.
The Consumer Financial Protection Bureau explains that valuations can come from different methods, including licensed appraisals, broker price opinions, and automated valuation models. Those valuations can differ because they may use different comparable properties, different information, different timing, and different methodologies.
An automated model may not fully understand a premium view, an inferior lot position, the quality of a renovation, deferred maintenance, a private dock, or other property-specific details that can matter to buyers.
What Is the Difference Between a Market Analysis and an Appraisal?
A real estate professional can help a buyer analyze comparable sales, active competition, listing history, property characteristics, and current market conditions when considering an offer. This type of market analysis can help you understand how the property is positioned before deciding what price and terms you want to propose.
An appraisal is different. Fannie Mae describes a home appraisal as an independent assessment of property value by a trained professional. For many financed purchases, the lender arranges an appraisal as part of evaluating the property securing the loan.
The appraisal should not be confused with the buyer's initial pricing analysis. It generally occurs later in the transaction, after the buyer and seller have already agreed to a contract price.
What Factors Can an Appraiser Consider?
According to Fannie Mae's appraisal guidance, factors affecting a home's value can include:
- Size and design
- Bedrooms and bathrooms
- Overall condition
- Location
- Views
- Additional features such as a swimming pool
- Recent sales of similar properties
- Relevant market trends
That list also illustrates why comparing houses based solely on bedroom count or square footage can produce misleading conclusions.
What Happens if the Appraisal Is Lower Than the Contract Price?
A lower appraisal can create a financing issue because the lender's underwriting is based in part on its valuation of the property.
What happens next depends on the specific contract, financing, appraisal provisions, and what the buyer and seller agree to do. Potential outcomes can vary, so buyers should not assume that a low appraisal automatically cancels a contract or automatically requires a seller to reduce the price.
The Consumer Financial Protection Bureau provides general information about low appraisals. Buyers should discuss loan-specific consequences with their lender and contract rights or obligations with a qualified Florida real estate attorney when legal interpretation is needed.
Do Insurance and Association Costs Affect Whether a Home Is a Good Value?
Purchase price is only one part of the financial picture.
Two homes with similar prices can have substantially different ongoing ownership costs because of:
- Property taxes
- Homeowners insurance
- Flood insurance when applicable
- HOA assessments
- Condominium assessments
- Special assessments
- CDD assessments
- Maintenance requirements
- Expected repairs and replacements
These costs do not mechanically determine market value, but they can materially affect whether a property works for your budget and how buyers compare competing homes.
Insurance availability, coverage, and premiums can vary substantially by property. Obtain property-specific quotes and review coverage with a qualified insurance professional. Association fees, assessments, reserves, restrictions, and owner obligations should be verified using current association documents and the appropriate association, management, legal, or financial professionals before making a purchasing decision.
How Can You Spot a Potentially Overpriced House?
No single clue proves that a home is overpriced. A combination of signals can justify a closer look.
Possible signals include:
- The asking price is materially above relevant recent comparable sales without an obvious property advantage.
- Similar active homes offer more for the same or lower price.
- The property has remained available substantially longer than similar homes.
- The seller has made repeated price reductions.
- The home's condition is materially inferior to similarly priced alternatives.
- The price appears heavily influenced by improvements that buyers may not value dollar for dollar.
- The seller appears to be relying on older market conditions rather than current transactions.
These are reasons to analyze the property more carefully, not proof of what the seller will ultimately accept.
How Can You Spot a House That May Be Priced Competitively?
A competitively priced home may show the opposite pattern:
- Recent comparable sales reasonably support the asking price.
- The home compares favorably with current alternatives.
- Condition is consistent with the price.
- Property features explain differences from lower-priced comparables.
- The property is attracting meaningful buyer interest.
- The listing is relatively new and positioned within the range buyers are currently considering.
Even then, competitive pricing does not guarantee a particular appraisal result or future resale value.
Should You Offer Below Asking if You Think the Home Is Overpriced?
You can propose a price supported by your analysis, but there is no standard discount that works for every property.
As explained in Hunt Brothers Realty's 2026 Florida home negotiation guide, automatically offering 5% or 10% below asking ignores the evidence surrounding the individual property.
A home listed at $500,000 might have strong comparable support near that amount. Another $500,000 listing might compete with highly similar properties selling closer to $475,000 and require significant repairs.
The same percentage-based strategy would make little sense for both homes.
Use This Fair-Price Checklist Before Making an Offer
| Question | What to Review |
|---|---|
| What have similar homes sold for? | Recent comparable closed sales. |
| What else can I buy? | Current competing listings in a similar price range. |
| How does this home differ? | Condition, renovations, lot, location, pool, garage, views, waterfront characteristics, and other material features. |
| Has the price changed? | Original price, current price, reductions, and listing history. |
| How has the market responded? | Market time and known buyer activity when reliable information is available. |
| What condition issues exist? | Visible maintenance concerns and professional inspection findings when available. |
| What are the ownership costs? | Taxes, insurance, association costs, assessments, maintenance, and other property-specific expenses. |
| What does my financing require? | Loan terms, appraisal requirements, cash needs, and lender-specific considerations. |
Questions to Ask Before Deciding What a House Is Worth to You
- Which recent sales are genuinely comparable to this property?
- How does the asking price compare with those sales?
- What similar homes are currently competing with this listing?
- What features justify a premium or discount compared with the comps?
- How long has the property been on the market?
- Has the seller reduced the price?
- Does the home need repairs or significant updating?
- Are renovations properly documented where applicable?
- What are the insurance considerations for this specific property?
- Are there HOA, condominium, CDD, or special-assessment costs?
- What would happen under my contract and financing if the appraisal were below the purchase price?
- Am I comfortable with the total ownership cost, not just the purchase price?
Fair Pricing Comes From Evidence, Not a Formula
There is no website, price-per-square-foot formula, neighborhood average, or automatic percentage discount that can tell you exactly what every house is worth.
A stronger approach is to build the answer property by property.
Start with relevant recent sales. Compare current alternatives. Study the listing history. Account for condition and meaningful property differences. Consider ownership costs. Then decide whether the asking price, or the price you are considering offering, is reasonably supported by that evidence.
That process will not guarantee a particular appraisal, seller response, or future resale price. It can, however, give you a much stronger basis for making an informed purchasing decision.
Evaluate a Florida Home With Hunt Brothers Realty
Hunt Brothers Realty can help buyers review recent comparable sales, competing listings, price history, market conditions, and property characteristics before deciding how to approach an offer. Explore the Florida Buyer Resource Center, read How Much Can You Negotiate on a Florida House in 2026?, review How to Make an Offer on a Florida Home in a Buyer-Friendly Market, or visit the Hunt Brothers Realty contact page to discuss your home search.
Informational notice: This article provides general real estate and educational information only and is not an appraisal or individualized legal, financial, lending, insurance, tax, inspection, engineering, or other professional advice. Property values and transaction circumstances vary. Buyers should discuss financing and appraisal requirements with a qualified lender, insurance availability and coverage with a qualified insurance professional, property condition with appropriate licensed inspectors, contractors, or engineers, and association matters with the applicable association and appropriate professionals. Questions involving purchase-contract rights, appraisal provisions, cancellation rights, title, or other legal matters should be reviewed with a qualified Florida real estate attorney when individualized legal guidance is needed.
Sources
- Hunt Brothers Realty, How Much Can You Negotiate on a Florida House in 2026?
- Hunt Brothers Realty, How to Make an Offer on a Florida Home in a Buyer-Friendly Market
- Hunt Brothers Realty, What Does a Buyer's Market Mean for Florida Homebuyers in 2026?
- Hunt Brothers Realty, Florida Buyer Resource Center
- Fannie Mae, Understanding Home Appraisals
- Consumer Financial Protection Bureau, What Are Appraisals and Why Do I Need to Look at Them?
- Consumer Financial Protection Bureau, Why Did I Receive Different Valuations During the Mortgage Loan Application Process?
- Consumer Financial Protection Bureau, My Appraisal Is Less Than the Sale Price
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2152
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1211
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1127
- Ellenton 6
- Englewood 11
- First Time Homebuyers 1320
- Foreclosures 5
- Home Selling 6
- Homeownership 1344
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1283
- Market Updates & Trends 804
- Mortgages & Financing 51
- Move-Up Buyers 23
- Neighborhood Guides 919
- New Construction 36
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1200
- Relocation to Florida 1239
- Safety Harbor 3
- Sarasota 86
- Sarasota - Downtown 163
- Selling a Home 146
- Siesta Key 92
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1393
- Venice 209
- Wellen Park 20
Recent Posts