What Credit Score Do I Need to Buy a House in Florida?
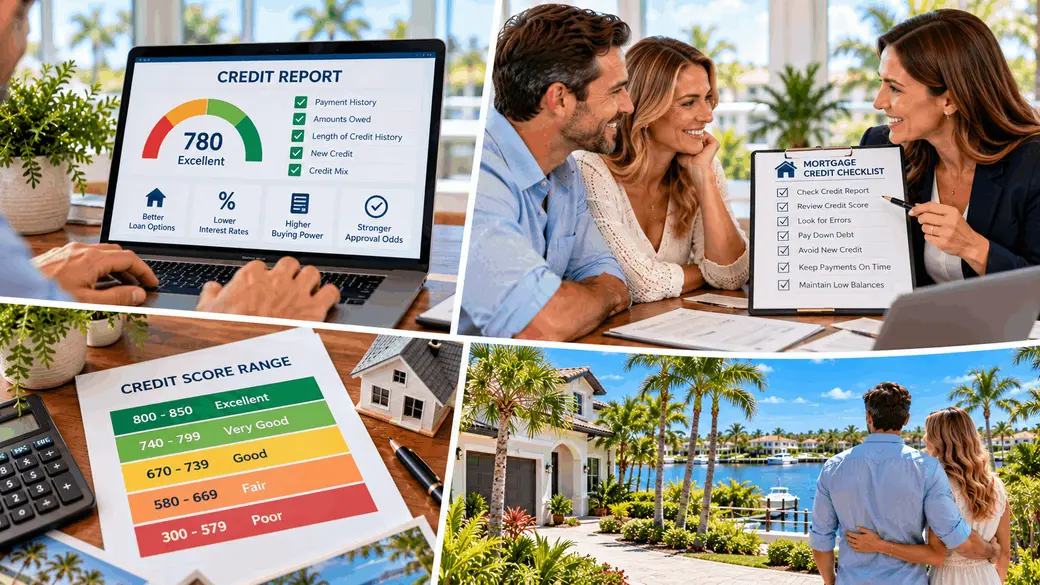
There is no single credit score required to buy a house in Florida. The answer depends on the mortgage program, underwriting method, lender and your complete financial profile. FHA rules can permit qualified borrowers with a 580 or higher decision credit score to use the program's 3.5% minimum down payment, while scores from 500 through 579 require at least 10% down under FHA rules. VA and USDA do not establish one universal program minimum credit score, although individual lenders can impose their own requirements. Conventional financing is also more nuanced in 2026, including Fannie Mae loans evaluated through Desktop Underwriter without a blanket minimum credit score requirement.
Quick Answers About Credit Scores for Buying a House in Florida
Is 620 the Minimum Credit Score to Buy a House?
No. A 620 score is frequently associated with conventional mortgage underwriting, but it is not a universal home-buying minimum. Current Fannie Mae rules do not impose a minimum credit score on loan casefiles evaluated through Desktop Underwriter, while manually underwritten loans have separate minimums. Other mortgage programs use different credit standards.
Can I Buy a House With a 580 Credit Score?
Potentially. FHA rules permit the program's 3.5% minimum down payment for borrowers meeting the applicable 580 credit-score threshold, but meeting that threshold does not guarantee mortgage approval. A lender may apply additional underwriting standards and must evaluate the rest of the application.
Can I Get an FHA Loan With a Credit Score Below 580?
FHA's established framework allows borrowers with qualifying scores from 500 through 579 to be eligible for FHA insurance with at least a 10% down payment. Individual lenders can set more restrictive standards, so finding a lender willing to originate a loan at that score is a separate question from FHA program eligibility.
What Credit Score Does a VA Loan Require?
The U.S. Department of Veterans Affairs states that VA does not require a minimum credit score. Private lenders making VA-backed loans can establish their own credit requirements, and borrowers must still satisfy applicable credit, income and underwriting standards.
What Credit Score Does USDA Require?
USDA currently states that its Single Family Housing Guaranteed Loan Program has no program-level credit score requirement. Applicants must demonstrate the willingness and ability to manage debt, and participating lenders can have additional underwriting standards. USDA financing also has household-income, property-location and other eligibility requirements.
Does a Higher Credit Score Help When Buying a Home?
It can. Credit is one factor lenders use in evaluating mortgage risk and pricing. A stronger credit profile may improve available financing terms, but the effect depends on the loan, lender, market conditions and other borrower characteristics.
Does Meeting the Minimum Credit Score Guarantee Mortgage Approval?
No. Mortgage underwriting also considers factors such as income, employment, debts, assets, down payment, credit history and the specific property. A score that satisfies one requirement does not by itself establish that the loan will be approved.
What Credit Score Do Different Mortgage Programs Require in 2026?
Mortgage credit requirements are easier to understand when separated by loan program. The table below summarizes important program-level distinctions, but it should not be treated as a promise that a lender will approve a borrower at the stated score.
| Mortgage Type | Program-Level Credit Guidance | Important Qualification |
|---|---|---|
| Fannie Mae Conventional | No minimum score for DU loan casefiles | Manual underwriting has separate minimums, and lenders can have additional requirements |
| FHA | 580 or higher for 3.5% minimum down payment, 500 through 579 requires at least 10% down under FHA rules | Lenders may impose more restrictive standards |
| VA | VA does not establish a minimum credit score | Private VA lenders may establish minimums, and VA eligibility is required |
| USDA Guaranteed | USDA states the program has no credit score requirement | Lender underwriting plus income, location and other program eligibility requirements apply |
Jumbo mortgages and other portfolio loans can follow lender-specific standards rather than one universal credit-score rule. Buyers considering these products should obtain current requirements directly from qualified lenders.
What Changed for Conventional Mortgage Credit Scores?
One reason older home-buying advice can be misleading in 2026 is that Fannie Mae changed its credit-score eligibility rules for loans evaluated through Desktop Underwriter, commonly called DU.
Fannie Mae's current Selling Guide states that a minimum credit score is not required for DU loan casefiles. Instead, DU evaluates creditworthiness using multiple risk factors within its automated underwriting process.
That does not mean credit scores no longer matter, nor does it mean every applicant with a low score qualifies. Credit can still affect the underwriting result, loan pricing and lender requirements.
Does Fannie Mae Still Have Minimum Scores for Manual Underwriting?
Yes. Fannie Mae's April 22, 2026 Selling Guide lists a minimum credit score of 620 for manually underwritten fixed-rate loans and 640 for manually underwritten adjustable-rate mortgages, subject to the complete eligibility requirements that apply to the transaction.
This distinction is why buyers should avoid treating a single conventional-loan number found online as universally applicable.
What Credit Score Do You Need for an FHA Loan?
FHA financing has one of the clearest relationships between credit score and minimum required investment.
- 580 or higher: FHA rules can permit the 3.5% minimum down payment for an otherwise eligible borrower.
- 500 through 579: FHA rules require at least a 10% down payment.
- Below 500: The borrower does not satisfy FHA's established minimum decision credit-score framework for FHA insurance.
Those are FHA program rules, not a statement that every FHA lender will approve applicants at those scores. Lenders can establish additional standards based on their underwriting policies.
FHA is also preparing for expanded use of alternative credit-score models for applicable case numbers assigned on or after January 1, 2027. Buyers applying around that transition should ask their mortgage professional which current FHA scoring methodology applies to their application.
What Credit Score Do You Need for a VA Home Loan?
VA does not establish a universal minimum credit score for its home loan guaranty. This is an important distinction between VA program requirements and lender requirements.
The U.S. Department of Veterans Affairs explains that borrowers still need to satisfy applicable credit and income requirements. VA also notes that private lenders may impose additional standards, including a lender-specific credit-score requirement.
Therefore, a buyer should not interpret "VA has no minimum score" to mean that credit is irrelevant or that every VA lender will approve the same credit profile.
What Credit Score Do You Need for a USDA Loan?
The USDA Single Family Housing Guaranteed Loan Program currently states that the program has no credit score requirement. Applicants are nevertheless expected to demonstrate the willingness and ability to manage debt.
USDA loans also have eligibility requirements beyond credit. These can include household-income limitations, occupancy requirements and property-location eligibility. Individual participating lenders can also apply their own underwriting requirements.
What Is a Lender Overlay?
A lender overlay is an additional lending requirement that is more restrictive than the underlying mortgage program's baseline rule.
For example, a government program might not establish a particular minimum credit score, while an individual lender chooses to require one for loans it originates. Another lender may use different standards.
This helps explain why one lender might decline a borrower while another lender identifies a viable financing option. It does not mean the second lender will necessarily offer equivalent pricing, fees or terms.
Why Does Your Credit Score Matter Even When There Is No Program Minimum?
The absence of a universal minimum does not make credit unimportant. Lenders use credit information as part of evaluating the likelihood that a borrower will repay the mortgage as agreed.
Depending on the mortgage, lender and borrower, credit can affect:
- Whether the application satisfies underwriting requirements
- Interest-rate and loan pricing
- Available mortgage programs
- Mortgage insurance pricing when applicable
- Required down payment in some programs
- Whether additional documentation or underwriting review is necessary
A qualified mortgage professional can explain how your actual credit profile affects the loans currently available to you.
Is Your Credit Score the Only Credit Factor a Mortgage Lender Reviews?
No. A three-digit score summarizes certain credit information, but underwriting can involve the broader credit history as well.
Depending on the circumstances, lenders may evaluate matters such as payment history, outstanding debts, recent credit activity, derogatory events and other information appearing in the credit file. The treatment of particular events depends on the mortgage program and underwriting requirements.
Do not assume that two borrowers with the same score will receive identical mortgage results. Their complete credit histories and financial profiles may be very different.
What Else Does a Mortgage Lender Look at Besides Credit?
Mortgage approval is based on substantially more than credit score. Depending on the program and borrower, underwriting can include:
- Income and its qualifying treatment
- Employment or other income documentation
- Existing monthly debts
- Assets and available funds
- Down payment
- Cash needed for closing
- Required reserves when applicable
- Loan amount and loan-to-value ratio
- Property type and eligibility
- Appraisal and other property-related requirements
For this reason, a borrower with excellent credit is not automatically approved, while a borrower with a lower score should not automatically assume homeownership is impossible.
Can a Higher Credit Score Lower Your Mortgage Payment?
Potentially. If a stronger credit profile results in more favorable mortgage pricing, the resulting interest rate or other loan costs can change the monthly payment and long-term borrowing cost.
The effect is not a fixed number of dollars per credit-score point. Mortgage pricing depends on the lender, loan program, market rates, down payment, property and other risk factors.
Ask lenders to provide actual loan scenarios rather than assuming that reaching a particular score will automatically produce a specific interest rate.
Should You Improve Your Credit Before Buying a House?
Sometimes improving credit before purchasing can expand financing options or improve loan pricing, but buyers should first determine what their current profile actually qualifies for.
A borrower who assumes a 700 score is required might unnecessarily postpone a purchase even though a qualified lender can identify an appropriate financing option today. Conversely, another buyer may benefit materially from addressing specific credit issues before applying.
Before paying off accounts, closing credit cards, opening new accounts or making other significant credit changes specifically to qualify for a mortgage, discuss the potential effect with a qualified mortgage or credit professional. Actions that seem beneficial can affect credit scoring, available assets or underwriting differently than expected.
Should You Check Your Credit Before Applying for a Mortgage?
Yes. Reviewing your credit before serious mortgage shopping gives you an opportunity to understand what is being reported and address legitimate errors through the appropriate credit-reporting process.
Keep in mind that a consumer credit score you see through a bank, credit card company or consumer service may not be identical to the score used by a mortgage lender. Mortgage underwriting uses applicable credit-reporting and scoring requirements for the particular loan.
Can You Buy a Florida Home With Bad Credit?
A lower credit score does not automatically mean you cannot buy a home, but it can narrow the financing available and may increase borrowing costs or required cash.
The most useful first step is to have qualified mortgage professionals review your actual circumstances. They can explain whether financing is currently available and, if not, which specific issues are preventing qualification.
That is more useful than relying on a generic online statement that everyone below a particular score must wait.
Should You Get Mortgage Preapproved Before Looking at Florida Homes?
If you plan to finance your purchase and are becoming a serious buyer, mortgage preapproval can help connect your credit and financial profile to an actual home-search range.
Hunt Brothers Realty's guide to getting preapproved before looking at houses explains that preapproval can help establish a preliminary financing range, identify mortgage issues before you find a property and prepare documentation for an offer.
Preapproval is not final mortgage approval. Final financing can still depend on continued borrower qualification, underwriting, appraisal, the property, insurance and other lender conditions.
Should You Compare More Than One Mortgage Lender?
Comparing lenders can be especially useful when credit is a concern because lender standards, programs, rates and fees can differ.
One lender's minimum credit requirement should not automatically be interpreted as the minimum imposed by every lender or by the underlying mortgage program.
Compare the complete financing proposal, including interest rate, annual percentage rate, points, lender fees, mortgage insurance when applicable, down payment, estimated cash to close and monthly payment. A lower credit-score threshold by itself does not establish that a particular loan is the best financing choice.
How Does Credit Affect How Much House You Can Afford in Florida?
Credit can affect the financing available to you, but it is only one component of affordability.
A Florida home budget should also account for mortgage principal and interest, property taxes, homeowners insurance, flood insurance when applicable, mortgage insurance, HOA or condominium assessments and other ownership expenses.
Read How Much House Can You Afford in Florida in 2026? to build a budget around the complete monthly housing expense rather than the mortgage amount alone.
What Should You Ask a Mortgage Lender About Your Credit?
Instead of asking only whether your score is "good enough," ask questions that reveal how credit affects your actual financing choices:
- Which mortgage programs could I currently qualify for?
- Does your company have a minimum credit score above the program requirement?
- How is my current credit affecting the interest rate or loan pricing?
- Would a different down payment change my options?
- Does mortgage insurance apply, and how is it priced?
- Are there specific credit issues affecting my underwriting result?
- Would waiting to address a particular issue materially change my options?
- What financial changes should I avoid while applying for and closing the mortgage?
What Should You Avoid Doing With Credit Before Closing?
Once you are preparing for a mortgage, significant changes to your credit or debts can affect underwriting. Avoid assuming that approval is permanent simply because you received a preapproval letter.
Before opening a new credit account, financing a vehicle, substantially increasing credit-card balances, closing accounts or making other significant credit changes during the mortgage process, ask your lender how the proposed action could affect qualification.
Likewise, changes involving employment, income, debts or available assets should be discussed promptly with your mortgage professional rather than assuming they will not matter.
The Bottom Line: What Credit Score Do You Need to Buy a Florida House?
There is no universal Florida home-buying credit score. FHA has defined score and down-payment thresholds, VA does not establish a program minimum, USDA states that its guaranteed program has no credit score requirement, and Fannie Mae no longer applies a blanket minimum score to loan casefiles evaluated through Desktop Underwriter.
The lender can still impose additional requirements, and the complete mortgage application matters. Your income, debts, assets, down payment, credit history, property and underwriting result can all affect approval.
If you are wondering whether your current credit is sufficient, the most useful next step is not to guess based on a generic score chart. Have qualified mortgage professionals evaluate your current profile and explain the financing options, costs and requirements that actually apply to you.
Prepare for Your Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty helps Florida Gulf Coast buyers organize the real estate side of the home-buying process after they understand their financing range. Buyers can explore Florida Gulf Coast communities, learn why mortgage preapproval can be useful before serious house hunting, and review how much house you can afford in Florida.
When you are ready to define your property search, contact Hunt Brothers Realty.
This article provides general real estate and educational information only. It is not individualized financial, lending, credit, tax, insurance or legal advice. Mortgage eligibility, credit-score treatment, interest rates, loan pricing, down-payment requirements and underwriting depend on the individual borrower, lender, mortgage program, property and current guidelines. Buyers should verify current financing requirements and individualized credit questions with qualified mortgage lenders or loan professionals and consult other appropriate financial, tax, legal, insurance and real estate professionals when a decision requires individualized guidance.
Sources
- Fannie Mae, Selling Guide, April 22, 2026
- Fannie Mae, Selling Guide Update Removing Minimum Credit Score Requirements From Desktop Underwriter
- U.S. Department of Housing and Urban Development, FHA TOTAL Scorecard and 2026 Credit Score Updates
- U.S. Department of Veterans Affairs, VA-Backed Home Loans
- U.S. Department of Veterans Affairs, VA Home Loan Credit and Qualification Guidance
- USDA Rural Development, Single Family Housing Guaranteed Loan Program
- Hunt Brothers Realty, Should I Get Preapproved Before Looking at Houses?
- Hunt Brothers Realty, How Much House Can You Afford in Florida in 2026?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2070
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1131
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1049
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1240
- Foreclosures 3
- Home Selling 3
- Homeownership 1263
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1204
- Market Updates & Trends 730
- Mortgages & Financing 42
- Move-Up Buyers 21
- Neighborhood Guides 842
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1121
- Relocation to Florida 1163
- Safety Harbor 2
- Sarasota 77
- Sarasota - Downtown 162
- Selling a Home 144
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1313
- Venice 169
- Wellen Park 16
Recent Posts