Cash Buyer vs. Financed Buyer in Florida: Who Has the Advantage in 2026?
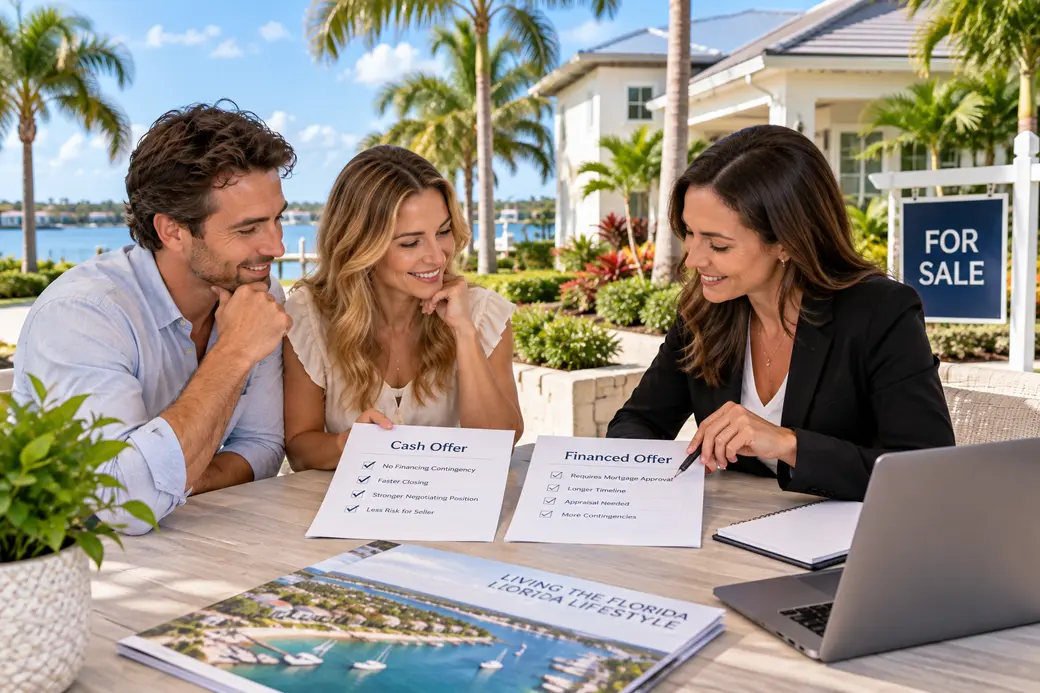
A cash buyer often has a structural advantage when competing for a Florida home because the purchase does not depend on mortgage approval, lender underwriting or a lender-required appraisal. But cash does not automatically make an offer better. In Florida's 2026 market, a well-qualified financed buyer can compete effectively by obtaining strong preapproval, limiting unnecessary uncertainty, offering terms that fit the seller's priorities and demonstrating the ability to close. The strongest offer is ultimately the combination of price, contractual terms, financial strength, timing and risk that a particular seller finds most attractive.
Quick Answers About Cash Buyers vs. Financed Buyers in Florida
Does a Cash Buyer Always Beat a Financed Buyer?
No. Cash can reduce financing-related uncertainty, but sellers can consider price, deposit, contingencies, closing date and other contractual terms. A stronger financed offer may be more attractive than a lower cash offer.
Why Do Some Florida Sellers Prefer Cash Offers?
A true cash purchase can eliminate the buyer's need for mortgage approval and lender underwriting. Depending on the contract, it can also remove financing-related appraisal uncertainty and may allow greater flexibility in scheduling the closing.
Can a Financed Buyer Still Win Against Cash?
Yes. A financed buyer may offer a higher price, stronger deposit, attractive closing date or other terms the seller prefers. Strong mortgage preapproval can also reduce uncertainty, although preapproval is not a guarantee that the loan will close.
Do Cash Buyers Need an Appraisal?
A cash buyer does not have a mortgage lender requiring an appraisal. The buyer can still choose to obtain an appraisal or negotiate an appraisal contingency if the seller agrees. Whether that protection exists depends on the executed contract.
Do Cash Buyers Still Need a Home Inspection?
Paying cash does not eliminate property-condition risk. Cash buyers can still conduct inspections and other due diligence according to their contract. Hunt Brothers Realty explains what buyers may encounter when a Florida home inspection finds problems.
How Common Are Cash Purchases in Florida?
Cash remains a major part of Florida real estate. Florida Realtors reported that 30.3% of statewide single-family closed sales during the first three months of 2026 were cash purchases. In March alone, 28.5% of closed single-family sales were cash transactions.
Should a Financed Buyer Get Preapproved Before Making an Offer?
Generally, buyers planning to finance should speak with a qualified lender before becoming serious offer writers. As Hunt Brothers Realty explains in its guide to getting preapproved before looking at houses, preapproval can establish a realistic financing range and identify potential mortgage issues earlier in the process.
Why Does Cash Have an Advantage in a Florida Real Estate Offer?
The primary advantage of cash is not simply that the buyer has money available. It is the removal of an entire layer of transaction dependency.
A financed transaction can depend on several parties and processes beyond the buyer and seller. The lender must evaluate the borrower, loan and property. Documentation may need to be updated. The property may require an appraisal or other valuation. Certain loan programs can impose additional property requirements. Final underwriting conditions must be satisfied before funding.
A genuine cash purchase does not require mortgage approval to fund the acquisition. That can reduce the number of events capable of delaying or disrupting the transaction.
What Is a Cash Offer in Florida?
In practical terms, a cash buyer intends to purchase the property without making the transaction contingent on obtaining mortgage financing.
Florida Realtors' analysis of the financing contingency explains that the cash option in the Florida Realtors/Florida Bar contract states that the transaction has no financing contingency. When that option applies, the buyer is committed to bringing the money required to close and does not have financing-contingency protection if funds are unavailable.
That distinction is important. A buyer should not select a cash structure simply to make an offer appear stronger if the buyer actually needs financing to complete the purchase and does not understand the contractual consequences.
Questions about contractual rights, financing contingencies, default or deposit exposure should be reviewed with a licensed real estate professional and, when legal interpretation is needed, a qualified Florida real estate attorney.
How Does a Financed Offer Work?
A financed buyer uses mortgage proceeds for some portion of the purchase price. Depending on the contract selected and negotiated terms, the transaction may include a financing contingency with specific requirements and deadlines.
Florida Realtors explains that its financing contingency can provide protection when a buyer applies for financing but cannot obtain the required loan approval and lender-satisfactory appraisal within the contractual framework. The exact rights and obligations depend on the executed contract, dates, notices and circumstances.
This protection can be valuable to a buyer, but from a seller's perspective it introduces an additional condition that must be satisfied before closing.
Cash vs. Financing: What Does a Florida Seller See?
| Offer Factor | Cash Buyer | Financed Buyer |
|---|---|---|
| Mortgage approval | Not required to fund a true cash purchase | Required |
| Lender underwriting | Not part of the purchase | Generally required |
| Lender-required appraisal | None | May be required, although some loans can qualify for alternatives or appraisal waivers |
| Financing contingency | None in a true cash contract structured without financing contingency | May apply according to the negotiated contract |
| Potential closing speed | Can be faster because there is no lender process | Depends partly on lender and loan requirements |
| Inspection and title due diligence | Still important | Still important |
| Proof of financial ability | Seller may request proof of funds | Preapproval and evidence of required cash can strengthen the offer |
The table illustrates why sellers sometimes view cash as simpler, but simplicity is only one component of an offer. Price and the remaining contractual terms still matter.
How Important Is the Financing Contingency?
The financing contingency can be one of the most important differences between two otherwise similar Florida offers.
From a financed buyer's perspective, appropriate financing protection can help address the risk that a mortgage cannot be obtained under the conditions required by the contract. From a seller's perspective, that same contingency represents a condition that must be resolved before the transaction reaches closing.
A financed buyer should not automatically waive important contractual protections simply to imitate a cash offer. The financial consequences can be substantial if the buyer later cannot obtain financing. Buyers should understand the contract with their licensed real estate professional, lender and appropriate legal professional before changing or waiving financing-related protections.
What Happens if the Florida Home Appraises Below the Purchase Price?
A low appraisal can create a significant difference between a cash buyer and a financed buyer, but the contract language matters.
For many mortgage transactions, the lender evaluates the property as collateral. Fannie Mae's lender guidance, for example, generally requires the lender to evaluate whether the property provides adequate collateral, although eligible loans may receive a value acceptance option instead of a traditional appraisal.
If the lender's valuation is insufficient for the requested financing, the buyer may need to explore available contractual and financing options. What the buyer can require, renegotiate or cancel depends on the actual contract and applicable loan program.
Does Florida Automatically Give Every Buyer a Purchase-Price Appraisal Contingency?
No. Florida Realtors states that the core Florida Realtors/Florida Bar contract does not automatically contain an appraisal-to-purchase-price contingency. Florida Realtors identifies its Appraisal Contingency rider as a way to negotiate separate appraisal protection.
The appraisal component associated with a financing contingency is also not necessarily identical to a separate purchase-price appraisal contingency. Florida Realtors explains this distinction in its financing contingency guidance.
Because appraisal rights depend heavily on contract language and, in some cases, the loan program, buyers should obtain transaction-specific guidance rather than relying on a general rule.
Can a Cash Buyer Skip the Appraisal?
Because there is no mortgage lender requiring collateral valuation, a true cash buyer generally does not need an appraisal for loan approval. That does not mean an appraisal has no value.
A cash buyer may independently choose to obtain an appraisal to help evaluate value. The buyer may also negotiate contractual appraisal protection if desired and accepted by the seller.
The decision to purchase without an appraisal should be made based on the buyer's circumstances, valuation information and risk tolerance. A licensed real estate professional can provide brokerage services and market information, while formal appraisal questions should be directed to an appropriately licensed appraiser.
Can Cash Buyers Close Faster in Florida?
Potentially. Removing mortgage underwriting, lender conditions and lender funding can make a shorter closing timeline possible. But cash does not eliminate every step required for a responsible Florida real estate transaction.
Depending on the transaction, buyers may still need time for:
- Home inspection
- Specialized inspections
- Title examination and closing preparation
- Condominium or homeowners association document review when applicable
- Survey work when applicable
- Insurance investigation
- Verification of funds and closing logistics
The fastest possible closing is not automatically the best closing date for either party. A seller may need time to move, coordinate another purchase or satisfy other contractual obligations.
How Common Are Cash Buyers in Florida in 2026?
Cash competition is not unusual in Florida. Florida Realtors' 2026 market outlook describes cash buyers as accounting for nearly one-third of transactions, with the trend particularly visible in coastal and metropolitan markets.
The organization's detailed statewide single-family data provides more context. During the first three months of 2026, 30.3% of Florida single-family closed sales were cash purchases. March's share was 28.5%, February's was 30.7%, and January's was 32.4%.
That means financed buyers remain responsible for the majority of statewide single-family purchases. Cash is important, but using a mortgage does not place a buyer outside the normal Florida market.
Why Are Cash Buyers Still Important When Mortgage Rates Are Elevated?
Borrowing costs create one obvious distinction between cash and financing. Freddie Mac reported that the national average rate for a 30-year fixed mortgage was 6.71% as of September 3, 2026. The 15-year fixed average was 6.04%.
Those are national survey averages rather than rates available to every Florida borrower. Actual mortgage pricing depends on the lender, borrower, loan type, property and market conditions.
Cash buyers avoid mortgage interest on the purchase unless they choose to finance the property later. Financed buyers, however, preserve more of their liquid capital instead of putting the entire purchase price into the property. Which approach is appropriate is a personal financial decision that should be reviewed with qualified financial, lending and tax professionals based on the buyer's circumstances.
Can a Financed Buyer Make an Offer More Competitive?
Yes. Financing does not prevent a buyer from presenting an attractive offer. The objective is to reduce avoidable uncertainty without taking risks the buyer does not understand or cannot afford.
1. Get Strong Mortgage Preapproval Early
A buyer who waits until finding the right home to begin financing may create unnecessary delays. Mortgage preapproval before serious home shopping can help establish the buyer's financing range and identify issues earlier.
Preapproval is not final loan approval, and buyers should confirm with their lender what financial or property-related conditions remain.
2. Have the Required Cash Ready
Financed buyers still need liquid funds for the deposit, down payment, closing expenses and potentially other transaction costs. Hunt Brothers Realty's 2026 down payment guide explains why buyers should budget beyond the down payment itself.
3. Understand the Seller's Priorities
Price may not be the seller's only priority. Timing, confidence in the closing, requested concessions and other terms can influence how competing offers are evaluated.
A licensed Florida real estate professional can communicate with the listing side within applicable rules to better understand which legitimate transaction terms matter to the seller.
4. Use a Realistic Closing Timeline
A financed buyer can ask the lender how quickly underwriting, appraisal and closing can realistically be completed. Promising an aggressive closing date that the lender cannot meet can create more risk rather than making the offer stronger.
5. Consider the Deposit Strategically
A seller may consider the deposit when evaluating an offer, but the amount should be chosen with a clear understanding of the contract and the circumstances under which the deposit could become disputed or at risk. Hunt Brothers Realty explains the difference between earnest money and a down payment.
6. Do Not Waive Protections Without Understanding the Consequences
Trying to make a financed offer look like cash by eliminating financing, appraisal or inspection protections can materially increase buyer risk. Contractual rights and deposit consequences should be understood before an offer is submitted or modified.
Legal questions about contract rights or waivers should be reviewed with a qualified Florida real estate attorney. Financing consequences should be discussed with the buyer's lender, and inspection risks with the appropriate licensed inspectors or other property professionals.
Can a Higher Financed Offer Beat a Lower Cash Offer?
Absolutely possible. Consider a simplified example in which a seller receives two offers:
| Terms | Buyer A | Buyer B |
|---|---|---|
| Price | $500,000 | $515,000 |
| Purchase method | Cash | Mortgage financing |
| Financing contingency | None | Yes |
| Closing | Flexible | Lender-confirmed schedule |
There is no universal answer about which offer the seller should choose. Buyer A provides less financing uncertainty. Buyer B offers $15,000 more but introduces mortgage-related conditions. The seller must evaluate the actual contracts and decide which combination of price and risk best meets the seller's objectives.
That is why describing cash as an automatic winner oversimplifies real-world negotiations.
Does a Cash Buyer Automatically Get a Discount?
No. A seller is not automatically obligated to accept less simply because the buyer is paying cash.
Cash can provide negotiating leverage when the seller places significant value on reduced financing uncertainty or a particular closing timeline. But the value of that advantage depends on the property, competing offers, market conditions and seller priorities.
A seller with multiple strong offers may have little reason to discount the price. A seller with a property that has been on the market longer may evaluate certainty and terms differently.
Does Paying Cash Mean You Should Skip Financing Entirely?
Not necessarily. Whether someone should use cash or mortgage financing is a broader financial decision, not simply a real estate negotiation question.
Paying cash can eliminate mortgage interest and monthly principal-and-interest payments, but it also places a large amount of capital into one property. Financing preserves more liquidity but creates borrowing costs and mortgage qualification requirements.
The appropriate choice can depend on liquidity needs, investment objectives, taxes, retirement planning, borrowing costs and other individual circumstances. Buyers should discuss those issues with qualified financial, tax and lending professionals rather than treating an offer strategy as personalized financial advice.
Do Cash Buyers Still Need Insurance in Florida?
A cash buyer does not have a mortgage lender requiring property insurance as a condition of the loan. That does not eliminate the financial risks associated with owning an uninsured or inadequately insured Florida property.
Insurance availability, coverage, exclusions, deductibles and premiums can vary substantially by property. Florida buyers should obtain property-specific insurance information and discuss appropriate coverage with a qualified insurance professional before making a purchasing decision, regardless of whether the purchase uses cash or financing.
What About Florida Condos?
Condominiums add another layer to the cash-versus-financing comparison. A borrower may qualify personally for a mortgage while the condominium project or specific unit still has to satisfy applicable lender and loan-program requirements.
Depending on the loan and property, lenders may review condominium documentation and project characteristics. A cash buyer does not need lender project approval, but that does not make association finances, reserves, insurance, structural information or assessments irrelevant.
Cash condo buyers should conduct their own appropriate due diligence rather than treating the absence of lender review as evidence that the condominium has no financial or structural concerns.
What Should Florida Sellers Compare When They Receive Cash and Financed Offers?
Sellers evaluating competing offers should look at the complete contracts rather than focusing exclusively on whether one buyer is paying cash.
- Purchase price: What is each buyer actually offering?
- Deposit: What deposit is being offered and when is it due?
- Proof of funds: Has the cash buyer demonstrated the ability to complete the transaction?
- Mortgage preparation: How far has the financed buyer progressed with a qualified lender?
- Financing terms: What financing contingency and deadlines apply?
- Appraisal terms: Is there separate appraisal protection or another valuation-related provision?
- Inspection terms: What inspection or due-diligence provisions are included?
- Closing date: Does the proposed schedule fit the seller's needs?
- Concessions: Is the buyer requesting seller-paid costs or other concessions?
- Overall execution risk: How many significant conditions remain before the transaction can close?
A licensed real estate professional can help a seller compare the real estate and negotiation aspects of competing offers. Legal interpretation of contractual rights or liabilities should be directed to a qualified Florida real estate attorney, while tax consequences should be discussed with an appropriate tax professional.
Which Buyer Has the Advantage in Different Situations?
| Situation | Potential Advantage | Why |
|---|---|---|
| Two offers at the same price and similar terms | Cash buyer | Less financing-related uncertainty |
| Financed offer is materially higher | Depends | Seller weighs additional price against financing and appraisal risk |
| Seller wants a very short closing | Often cash | No mortgage underwriting or lender funding process |
| Seller needs a later closing | Depends | Closing flexibility may matter more than speed |
| Financed buyer has strong preapproval and clean terms | More competitive financed offer | Preparation can reduce perceived financing uncertainty |
| Property presents financing challenges | Potentially cash | Cash does not require lender collateral approval, although buyer due diligence remains important |
What Mistakes Should Cash Buyers Avoid?
Having the ability to pay cash does not make normal property due diligence unnecessary. Common risks include moving too quickly, assuming an appraisal has no value, overlooking insurance costs or treating the absence of lender scrutiny as proof that the property is financially or physically sound.
Cash buyers should still consider appropriate inspections, title work, surveys when relevant, association documents, flood information, insurance, permits and other property-specific issues. Hunt Brothers Realty's guide to negotiating repairs on an as-is Florida home explains why contract structure and due diligence remain important even when a property is sold as-is.
What Mistakes Should Financed Buyers Avoid?
A financed buyer can weaken an otherwise good offer by being unprepared. Waiting to contact a lender, misunderstanding cash-to-close requirements, making major financial changes during underwriting or promising contract deadlines that the lender cannot meet can create unnecessary risk.
Financed buyers should also avoid assuming the largest loan for which they qualify is automatically an appropriate home-buying budget. Florida ownership costs can include property taxes, homeowners insurance, flood insurance when applicable, HOA or condominium fees, assessments and ongoing maintenance.
So, Who Really Has the Advantage in Florida in 2026?
If two buyers offer the same price with otherwise comparable terms, a cash buyer will often have an advantage because there is no mortgage approval process standing between contract and closing.
But real offers are rarely identical. A financed buyer can offer more money, stronger timing, fewer seller concessions or other terms that shift the comparison. A seller may reasonably prefer the economics of a strong financed offer over the simplicity of a lower cash offer.
The 2026 Florida market also gives buyers more nuance than the simple bidding-war narrative of earlier years. Florida Realtors reported continued growth in pending and closed sales during summer 2026 even as buyers adapted to mortgage rates in the mid-6% range. Negotiating conditions remain property-specific, which makes current local inventory, competition and seller motivation important when deciding how aggressively to structure an offer.
The Bottom Line: Cash Has an Edge, but Financing Can Still Compete
Cash remains a meaningful advantage in Florida because it removes mortgage approval and lender underwriting from the purchase. With nearly three in ten statewide single-family transactions closing in cash during March 2026, financed buyers should expect to encounter cash competition in some segments of the market.
That does not mean a financed buyer should automatically overpay or surrender important protections. Strong preapproval, realistic deadlines, adequate cash reserves and a carefully structured offer can make financing highly competitive.
For sellers, the lesson is equally important. The highest offer and the cash offer are not automatically the same as the strongest overall offer. Each contract should be evaluated as a complete package of price, terms, timing and transaction risk.
Buying or Selling a Florida Home in 2026?
Hunt Brothers Realty helps Florida Gulf Coast buyers and sellers evaluate real estate offers within the scope of professional real estate brokerage services. Buyers can learn more about what a Florida buyer's agent does, review Florida Gulf Coast communities, or contact Hunt Brothers Realty to discuss a property search or sale.
Informational notice: This article provides general real estate and educational information and is not individualized legal, financial, tax, insurance, lending, appraisal, inspection or other professional advice. The advantages and risks of cash and financing depend on the specific property, buyer, seller, loan program and executed contract. Buyers and sellers should review transaction strategy with their licensed real estate professionals. Financing and qualification questions should be reviewed with a qualified mortgage professional, insurance with a qualified insurance professional, valuation questions with an appropriately licensed appraiser when needed, tax or financial consequences with the appropriate qualified professionals, and questions involving contract rights, contingencies, deposits, title or other legal matters with a qualified Florida real estate attorney or other appropriate legal professional.
Sources
- Florida Realtors, 2026 Real Estate Trends: Florida Housing Market Stabilizing as Buyer Demand Builds
- Florida Realtors, March 2026 Florida Single-Family Market Detail
- Florida Realtors, Analyzing the Financing Contingency
- Florida Realtors, Financing Contingency FAQs
- Florida Realtors, Florida Real Estate Contract Guidance
- Florida Realtors, Florida Buyers Move Ahead Without Waiting on Mortgage Rates
- Freddie Mac, Primary Mortgage Market Survey
- Fannie Mae Selling Guide, Lender Responsibilities and Appraisal Requirements
- Hunt Brothers Realty, Should I Get Preapproved Before Looking at Houses?
- Hunt Brothers Realty, How Much Should You Put Down on a House?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1386
- Anna Maria Island 62
- Bird Key 3
- Bradenton 39
- Buying a Home 544
- Casey Key 2
- Clearwater 5
- Condos & HOA Living 453
- Ellenton 4
- Englewood 5
- First Time Homebuyers 615
- Foreclosures 3
- Homeownership 590
- Lakewood Ranch 15
- Lido Key 24
- Longboat Key 65
- Luxury/Waterfront Properties 529
- Market Updates & Trends 267
- Mortgages & Financing 27
- Move-Up Buyers 20
- Neighborhood Guides 405
- New Construction 21
- Palmetto 2
- Parrish 4
- Port Charlotte 7
- Punta Gorda 11
- Real Estate Investing 461
- Relocation to Florida 513
- Safety Harbor 2
- Sarasota - Downtown 107
- Selling a Home 134
- Siesta Key 87
- St. Petersburg 3
- Tierra Verde 3
- Vacation & Second Homes 645
- Venice 20
- Wellen Park 7
Recent Posts