How Can I Find Homes for Sale That Match My Budget?
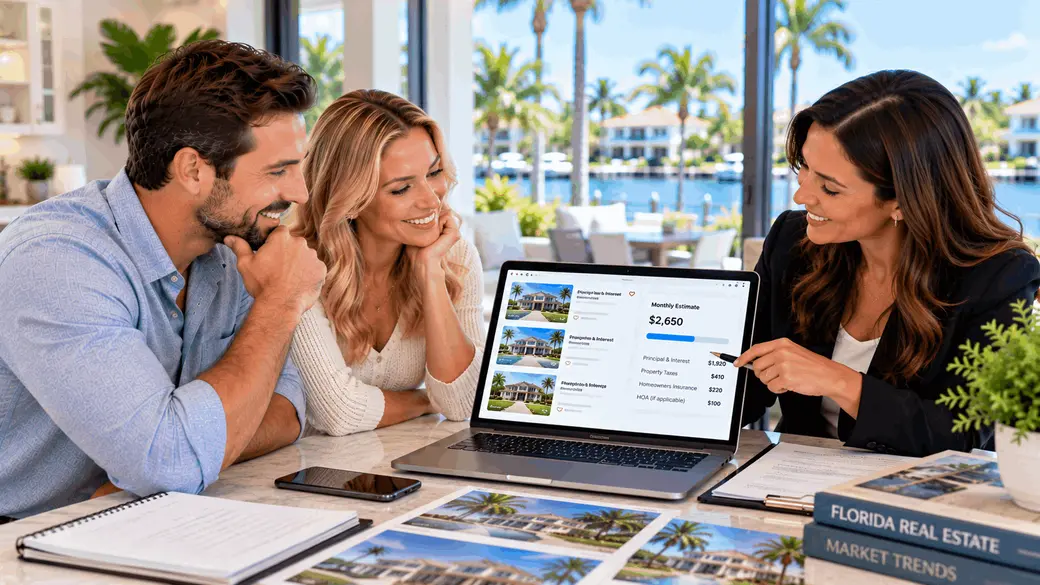
To find homes for sale that truly match your budget, start with the total monthly housing cost you are comfortable paying, not simply the highest purchase price a lender may approve. Account for mortgage principal and interest, property taxes, homeowners insurance, applicable flood or mortgage insurance, HOA or condominium fees and expected maintenance. Then get pre-approved if you plan to finance, establish a target price range and search within it. As you compare individual homes, update the numbers because two properties with the same asking price can have substantially different monthly ownership costs.
Florida buyers can also use the Hunt Brothers Realty Florida Buyer Resource Center to learn more about financing, contracts, buyer representation and preparing for a purchase.
Quick Answers About Finding Homes That Match Your Budget
How do I know what home price I can afford?
Start with the total monthly housing payment that comfortably fits your finances, savings goals and other obligations. Then estimate taxes, insurance, association fees and other property costs before determining how much of that payment can go toward mortgage principal and interest. A qualified mortgage professional can help translate that budget into a potential financing range.
Should I get pre-approved before searching for homes?
If you expect to use mortgage financing, pre-approval before beginning a serious home search can help establish a preliminary financing range and identify potential lending issues. It does not guarantee final loan approval, and the maximum amount a lender is willing to lend does not have to become your personal spending limit.
Should I search up to my maximum pre-approval amount?
Not automatically. The Consumer Financial Protection Bureau advises buyers to focus on what they can comfortably afford rather than simply how much they qualify to borrow. Your preferred budget may be lower than your maximum pre-approval if you want additional room for savings, travel, repairs, other debts or future expenses.
Why can two homes at the same price have different monthly costs?
Property taxes, insurance, flood coverage, HOA or condominium fees and maintenance requirements can vary significantly. One $500,000 home could therefore cost considerably more per month to own than another $500,000 home.
Should I leave room in my budget for repairs?
Yes. Homeownership includes expenses beyond the mortgage payment. The appropriate reserve depends on the property's age, condition and systems, but buyers should consider maintenance and future repairs rather than using every available dollar for the purchase itself.
Can a real estate agent search for homes within my exact budget?
Yes. A real estate professional can structure a property search around your target purchase-price range, locations, property types and features. The search becomes more useful when you also identify costs such as HOA fees, condominium assessments, CDD assessments and other property characteristics that could affect affordability.
What if I cannot find enough homes in my original price range?
Before increasing your budget, consider adjusting location, property type, size, age, lot characteristics or optional features. Expanding the search geographically or considering condos, townhomes or smaller homes may create additional choices without increasing the amount you intend to spend.
Start With the Monthly Payment, Not the Listing Price
A common way to begin a home search is to choose a price, such as $400,000 or $600,000, and start browsing listings below that number. That is simple, but it can overlook an important part of affordability.
Your purchase price is not your monthly housing cost.
The Consumer Financial Protection Bureau recommends considering the complete monthly payment, which can include:
- Mortgage principal
- Mortgage interest
- Property taxes
- Homeowners insurance
- Flood or other supplemental insurance when applicable
- Mortgage insurance when applicable
- HOA or condominium fees when applicable
Utilities, maintenance and future repairs may not appear in the mortgage payment, but they still affect what you can comfortably afford to own.
What Is the Difference Between What I Qualify for and What I Can Afford?
They are not necessarily the same number.
A mortgage lender evaluates your finances using its underwriting requirements and determines how much it may be willing to lend. Your personal budget has a different purpose. It reflects how much you are comfortable spending while still paying other bills and pursuing savings, retirement, travel, education or other priorities.
CFPB specifically cautions buyers that the amount they can borrow is different from the amount they can comfortably repay without putting too much pressure on the rest of their budget.
That is why a buyer approved for $600,000 may intentionally decide to search between $475,000 and $525,000. There is no requirement to shop at the top of a pre-approval.
Should I Get Pre-Approved Before Setting My Search Range?
For buyers planning to finance a purchase, pre-approval is generally useful before a serious property search. It can provide preliminary information about the loan amount a lender may consider and may uncover financing questions before you find a home you want to buy.
Hunt Brothers Realty explains the process in Should I Get Pre-Approved Before Looking at Homes in Florida?
Pre-approval is not final loan approval. The property itself, appraisal, insurance, underwriting, your continued financial qualification and loan-program requirements can all matter later in the process.
Financing terms are individual to the borrower and property. Buyers should review their target payment, down payment, loan choices, rates and qualification details with qualified mortgage professionals before making financing decisions.
How Should I Set My Home-Search Price Range?
Once you understand your personal budget and preliminary financing, turn those numbers into a practical search range.
For example, suppose your financial analysis suggests you are comfortable purchasing around $500,000. Instead of automatically searching every property from $0 to $500,000, you might initially focus on a narrower band that contains homes likely to meet your needs.
The purpose is not to create an arbitrary cutoff. It is to avoid spending most of your time looking at homes that are either financially unrealistic or far below the level needed to satisfy your priorities.
Should I Search Slightly Above My Budget?
Sometimes it can be useful to monitor properties modestly above your target price, but that should not be confused with assuming the seller will reduce the price to fit your budget.
A property listed slightly above your range might later receive a price adjustment or have negotiating circumstances that make it relevant. Another seller may have little interest in accepting less than the asking price.
Keep your primary search centered on properties you can realistically purchase. A secondary alert can monitor a modestly higher range without encouraging you to rely on an uncertain future negotiation.
Why Should I Compare Total Ownership Cost Between Homes?
Imagine two homes are both listed at $450,000.
Home A has no HOA but requires more exterior maintenance and may have higher insurance costs. Home B is in a planned community with an HOA fee but has newer major systems. A condominium at the same price could add a substantial monthly association assessment but shift some exterior maintenance responsibilities to the association.
The listing prices are identical. The ownership costs are not.
For a more complete breakdown, read The True Cost of Buying a Home in Florida: What to Budget Beyond the Mortgage.
Which Florida Housing Costs Can Change My Search Budget?
Florida buyers should pay particular attention to costs that vary by location and property type.
Property Taxes
Do not assume the seller's current tax bill will equal your future bill. Ownership changes, exemptions, assessed value and other factors can affect property taxes. Obtain a property-specific estimate from the applicable county property appraiser and consult a qualified tax professional when individual tax guidance is needed.
Homeowners Insurance
Insurance can vary substantially between homes based on construction, age, roof, location, wind mitigation characteristics, claims history and other underwriting factors. Obtain property-specific quotes rather than applying one insurance estimate to every listing.
Flood Insurance
Flood coverage may be required by a lender for some properties and may be considered voluntarily in other circumstances. Flood-zone designation alone does not tell you the cost of coverage. Verify the property's flood information and obtain an insurance quote when evaluating the budget.
HOA and Condominium Fees
Association assessments can materially affect monthly affordability. Buyers should understand the current regular assessment, what it covers, the association's financial condition and whether special assessments or approved increases are relevant to the property.
CDD Assessments
Some Florida master-planned communities have Community Development District assessments that may appear on the property-tax bill. Where applicable, include those costs when comparing homes.
Maintenance
Pools, roofs, air-conditioning systems, landscaping, seawalls and other property components can create very different maintenance profiles. A lower-priced home needing major work may not be less expensive to own than a higher-priced property in better condition.
How Much Cash Do I Need Besides the Down Payment?
Do not use the entire amount of available cash to calculate your down payment without considering other purchase expenses.
CFPB currently suggests using approximately 2% to 5% of the purchase price as a general planning estimate for closing costs, excluding the down payment. Actual costs can differ based on the mortgage, lender, property, transaction and location.
Other cash needs can include:
- Inspections
- Appraisal costs when applicable
- Insurance premiums and prepaid items
- Escrow funding when applicable
- Moving expenses
- Immediate repairs or improvements
- Furniture and household purchases
- Post-closing emergency reserves
Your lender and closing professionals can provide transaction-specific estimates as the purchase progresses.
How Can Search Filters Help Me Stay on Budget?
Once you have a realistic price range, use search filters to reduce listings that do not fit your needs.
Useful filters can include:
- Minimum and maximum price
- City or neighborhood
- Single-family home, condo, villa or townhome
- Bedrooms and bathrooms
- Garage or parking requirements
- Pool preferences
- Waterfront preferences
- New construction or resale
- Home size
- Lot characteristics
Some important affordability factors, particularly insurance costs, future taxes and association finances, cannot be reliably reduced to a simple search filter. Those require additional property-level research.
Should I Separate Must-Haves From Nice-to-Haves?
Yes. This can be one of the most effective ways to keep a search realistic.
A buyer's list might look like this:
| Must-Haves | Nice-to-Haves |
|---|---|
| Minimum number of bedrooms | Extra guest room |
| Acceptable commute or location | Specific neighborhood |
| Required parking | Three-car garage |
| Accessible layout if needed | Preferred architectural style |
| Total ownership cost within budget | Private pool |
When inventory is limited, adjusting a nice-to-have can open significantly more options without compromising the features that actually matter to your daily life.
What Should I Change if Nothing Fits My Budget?
If your search produces few or no realistic options, increasing the budget is only one possible response.
Consider changing one variable at a time:
- Location: Search adjacent communities or a slightly larger geographic area.
- Property type: Compare single-family homes with townhomes, villas or condos.
- Size: Consider whether slightly less square footage would still work.
- Age: Compare newer construction with established homes.
- Features: Decide whether a pool, waterfront location, oversized lot or extra garage space is essential.
- Condition: Consider whether cosmetic improvements are acceptable while remaining cautious about significant repair costs.
The goal is to discover which compromise gives you more choices with the least effect on your priorities.
Can Location Help Me Get More Home for My Budget?
Location can have a substantial effect on what a particular budget can buy. A price range that produces a small condo near the coast may produce a larger home farther inland. A downtown budget can look very different from the same budget in a suburban or master-planned community.
Use Hunt Brothers Realty's Explore Communities resource to compare Florida locations and identify areas that may fit your property and lifestyle priorities.
Should I Set Up Alerts for New Listings?
Once your criteria are defined, listing alerts can help you monitor new inventory that enters your target range. This is more efficient than repeatedly searching broad groups of properties that do not fit your budget.
A focused search can monitor your preferred locations, price range, property type and essential features. A real estate professional can then help distinguish between listings that simply meet the filters and properties that appear to fit the broader ownership budget.
What Should I Recalculate Before Making an Offer?
A general search budget is only the beginning. Before making an offer, update the numbers for the actual property.
Review or estimate:
- Expected loan amount and current rate assumptions
- Estimated principal and interest
- Estimated property taxes after purchase
- Property-specific insurance quotes
- Flood insurance when applicable
- Mortgage insurance when applicable
- HOA, condominium or CDD assessments
- Known or proposed special assessments
- Estimated closing costs and cash required
- Expected immediate repairs
- Ongoing maintenance
This property-specific calculation is much more useful than assuming every home under your maximum listing-price filter is equally affordable.
A Simple Budget-Based Home Search Strategy
- Choose a comfortable monthly housing budget. Base it on your own finances and priorities.
- Estimate the complete payment. Include taxes, insurance and applicable association costs.
- Get pre-approved if financing. Use the lender's information as part of the planning process, not an instruction to spend the maximum.
- Determine available cash. Account for the down payment, closing expenses and reserves.
- Create a target price range. Focus your primary search on realistically affordable properties.
- Separate must-haves from preferences. Know which criteria can change if inventory is limited.
- Set focused listing alerts. Monitor new homes matching your criteria.
- Compare total ownership costs. Do not compare properties using price alone.
- Recalculate before offering. Use property-specific taxes, insurance, fees and financing assumptions.
The Best Home Budget Is One You Can Comfortably Own
Finding homes that match your budget is not simply a matter of entering a maximum price into a search box. A useful budget accounts for the money required to purchase the property, the monthly cost of owning it and the expenses that may arise after closing.
Once you understand those numbers, the home search becomes more focused. You can compare neighborhoods, property types and features while keeping affordability at the center of the decision rather than discovering the true cost after you have already fallen in love with a home.
Start a Budget-Focused Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty can help you organize a Florida property search around your preferred price range, locations, property types and real estate priorities. Start with the Florida Buyer Resource Center, compare locations through Explore Communities, or contact Hunt Brothers Realty to discuss your home-search criteria.
Informational notice: This article provides general real estate and educational information only and is not individualized financial, lending, tax, insurance, legal, inspection or other professional advice. Affordability, mortgage qualification, rates, closing costs, taxes, insurance and cash requirements vary by buyer, property, lender and transaction. Buyers should review financing with qualified mortgage professionals, obtain property-specific insurance information from licensed insurance professionals, consult qualified tax or legal professionals when individualized guidance is needed, and use appropriate inspectors or other qualified professionals when evaluating property condition.
Sources
- Consumer Financial Protection Bureau, Figure Out How Much You Want to Spend
- Consumer Financial Protection Bureau, Decide How Much You Want to Spend on a Home
- Consumer Financial Protection Bureau, Find the Right Home
- U.S. Department of Housing and Urban Development, Buying a Home
- Hunt Brothers Realty, Florida Buyer Resource Center
- Hunt Brothers Realty, Should I Get Pre-Approved Before Looking at Homes in Florida?
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2152
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1211
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1127
- Ellenton 6
- Englewood 11
- First Time Homebuyers 1320
- Foreclosures 5
- Home Selling 6
- Homeownership 1344
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1283
- Market Updates & Trends 804
- Mortgages & Financing 51
- Move-Up Buyers 23
- Neighborhood Guides 919
- New Construction 36
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1200
- Relocation to Florida 1239
- Safety Harbor 3
- Sarasota 86
- Sarasota - Downtown 163
- Selling a Home 146
- Siesta Key 92
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1393
- Venice 209
- Wellen Park 20
Recent Posts