Can I Buy a House If I’m Self-Employed?
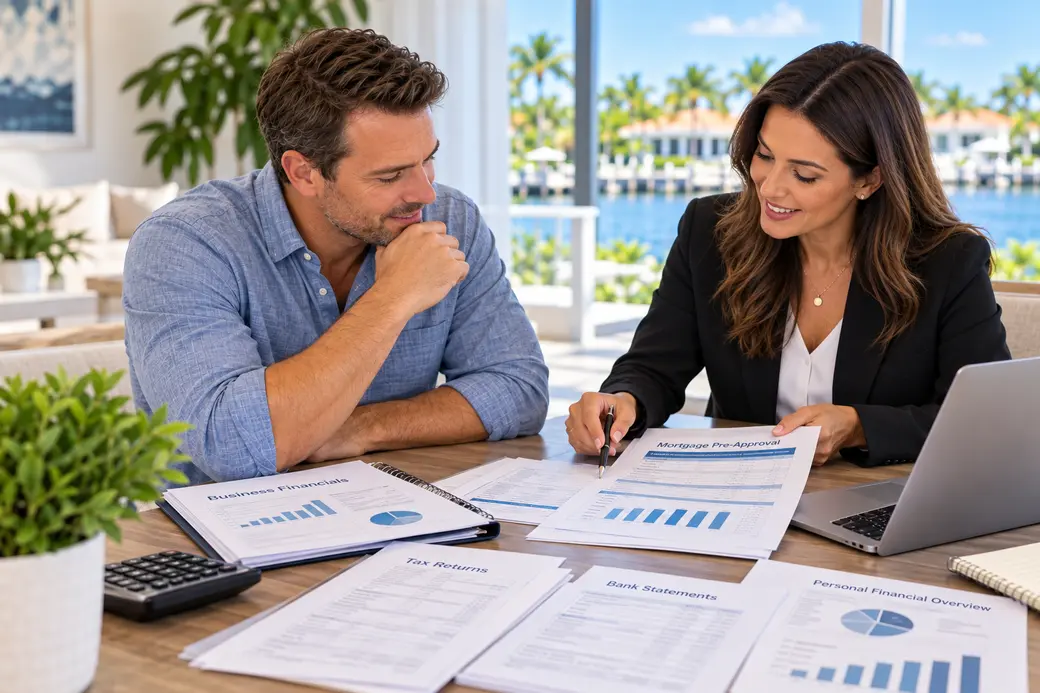
Yes, being self-employed does not prevent you from buying a house or qualifying for a mortgage. The difference is that a lender may need to analyze your income differently from a borrower who receives a regular salary and W-2. Self-employed buyers may be asked for personal and business tax information, documentation showing the business is active, and records that help the lender determine whether the income is stable and likely to continue. The amount you can qualify to borrow may therefore depend less on gross business revenue and more on the qualifying income the lender can document under the specific mortgage program.
Mortgage requirements vary by lender, loan program, ownership structure and borrower circumstances. Self-employed buyers should discuss their actual tax returns, business structure, debts, available assets and intended purchase with a qualified mortgage professional before assuming what they will qualify for. Hunt Brothers Realty's mortgage preapproval guide for Florida homebuyers explains why early financing preparation can make a home search more useful.
Quick Answers About Buying a House When You’re Self-Employed
Can Self-Employed Buyers Get a Regular Mortgage?
Yes. Self-employed borrowers can potentially qualify for conventional and other mortgage programs if they meet the applicable underwriting requirements. The lender generally needs to establish that qualifying income is documented, stable and reasonably expected to continue.
How Long Do I Need to Be Self-Employed?
A two-year earnings history is a common underwriting benchmark, but it is not an absolute rule for every mortgage. For example, Fannie Mae guidance can permit consideration of less than two years of self-employment when there is at least a full year of income from the current business and supporting prior experience in the same or a similar field. Eligibility depends on the complete loan file and program.
Will the Lender Look at My Tax Returns?
Often, yes. Depending on the loan and borrower, lenders may review personal federal tax returns, applicable business returns, schedules or IRS transcripts. Documentation requirements can be reduced in certain circumstances or through applicable automated verification, so ask the lender for a personalized checklist.
Does My Business Revenue Equal My Mortgage Income?
Usually not. Gross business revenue is different from the income a mortgage underwriter may use for qualification. The lender may analyze expenses, taxable income, business distributions, trends and other tax-return items to determine the amount of income that can reasonably support the mortgage.
Do Tax Write-Offs Affect Mortgage Qualification?
They can. Business deductions that reduce taxable income may also affect the income a lender can use, although mortgage underwriting can treat certain tax-return items differently depending on the applicable guidelines. A mortgage professional should review your actual returns before you estimate your qualifying income yourself.
Can I Use Money From My Business for the Down Payment?
Potentially, but additional analysis may be required. When business assets are used for a down payment, closing costs or reserves, a lender may need to determine that removing those funds will not negatively affect the business. Do not transfer substantial business funds for a purchase without first discussing the documentation and underwriting consequences with your lender.
Should I Get Preapproved Before Shopping for Homes?
For a self-employed buyer planning to finance the purchase, early preapproval can be particularly useful. It gives the lender an opportunity to examine how your income will be treated before you select a property and helps you establish a more realistic search range.
Why Is Getting a Mortgage Different When You’re Self-Employed?
The primary difference is income verification. A salaried employee may have a relatively straightforward trail of pay statements and W-2 income. A self-employed borrower can have income flowing through a sole proprietorship, partnership, LLC, S corporation or corporation, with business expenses and tax reporting affecting how earnings appear on the tax returns.
Under current Fannie Mae conventional guidance, a borrower with an ownership interest of 25% or more in a business is treated as self-employed for underwriting purposes. The lender's analysis can include the stability of the income, the financial strength of the business and whether the business is expected to continue producing enough income to support the borrower's obligations.
That does not mean self-employed borrowers are viewed negatively. It means the lender needs a reliable method for turning business and tax information into qualifying monthly income.
How Much Self-Employment History Do Mortgage Lenders Want?
Two years is a common benchmark because a longer earnings history gives an underwriter more information about income stability and trends. Fannie Mae generally requires lenders to obtain a two-year history of prior earnings when evaluating self-employed income.
However, a buyer who has been self-employed for less than two years should not automatically assume a mortgage is impossible. Under Fannie Mae guidance, income with a shorter history may be considered when the most recent tax return reflects at least 12 months of self-employment income and the borrower can document prior earnings at a comparable or higher level in the same field or a similar occupation.
Other loan programs and lenders can have different rules. Ask a qualified mortgage professional to evaluate your timeline rather than waiting an arbitrary number of years without knowing whether it is necessary.
What Documents Might a Self-Employed Buyer Need?
Documentation depends on the loan program, lender, type of business, ownership percentage, length of self-employment and automated underwriting findings. A self-employed buyer may need to provide more income documentation than a borrower whose income comes entirely from a fixed salary.
Depending on the circumstances, a lender may request items such as:
- Personal federal income tax returns
- Applicable business federal income tax returns
- Schedule C, Schedule E or Schedule K-1 information when applicable
- IRS tax transcripts
- Business license or other evidence of business existence
- Recent business bank statements when required
- Profit and loss information when required
- Balance-sheet or liquidity information when relevant
- Personal bank and investment statements
- Documentation of down-payment and closing funds
- Information concerning existing personal or business debts
This is not a universal mortgage-document checklist. Some borrowers will need fewer items and others will need additional records. Ask the lender what is required for your specific loan and business structure before assembling unnecessary documents.
How Does a Lender Calculate Self-Employment Income?
Mortgage qualifying income can look different from both business revenue and the amount of money you transfer into your personal account. The underwriter typically analyzes tax documentation under the applicable loan guidelines to identify income that is stable, recurring and available to support the mortgage.
For a business owner, that analysis can include year-to-year trends in gross income, expenses and taxable income. In certain business structures, an underwriter may also need to determine whether income reported on a tax return has actually been distributed to the borrower or whether the business has enough liquidity to support those distributions.
Why Can My Qualifying Income Be Lower Than Expected?
A business can generate substantial gross revenue while reporting a considerably smaller amount of taxable income after expenses. Mortgage underwriting is designed to determine how much income can reasonably be relied upon for the borrower's personal housing obligation, not simply how much money moved through the business during the year.
Do not attempt to redesign your tax strategy solely from a mortgage article. Tax consequences are individualized, and tax planning should be discussed with a qualified tax professional or CPA. Mortgage qualification questions should be reviewed separately with your lender so you understand how the lender will interpret your filed returns.
What If My Business Income Increased Recently?
Increasing income can be relevant, but the lender may still examine historical earnings and the sustainability of the increase. Mortgage underwriting generally focuses on income that can be documented as stable and reasonably expected to continue rather than assuming a recent strong month or quarter will continue indefinitely.
If your business changed substantially, ask the lender whether updated profit and loss information or other current documentation will be needed. Requirements can depend on how long it has been since the most recent tax return and the trends shown in the business.
What If My Self-Employment Income Declined?
Declining income can require additional lender analysis because the underwriter needs to determine what amount of income, if any, can reasonably be expected to continue. A two-year average may not automatically solve the issue if the more recent year shows a significant downward trend.
If your recent tax returns show lower income, discuss the situation with a mortgage professional before establishing a home-search price range. The lender can explain which income it can currently use and whether additional documentation is needed.
Can I Use Business Funds for My Down Payment and Closing Costs?
Business assets can potentially be relevant to a home purchase, but withdrawing them may require additional underwriting. Under Fannie Mae guidance, when a borrower is using self-employment income to qualify and also intends to use business assets for the down payment, closing costs or reserves, the lender must analyze whether removing those funds will negatively affect the business.
That analysis may involve business bank statements, cash-flow information or a current balance sheet. The practical lesson is simple: do not move large amounts between business and personal accounts simply because you have found a house you like. Ask the lender first what records will be needed and how the transfer could affect underwriting.
Does Being Self-Employed Mean I Need a Bigger Down Payment?
Not necessarily. Down-payment requirements depend on the mortgage program, property, borrower qualification and other underwriting factors rather than self-employment alone. A self-employed borrower who meets the applicable program requirements may qualify for financing without automatically making a larger down payment simply because they own a business.
Ask a lender to compare actual loan options using your circumstances. Hunt Brothers Realty's Florida home-affordability guide explains why down payment, mortgage terms, taxes, insurance and association costs should be considered together rather than focusing on the purchase price alone.
What Credit Score Does a Self-Employed Buyer Need?
There is no single credit-score requirement that applies to every self-employed homebuyer. Minimum requirements and pricing can depend on the loan program, lender, loan-to-value ratio and complete borrower profile.
Self-employment does not create its own universal credit-score category. Ask the lender which programs are available based on your credit profile, income documentation, debts, assets and intended property.
How Do My Debts Affect Mortgage Qualification?
Mortgage underwriting considers existing financial obligations in addition to income. For self-employed buyers, a lender may also need to determine whether particular business debts are obligations of the business, the individual borrower or both.
Do not assume a debt is excluded simply because it relates to your company. Provide accurate documentation and ask the lender how each obligation is being treated when calculating qualification.
Should I Get Preapproved Earlier If I’m Self-Employed?
Getting preapproved before becoming deeply involved in a home search can be particularly valuable for a self-employed buyer because it gives the lender time to review how your income will be documented. A quick online affordability calculator may not account correctly for business deductions, distributions, ownership structure or income trends.
Hunt Brothers Realty's prequalification versus preapproval guide explains that documentation can vary by borrower and that a self-employed buyer may have different requirements from someone with straightforward salary income.
What Should I Ask the Lender During Preapproval?
- How are you calculating my qualifying self-employment income?
- Which tax years and business returns do you need?
- Do you need a current profit and loss statement?
- Are there concerns about declining or variable income?
- How are business debts being treated?
- Can I use business assets toward closing?
- Would using business funds require additional cash-flow analysis?
- What down-payment options are available?
- What reserves will I need?
- What documents might need to be updated before closing?
Does Preapproval Mean My Mortgage Is Guaranteed?
No. Preapproval is not final loan approval. Once you have a property under contract, the lender may need to update borrower documentation and evaluate the home, appraisal, title, insurance and other transaction-specific requirements.
Self-employed borrowers should also expect the lender to confirm that the business continues to exist during the loan process. Current Fannie Mae guidance requires verification of the borrower's business within the applicable period before the note date when self-employment income is being used to qualify.
Avoid Major Financial Changes Before Closing
Before changing the business structure, taking on significant new debt, moving substantial funds, changing your compensation method or making another major financial decision during a mortgage transaction, ask your lender whether the change could affect qualification or documentation.
Tax, accounting and business decisions should be made with appropriately qualified professionals based on your broader circumstances, not solely to obtain a mortgage.
How Much House Can a Self-Employed Buyer Afford?
The lender's maximum approval and your comfortable home budget are two separate numbers. This is particularly important for business owners whose monthly income, taxes or cash needs may vary during the year.
A Florida housing budget can include:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- Flood insurance when applicable
- Mortgage insurance when applicable
- HOA or condominium assessments
- CDD assessments where applicable
- Utilities
- Repairs and routine maintenance
- Pool, landscaping or other property-specific expenses
The Hunt Brothers Realty guide to the true cost of buying a home in Florida explains why buyers should evaluate total ownership expenses rather than the mortgage payment in isolation.
How Much Cash Will I Need to Buy?
Your cash requirement can include more than the down payment. Closing costs, prepaid expenses, initial escrow funding and financial reserves can also affect how much money you need available to complete the transaction.
Hunt Brothers Realty's guide to buyer closing costs explains the difference between closing costs, down payment and total Cash to Close. The exact amount should ultimately come from the lender's transaction-specific Loan Estimate and closing documents rather than a generic online percentage.
Can a Self-Employed First-Time Buyer Qualify?
Being both self-employed and a first-time buyer does not automatically prevent mortgage qualification. The lender still evaluates the applicable income, credit, assets, debts, loan program and property requirements.
The most useful first step is usually to have a mortgage professional review the actual business and tax documentation. That allows you to begin the home search with financing assumptions based on your circumstances rather than on a calculator designed around salaried employment.
Frequently Asked Questions About Self-Employed Homebuyers
Can I Get a Mortgage With Only One Year of Self-Employment?
Possibly. Under Fannie Mae conventional guidance, less than two years may be considered when there is at least a full year of self-employment income from the current business and supporting prior experience at a comparable or higher income level in the same or a similar field. Other loan programs can differ.
Do I Need Two Years of Tax Returns?
Two years of returns are commonly used for self-employed income analysis, but current Fannie Mae guidance allows reduced return documentation in specified situations, including certain businesses with a longer documented history. Automated underwriting and loan-program requirements can also affect documentation, so ask your lender what applies to you.
What If I Pay Myself a Salary From My Own Company?
Receiving a salary from your company does not necessarily mean the lender ignores your ownership interest. Under Fannie Mae guidance, a borrower with at least 25% ownership is treated as self-employed, so the lender may still need to analyze the business and applicable tax returns.
Can I Qualify if I Own an LLC?
Potentially. The LLC itself does not determine mortgage eligibility. The lender will consider ownership, how the entity is taxed, the income being used, business performance and the documentation required under the chosen loan program.
Can I Get a Loan If My Income Changes From Month to Month?
Variable monthly income is common in self-employment. The lender generally looks at documented historical income and trends rather than requiring every month to be identical. Significant declines or recent changes can require additional analysis.
Should I Change How I File My Taxes Before Buying?
Tax filing and tax planning are individualized financial matters. A mortgage lender can explain how filed returns affect qualification, but decisions about deductions, entity structure or tax strategy should be reviewed with a qualified CPA or tax professional based on your broader circumstances.
Self-Employment Does Not Put Homeownership Out of Reach
Self-employed buyers purchase homes every day. The mortgage process can simply require a more detailed look at how income is earned, reported and expected to continue. Tax returns, business structure, income trends, debts and the source of closing funds can all become part of that analysis.
The most useful approach is to involve a mortgage professional before setting a firm home-shopping budget. Once the lender has reviewed the relevant documentation, you can compare homes using a financing range grounded in your actual circumstances while separately deciding what monthly ownership cost you are comfortable carrying.
Plan Your Florida Home Purchase With Hunt Brothers Realty
Hunt Brothers Realty helps buyers organize the real estate side of a Florida Gulf Coast purchase while coordinating with the mortgage, insurance, inspection, title and other professionals involved in the transaction. Explore the Florida Buyer Resource Center, review the mortgage preapproval guide, or contact Hunt Brothers Realty when you are ready to begin your home search.
Informational notice: This article provides general real estate and educational information only and is not individualized lending, financial, tax, accounting, legal or other professional advice. Mortgage programs, underwriting requirements, qualifying-income calculations, documentation, rates, down payments and loan eligibility vary by lender, borrower and transaction and can change over time. Self-employed buyers should review financing with a qualified mortgage lender or loan professional and direct tax, accounting, business-structure or legal questions to the appropriate qualified CPA, tax professional, attorney or other professional before making decisions based on their individual circumstances.
Sources
- Fannie Mae, Underwriting Factors and Documentation for a Self-Employed Borrower
- Fannie Mae, Self-Employment Documentation Requirements for a Business
- Fannie Mae, Tax Return and Transcript Documentation Requirements
- Fannie Mae, Verification of Self-Employment Before Closing
- U.S. Department of Housing and Urban Development, FHA Single Family Housing Policy Handbook 4000.1
- Consumer Financial Protection Bureau, Applying for a Mortgage Loan
- Hunt Brothers Realty, Mortgage Prequalification vs. Preapproval
- Hunt Brothers Realty, How Much House Can You Afford in Florida?
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
Contact Hunt Brothers Realty
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3
Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1706
- Anna Maria Island 81
- Bird Key 3
- Bradenton 190
- Buying a Home 826
- Casey Key 2
- Clearwater 6
- Condos & HOA Living 726
- Ellenton 4
- Englewood 5
- First Time Homebuyers 912
- Foreclosures 3
- Homeownership 907
- Lakewood Ranch 16
- Lido Key 27
- Longboat Key 76
- Luxury/Waterfront Properties 844
- Market Updates & Trends 440
- Mortgages & Financing 37
- Move-Up Buyers 20
- Neighborhood Guides 585
- New Construction 28
- Palmetto 2
- Parrish 5
- Port Charlotte 9
- Punta Gorda 13
- Real Estate Investing 774
- Relocation to Florida 823
- Safety Harbor 2
- Sarasota 35
- Sarasota - Downtown 146
- Selling a Home 140
- Siesta Key 88
- St. Petersburg 4
- Tierra Verde 4
- Vacation & Second Homes 959
- Venice 22
- Wellen Park 7
Recent Posts