Mortgage Prequalification vs. Preapproval: What's the Difference?
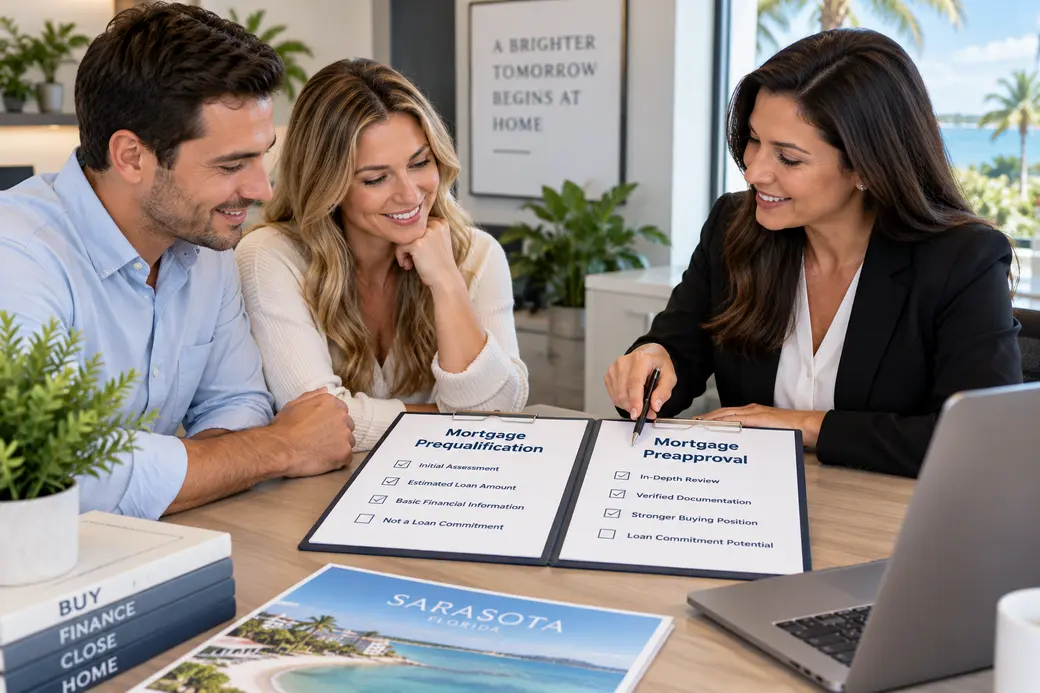
Mortgage prequalification and preapproval can both help home buyers understand potential financing before making an offer, but the terms do not have one universal meaning across lenders. Some lenders use prequalification for an initial estimate based largely on information provided by the buyer, while preapproval may involve a more detailed review of credit, income, assets and other documentation. The Consumer Financial Protection Bureau cautions that lenders use these terms differently, so the most important question is not what the letter is called, but what the lender actually reviewed and verified before issuing it.
Quick Answers About Mortgage Prequalification vs. Preapproval
What is mortgage prequalification?
Mortgage prequalification is generally an early assessment of how much a prospective borrower may be able to finance. Depending on the lender, it may rely substantially on information supplied by the buyer and may involve less verification than that lender's preapproval process.
What is mortgage preapproval?
A mortgage preapproval generally indicates that a lender is tentatively willing to lend up to a specified amount based on certain assumptions and the financial information it reviewed. Depending on the lender's process, that review may include credit, income, assets, debts and supporting documentation.
Is preapproval stronger than prequalification?
It often involves more verification, but buyers should not assume that based solely on the terminology. The CFPB specifically notes that lenders use "prequalification" and "preapproval" differently. Ask what information was verified, whether credit was reviewed and what conditions remain.
Does a preapproval guarantee the mortgage?
No. A preapproval is not a guaranteed loan offer or final mortgage approval. Additional borrower verification and property-related underwriting may still be required before the loan can close.
Do you need preapproval before looking at houses?
You can browse listings and attend open houses without being preapproved. For a financed buyer preparing to shop seriously and potentially make an offer, however, obtaining current financing information beforehand can help establish a realistic search range and provide a letter when a seller requests one.
Does getting preapproved mean you have chosen your mortgage lender?
No. The CFPB states that getting a preapproval does not commit you to using that lender. Buyers can compare lenders and, once they are pursuing a specific property and mortgage, compare official Loan Estimates.
Should you spend the full amount for which you are preapproved?
Not automatically. The maximum amount a lender may be willing to finance and the amount a buyer is personally comfortable spending are different questions. Your budget may also need to account for taxes, insurance, association fees, maintenance, repairs and other ownership expenses.
What Is Mortgage Prequalification?
Prequalification is generally an early step that gives a prospective home buyer an indication of the financing that may be available. Fannie Mae describes prequalification as a process that can provide a general idea of the loan amount a buyer is likely to qualify for.
With some lenders, prequalification may be relatively quick. The buyer might provide information about income, assets and debts verbally or through an online form. Supporting documentation may be limited at this stage, depending on the lender's process.
That can make prequalification useful for an early financing conversation. It can help someone who is beginning to consider homeownership understand a possible price range and identify questions to discuss with a mortgage professional.
The limitation is equally important: an estimate based primarily on information supplied by the borrower can change once the lender receives and verifies the supporting financial information.
What Is Mortgage Preapproval?
The Consumer Financial Protection Bureau describes a preapproval letter as a statement that a lender is tentatively willing to lend money to a buyer up to a certain loan amount.
A lender's preapproval process may involve a more detailed review of the buyer's financial position. Depending on the lender, borrower and loan program, the process may examine information involving:
- Income
- Employment
- Assets
- Existing debts
- Credit history
- Expected down payment
- Potential loan amount
Supporting documents may also be requested. The exact documentation depends on the lender, loan program and borrower's circumstances, so buyers should obtain a borrower-specific document list directly from their mortgage professional.
For a deeper look at timing, Hunt Brothers Realty explains why mortgage preapproval can be useful before seriously looking at houses.
The Most Important Difference Is What the Lender Actually Verified
It is tempting to create a simple rule that says prequalification is always an informal estimate and preapproval is always a fully verified decision. In practice, that can be misleading.
The CFPB's guidance on prequalification and preapproval states that lenders use the terms differently. Some lenders may use prequalification for a letter based on unverified borrower information and preapproval for a process based on verified information. Other lenders may use different terminology or procedures.
Instead of focusing exclusively on the heading printed on the letter, ask the lender exactly what occurred before it was issued.
Questions to Ask About a Prequalification or Preapproval Letter
- Was my income verified?
- Were my assets verified?
- Was my employment reviewed?
- Was my credit checked?
- Were my existing debts reviewed?
- Which loan program and down payment assumptions were used?
- What interest-rate assumption was used?
- What documentation has not yet been reviewed?
- What conditions remain?
- How long is the letter valid?
- What changes could affect the amount?
Those answers tell you much more about the strength and limitations of the lender's review than the words "prequalified" or "preapproved" alone.
Prequalification vs. Preapproval at a Glance
| Question | Prequalification | Preapproval |
|---|---|---|
| Typical purpose | Early financing estimate | More detailed financing preparation before serious shopping or making an offer |
| Financial information | May rely substantially on buyer-provided information | May involve greater documentation and verification |
| Credit review | Depends on lender | Often reviewed, but process varies by lender |
| Guarantees final financing? | No | No |
| Terminology standardized? | No | No |
This comparison describes common practices, not universal lender requirements. Always ask the lender what its specific process includes.
Why Can Preapproval Matter When You Make an Offer?
A seller evaluating a financed offer generally wants confidence that the buyer has taken meaningful steps toward arranging the financing needed to complete the purchase.
The CFPB explains that a preapproval letter can tell a seller that a buyer is likely to be able to obtain financing. Sellers may also request a preapproval letter when evaluating an offer.
A preapproval letter does not make an offer automatically stronger than every competing offer. Sellers may consider price, financing terms, deposits, contingencies, closing date and other contract terms. It does, however, provide financing information that may be important when a seller evaluates a financed purchase.
Does Preapproval Mean the Loan Is Approved?
No. Mortgage preapproval occurs before final loan approval, and often before the buyer has selected a particular property.
Once a buyer enters into a purchase contract, the lender may need to verify updated borrower information and evaluate the property under the applicable loan program and underwriting requirements. Depending on the transaction, property-related review can involve an appraisal, title, insurance, condominium project information and other requirements.
A buyer can therefore be preapproved and still encounter financing issues later. Mortgage qualification is an ongoing process until the lender has completed its required underwriting and the loan is cleared to close.
Can Your Preapproval Amount Change?
Yes. A preapproval reflects information and assumptions available at a particular point in time. Changes before closing can require additional lender review and may affect financing.
Depending on the circumstances, relevant changes can include:
- Employment or income changes
- Taking on new debt
- Changes to available assets
- Changes to credit
- A different down payment
- A different loan program
- Interest-rate changes
- The purchase price
- Property-specific underwriting requirements
Before making significant financial changes while buying a home, ask your mortgage professional whether the change could affect qualification or closing. Financing consequences depend on the individual borrower and loan.
Does Mortgage Preapproval Affect Your Credit?
A lender may check your credit when evaluating mortgage preapproval. The CFPB's credit-check guidance explains that lenders commonly obtain credit when someone applies for a new loan or seeks mortgage preapproval.
Do not assume every lender handles a prequalification or preapproval credit inquiry identically. Ask whether the lender will check your credit, what type of inquiry will be used and at what point in the process it occurs.
How Long Does a Mortgage Preapproval Last?
Preapproval letters are not necessarily valid indefinitely. The CFPB notes that a preapproval letter can have an expiration date and says a typical period may be 30 to 60 days, although the actual period depends on the lender.
If your home search takes longer, the lender may need updated information before issuing a current letter. Hunt Brothers Realty's guide to how long mortgage preapproval lasts explains what buyers should investigate when a letter is approaching expiration.
Does Preapproval Tell You How Much House You Can Afford?
It tells you something different. Preapproval can indicate the financing a lender may be willing to consider. Your personal budget determines how much you are comfortable spending.
The CFPB specifically cautions that only the buyer can determine how much is comfortable to spend. A lender evaluates creditworthiness and financing criteria, but your household budget may include priorities and expenses that are not fully reflected in the maximum loan amount.
This distinction can be particularly important for Florida buyers. In addition to principal and interest, ownership expenses may include property taxes, homeowners insurance, flood insurance when applicable, mortgage insurance, HOA or condominium assessments, utilities, maintenance and repairs.
Hunt Brothers Realty's guide to how much house you can afford in Florida in 2026 explains why a lender's maximum financing amount and a buyer's comfortable housing budget should be treated as separate questions.
What Documents Might You Need for Preapproval?
Documentation varies by lender, loan program and borrower. A salaried employee with straightforward income may have different requirements from a self-employed buyer, investor or borrower with variable income.
Depending on your circumstances, a lender may request information involving:
- Identity
- Employment
- Income documentation
- Bank and investment assets
- Existing debts
- Credit information
- Tax information when applicable
- Sources of down payment or closing funds
- Other documentation relevant to the borrower or loan program
Ask the lender for a personalized document checklist rather than assuming a generic online list contains everything needed for your application.
When Should You Get Prequalified?
A preliminary financing conversation can be useful when you are still exploring whether buying is realistic and want a general understanding of potential borrowing options.
For example, someone planning to buy later may want to understand whether income, debt, credit, down payment or available cash could affect future financing. Starting early can provide time to gather documentation and investigate questions before a purchase creates contractual deadlines.
When Should You Get Preapproved?
A practical time to obtain preapproval is when you are moving from casual research into serious home shopping and would be prepared to make an offer if the right property appears.
At that stage, current financing information can help you focus your search, understand estimated cash requirements and have a lender letter available when an offer requires one.
Getting preapproved earlier can also reveal documentation or qualification issues while there is time to investigate them. The CFPB specifically identifies this as one potential advantage of starting the process before finding a property.
Should You Compare More Than One Mortgage Lender?
Yes, comparing lenders can help buyers understand differences in loan programs, rates, fees and other financing terms. The CFPB's mortgage-shopping guidance recommends seeking preapprovals from at least three lenders.
A preapproval letter itself does not provide all of the information needed to determine which lender ultimately offers the most suitable financing. Once you have a specific property and apply for a mortgage, official Loan Estimates provide standardized information for comparing expected interest rates, monthly payments, closing costs and other loan terms.
Hunt Brothers Realty's guide to comparing mortgage types for home buyers covers additional questions to discuss with lenders when evaluating financing options.
Is a Preapproval the Same as a Loan Estimate?
No. A preapproval letter is an early financing document indicating that the lender is tentatively willing to lend based on its review and assumptions. A Loan Estimate is a standardized mortgage disclosure issued after a buyer submits the information constituting an application for a particular mortgage.
According to the CFPB's Loan Estimate guidance, the Loan Estimate provides important details such as the estimated interest rate, monthly payment and total closing costs for the requested mortgage.
For more on the expenses that appear during a financed purchase, see Hunt Brothers Realty's guide to closing costs when buying a house.
Does Preapproval Lock Your Mortgage Rate?
Do not assume that receiving a preapproval letter means your mortgage interest rate is locked. Preapproval and rate locking are separate concepts, and lender practices, timing, fees and lock terms can vary.
Ask your mortgage professional what interest-rate assumption was used in the preapproval, whether any rate is actually locked, how long a lock would last and what conditions apply. Rate and loan-term questions should be confirmed directly with the lender for your specific financing scenario.
Mortgage Preapproval Checklist Before You Start House Hunting
Before relying on a preapproval letter for your home search, consider confirming:
- What financial information the lender reviewed
- What documentation was verified
- Whether credit was checked
- The loan program assumed
- The down payment assumed
- The maximum loan amount stated in the letter
- The interest-rate assumption used
- Estimated monthly housing costs at several purchase prices
- Estimated cash needed for down payment and closing
- The expiration date of the letter
- What conditions remain before final approval
- What financial changes should be discussed with the lender before closing
The Bottom Line on Prequalification vs. Preapproval
Mortgage prequalification and preapproval both help buyers investigate financing before purchasing a home, but the labels alone do not tell you how thoroughly a lender reviewed the borrower.
Prequalification may provide an early estimate based on relatively limited information. Preapproval often involves greater documentation and verification and can provide a useful lender letter when a buyer begins serious home shopping. However, because lender practices differ, buyers should ask exactly what information was reviewed and what conditions remain.
Most importantly, neither one is final mortgage approval. A financed purchase still depends on the borrower's continued qualification, applicable underwriting requirements and the lender's review of the specific property.
Preparing to Buy a Home in Florida?
If you are preparing to buy a home in Sarasota or along Florida's Gulf Coast, Hunt Brothers Realty can help you organize the real estate side of the process, from defining your property search and evaluating listings to preparing an offer and completing property-specific due diligence. Buyers can also explore Sarasota-area communities before beginning a serious home search.
This article provides general real estate and educational information only and is not individualized financial, lending, legal, tax, insurance or other professional advice. Mortgage eligibility, prequalification and preapproval procedures, credit inquiries, interest rates, loan programs, down-payment requirements, closing costs and underwriting depend on the individual borrower, lender and transaction. Buyers should confirm all financing information and decisions with a qualified mortgage lender or loan professional. Legal, tax, insurance and other property-specific questions should be reviewed with the appropriate qualified professionals before making a purchasing decision.
Sources
- Consumer Financial Protection Bureau, What's the Difference Between a Prequalification Letter and a Preapproval Letter?
- Consumer Financial Protection Bureau, Get a Preapproval Letter
- Consumer Financial Protection Bureau, Shopping for a Mortgage
- Consumer Financial Protection Bureau, What Is a Loan Estimate?
- Fannie Mae, Pre-qualification vs. Pre-approval
- Hunt Brothers Realty, Should I Get Preapproved Before Looking at Houses?
- Hunt Brothers Realty, How Long Does a Mortgage Preapproval Last?
- Hunt Brothers Realty, How Much House Can You Afford in Florida in 2026?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1506
- Anna Maria Island 68
- Bird Key 3
- Bradenton 92
- Buying a Home 651
- Casey Key 2
- Clearwater 5
- Condos & HOA Living 556
- Ellenton 4
- Englewood 5
- First Time Homebuyers 728
- Foreclosures 3
- Homeownership 709
- Lakewood Ranch 15
- Lido Key 24
- Longboat Key 65
- Luxury/Waterfront Properties 646
- Market Updates & Trends 317
- Mortgages & Financing 32
- Move-Up Buyers 20
- Neighborhood Guides 470
- New Construction 24
- Palmetto 2
- Parrish 4
- Port Charlotte 7
- Punta Gorda 11
- Real Estate Investing 580
- Relocation to Florida 630
- Safety Harbor 2
- Sarasota - Downtown 132
- Selling a Home 136
- Siesta Key 87
- St. Petersburg 3
- Tierra Verde 4
- Vacation & Second Homes 763
- Venice 21
- Wellen Park 7
Recent Posts