How Much Are Closing Costs for Home Sellers in Florida in 2026?
There is no single percentage that every Florida home seller pays in closing costs in 2026. A seller's actual expenses can include Florida documentary stamp tax on the deed, title and closing expenses depending on the purchase contract, negotiated real estate brokerage compensation, association or estoppel-related charges when applicable, buyer concessions, mortgage-related payoff charges and other property-specific items. Sellers should also distinguish true transaction costs from paying off an existing mortgage, which can substantially reduce net proceeds but is repayment of debt rather than simply another closing fee. The best way to estimate the bottom line is with a property-specific seller net sheet.
That distinction matters. A Florida home can sell for $600,000 without the seller receiving anything close to $600,000 at closing. The sale price must be adjusted for transaction expenses, negotiated credits, prorations, mortgage and lien payoffs, and other obligations before the seller's estimated net proceeds become clear.
Quick Answers About Florida Home Seller Closing Costs in 2026
What closing costs does a Florida home seller typically need to consider?
Common possibilities include documentary stamp tax on the deed, brokerage compensation, title and closing expenses allocated to the seller under the contract, lien or association-related charges, negotiated buyer credits, prorated expenses and costs associated with satisfying existing mortgages or liens.
What percentage should a Florida seller budget for closing costs?
There is no reliable universal percentage because some of the largest expenses are negotiable or transaction-specific. Sellers should calculate known costs individually and request a seller net sheet rather than relying on a generic percentage.
How much is Florida documentary stamp tax on a deed?
In Florida counties other than Miami-Dade, the current rate is $0.70 for each $100, or portion thereof, of consideration. That equals $4,200 on a straightforward $600,000 consideration amount. Miami-Dade has a different rate and surtax structure.
Does the seller always pay the owner's title insurance policy in Florida?
No. Florida purchase contracts can allocate owner's title insurance and related charges differently. Sellers should check the title provision selected in their actual contract rather than relying on a statewide assumption.
Is real estate commission fixed in Florida?
No. Real estate brokerage compensation is negotiable and should be reviewed in the seller's listing agreement and any other applicable agreements. Sellers should not assume a particular commission percentage is required by law or standard for every transaction.
Is paying off the seller's mortgage considered a closing cost?
It is more useful to treat the mortgage payoff separately. The payoff can be one of the largest deductions from sale proceeds, but it represents repayment of the seller's existing debt rather than a transaction fee for selling the property.
Can a Florida seller pay some of the buyer's closing costs?
Potentially. A seller contribution toward eligible buyer expenses can be negotiated as part of an offer. The buyer's financing can limit what contributions are permitted, so proposed concessions should be verified before the parties rely on them.
How can a seller estimate what will actually be left after closing?
Ask for a seller net sheet using the expected sale price, estimated brokerage compensation, deed tax, title and closing expenses, mortgage payoff, concessions, prorations and other known obligations. Update it whenever the price or contract terms change.
What Are Seller Closing Costs in Florida?
Seller closing costs are expenses and adjustments associated with transferring the property and completing the transaction. They are deducted from the seller's side of the closing statement before the seller receives the remaining proceeds.
Depending on the property and contract, a Florida seller may need to account for:
- Florida documentary stamp tax on the deed
- Negotiated real estate brokerage compensation
- Owner's title insurance and title-related charges when allocated to the seller
- Seller closing or settlement charges when applicable
- Municipal lien, tax or other searches when allocated to the seller
- Association estoppel and related charges when applicable
- Recording or satisfaction-related expenses when applicable
- Negotiated buyer closing-cost contributions
- Inspection-related repairs or credits negotiated under the contract
- Property-tax, association, rent or other applicable prorations and adjustments
- Attorney or other professional fees when applicable
- Other property-specific or contract-specific expenses
Not every seller will pay every item on this list. The signed contract, property type, location, association status and negotiated terms determine much of the final allocation.
Why Is There No Single Florida Seller Closing-Cost Percentage?
Online estimates sometimes tell Florida sellers to subtract one fixed percentage from the sale price. That can be convenient for rough planning, but it can also create a misleading expectation.
Consider two sellers who each close at $600,000. One may have negotiated different brokerage compensation, pay the owner's title policy under the selected contract provision, provide no buyer credit and have no association. The other might have a different title arrangement, a condominium estoppel, a negotiated buyer concession and inspection-related credit.
Their sale prices are identical, but their seller costs can be substantially different.
For planning purposes, calculate each known expense individually. That produces a more useful estimate than applying a generic percentage to every Florida sale.
How Much Is Florida Documentary Stamp Tax When Selling a Home?
One of the most predictable expenses in many Florida home sales is documentary stamp tax on the deed.
The Florida Department of Revenue states that deeds and other documents transferring an interest in Florida real property are subject to documentary stamp tax. In every Florida county except Miami-Dade, the current rate is $0.70 per $100, or portion thereof, of consideration.
| Illustrative Consideration | Deed Documentary Stamp Tax at $0.70 per $100 |
|---|---|
| $300,000 | $2,100 |
| $400,000 | $2,800 |
| $500,000 | $3,500 |
| $600,000 | $4,200 |
| $750,000 | $5,250 |
| $1,000,000 | $7,000 |
These examples assume a straightforward consideration amount equal to the figure shown and a property outside Miami-Dade County. Documentary stamp tax can involve legal and tax questions concerning what constitutes taxable consideration. Sellers should use the calculation supplied by the closing professional and obtain qualified tax or legal guidance when their transfer is not a straightforward conventional sale.
Is Miami-Dade Different for Documentary Stamp Tax?
Yes. Miami-Dade County should not be calculated using the same formula without considering its separate rules.
The Florida Department of Revenue currently lists a Miami-Dade deed tax rate of $0.60 per $100, or portion thereof, of consideration, plus a $0.45 per $100 surtax. The Department states that the surtax does not apply to a document transferring only a single-family dwelling.
Because property type and transfer structure matter, Miami-Dade sellers should have the actual deed tax calculated for their transaction rather than using a statewide online estimate.
Did Florida Change the General Deed Tax Rate in 2026?
The Florida Department of Revenue published a documentary stamp tax legislative update in July 2026, but the current Department guidance continues to list the general deed tax rate outside Miami-Dade at $0.70 per $100 or portion thereof of consideration.
Sellers preparing a future closing should still verify the current calculation because tax law can change and unusual transfers can require transaction-specific analysis.
Does the Seller Pay Real Estate Commission in Florida?
A seller may owe brokerage compensation under a listing agreement, but there is no universal Florida commission percentage that every seller is required to pay.
Real estate brokerage compensation is negotiable. Sellers should review the compensation terms of their listing agreement rather than automatically adding a fixed percentage from an online calculator.
Seller decisions concerning whether to offer or agree to additional compensation associated with a buyer's brokerage representation are also transaction-specific. A seller should understand exactly what has been agreed to, who is being compensated, the amount, and how it affects estimated net proceeds.
When preparing to list, ask your real estate professional to show brokerage compensation as a separate line on the estimated seller net sheet. This makes it easier to see the effect of the negotiated agreement without treating any commission percentage as fixed by law.
Who Pays for Owner's Title Insurance in Florida?
There is not one answer that applies to every Florida residential transaction.
The Florida Realtors/Florida Bar residential contract includes different title arrangements. Under one option, the seller designates the closing agent and pays the owner's policy and specified related charges. Under another, the buyer designates the closing agent and pays those costs. A separate regional provision applies to Miami-Dade and Broward transactions.
This is an important example of why "Florida sellers always pay title insurance" is too broad.
Seller takeaway: look at the title provision selected in the actual purchase contract. That provision can materially change the seller's closing-cost estimate.
What Other Title and Closing Charges Can a Seller Pay?
Depending on the contract option and transaction, seller-side expenses can involve title searches, municipal lien searches, tax searches, closing services or other title-related work.
A seller may also have expenses connected with clearing title issues or satisfying existing liens before the buyer can receive the title required by the contract.
These amounts should come from the title or closing professional handling the actual sale. Questions about ownership, liens, title defects or the seller's legal obligations should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional when individualized legal guidance is necessary.
How Does a Mortgage Payoff Affect Seller Proceeds?
A mortgage payoff is one of the most important numbers on a seller's closing statement, but it should not be confused with the cost of selling the home.
Suppose a seller closes at $600,000 and owes approximately $250,000 on the existing mortgage. That $250,000 does not represent a $250,000 selling fee. It represents debt secured by the property that generally must be satisfied as part of transferring title.
The actual payoff can differ from the principal balance displayed on a monthly mortgage statement because a payoff calculation can include interest through the payoff date and other amounts applicable to the loan.
Use an official payoff statement obtained through the appropriate closing process rather than estimating the seller's net from the current principal balance alone.
What About a Home Equity Loan or HELOC?
Additional loans or liens secured by the property can also reduce the amount a seller receives at closing.
A seller with a first mortgage and a home equity line should not calculate expected proceeds using only the first mortgage. The closing and title professionals need to identify the obligations that must be satisfied or otherwise addressed for the transaction.
If there are judgments, disputed liens, ownership issues or questions about which obligations must be paid, obtain appropriate legal and title guidance rather than relying on a preliminary net estimate.
How Do Property Taxes Affect a Florida Seller's Closing Statement?
Property taxes can create a seller-side adjustment at closing even though they are not simply another service fee.
The Florida Realtors/Florida Bar residential contract provides for applicable items to be made current and prorated according to the contract. The exact treatment depends on the closing date, tax status, contract and available tax information.
Because Florida property taxes are property-specific and homestead or other circumstances can affect taxation, sellers should use the closing professional's actual calculation. Questions about the tax consequences of a sale or a seller's individual tax liability should be directed to a qualified tax professional or CPA.
Can Condo and HOA Sellers Have Additional Closing Expenses?
Yes. Selling property within a condominium or homeowners association can introduce additional charges and adjustments that do not apply to an unassociated single-family property.
Depending on the community and transaction, potential issues can involve:
- Estoppel-related charges
- Outstanding assessments
- Regular association assessments and prorations
- Transfer-related charges
- Application or approval matters
- Other association-specific obligations
The allocation and amount can depend on current law, association documents and the purchase contract. Sellers should request current information from the association or management company and verify how each item will appear on the closing statement.
Can a Seller Pay the Buyer's Closing Costs?
A buyer may ask a Florida seller to contribute toward eligible buyer closing costs. If the seller agrees and the transaction permits the contribution, that concession reduces the seller's net proceeds.
For example, compare these hypothetical offers:
- Offer A: $500,000 with no seller closing-cost contribution
- Offer B: $505,000 with a $10,000 seller contribution toward eligible buyer expenses
Offer B has the higher headline price, but the $10,000 concession changes its economics for the seller. Other terms can change the comparison further.
This is why sellers should compare estimated net proceeds and overall contract terms, not just purchase price. Hunt Brothers Realty's Sarasota and Manatee negotiation guide explains how closing-cost contributions, repairs, credits and timing can all become part of an offer.
For financed purchases, the buyer should confirm that a proposed seller contribution complies with the applicable loan requirements. Sellers should not assume that any requested credit can automatically be used in full.
Can Inspection Findings Increase a Seller's Cost?
Potentially. Inspection findings can affect the economics of a sale even when they are not part of the seller's original closing-cost estimate.
Depending on the contract and negotiations, an inspection issue could lead to:
- Seller-completed repairs
- A negotiated repair credit
- A price adjustment
- Another negotiated concession
- No change to the transaction
The result depends on the contract, the condition identified, the parties' negotiations and other transaction circumstances. Inspection findings should be evaluated by the appropriate inspector, contractor, engineer or other qualified professional before a seller makes a significant repair decision.
What About Repairs and Improvements Before the Home Is Listed?
Pre-listing expenses are another reason the total cost of selling can be higher than the closing statement alone suggests.
A seller might spend money before listing on:
- Cleaning
- Decluttering or moving belongings
- Landscaping
- Painting
- Minor repairs
- Roof, HVAC, plumbing or electrical work when needed
- Staging or presentation
- Moving and storage
These are not necessarily closing costs, but they affect the seller's total financial outcome. Before beginning a major project solely for resale, review Hunt Brothers Realty's guide to renovating before selling a Florida home. An expensive renovation does not automatically produce an equivalent increase in sale price.
What Is a Seller Net Sheet?
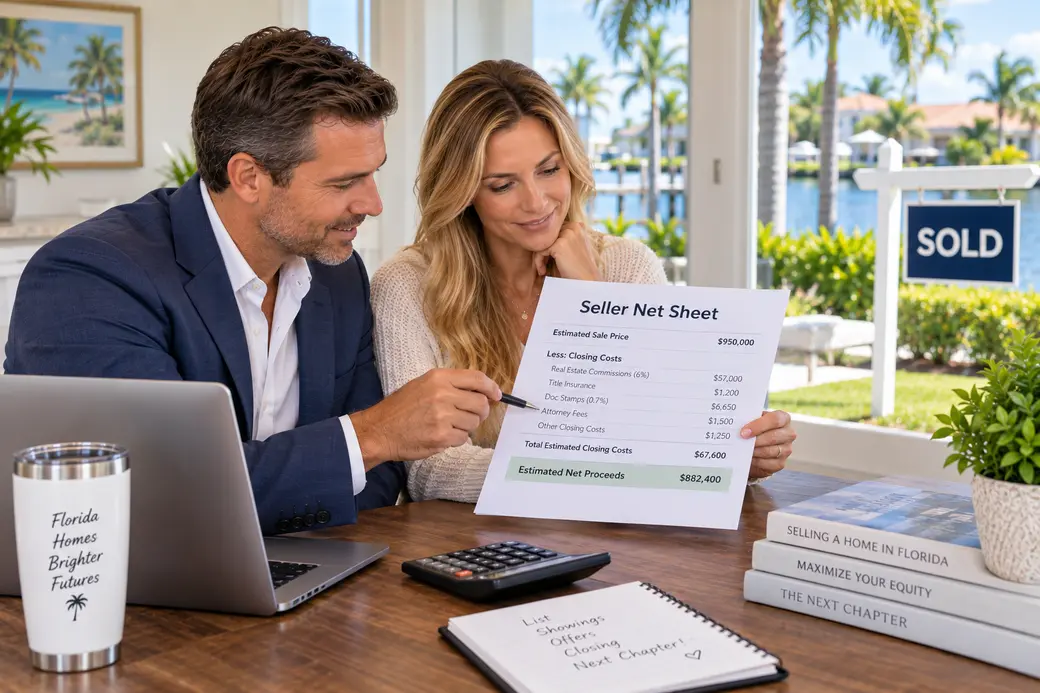
A seller net sheet is an estimate showing how the anticipated sale price may translate into proceeds after expected deductions and adjustments.
A useful seller net estimate may include:
- Expected sale price
- Negotiated brokerage compensation
- Documentary stamp tax on the deed
- Estimated title and closing charges
- Association-related expenses when applicable
- Estimated tax and other prorations
- Negotiated buyer concessions
- Mortgage, HELOC and other lien payoffs
- Other transaction-specific deductions or credits
A preliminary net sheet is an estimate, not the final closing statement. Its usefulness comes from helping sellers compare scenarios before making decisions.
Example: Estimating Net Proceeds on a $600,000 Florida Sale
Consider a hypothetical property outside Miami-Dade County selling for $600,000. Rather than applying a blanket closing-cost percentage, build the estimate line by line.
| Item | Illustrative Treatment |
|---|---|
| Sale price | $600,000 |
| Deed documentary stamp tax | Approximately $4,200 under the current general rate |
| Brokerage compensation | Use the amount negotiated in the applicable agreement |
| Title and closing expenses | Use the actual contract allocation and closing estimate |
| Association charges | Add if applicable to the property and seller |
| Buyer concession | Add the negotiated amount, if any |
| Taxes and other prorations | Use the transaction-specific estimate |
| Mortgage and other lien payoff | Use current official payoff figures |
This approach intentionally does not invent a commission, title premium, mortgage balance or seller concession. Those are exactly the variables that can make one seller's net proceeds very different from another seller's proceeds at the same $600,000 sale price.
Sale Price and Seller Net Proceeds Are Not the Same Number
This becomes especially important when sellers are deciding how much they need from a sale to fund their next purchase, retirement plans or another financial goal.
A simplified framework is:
Sale price minus seller transaction expenses, negotiated credits, prorations and debt or lien payoffs equals estimated net proceeds.
That is why pricing a home solely according to the amount a seller wants to receive can create problems. Buyers compare the property with competing listings and recent sales, not with the seller's mortgage balance or desired net.
Hunt Brothers Realty's guide to common Sarasota seller mistakes explains why pricing based primarily on what an owner wants to net can disconnect the asking price from current market evidence.
Can Selling Costs Affect Which Offer Is Actually Better?
Absolutely. The highest purchase price is not automatically the offer with the highest estimated seller proceeds or the terms that best fit the seller's priorities.
When comparing offers, sellers may need to consider:
- Purchase price
- Requested seller closing-cost contributions
- Any negotiated buyer-broker compensation
- Financing terms
- Inspection provisions
- Closing date
- Requested personal property
- Other concessions or negotiated expenses
A useful practice is to update the seller net estimate for each serious offer. That converts competing contract terms into a clearer financial comparison while still allowing the seller to consider timing, certainty and other non-price priorities.
How Can Florida Sellers Reduce Surprises at Closing?
- Request a preliminary seller net sheet before listing. Start with a realistic expected sale price and known obligations.
- Verify mortgage and lien information. Do not estimate equity from the first mortgage balance alone if other secured obligations exist.
- Understand brokerage compensation. Use the negotiated terms of the applicable agreement rather than an assumed industry percentage.
- Review the title provision in the offer. Know which party is paying the owner's policy and related expenses before accepting the contract.
- Identify association costs early. Condo and HOA transactions may have additional documentation, estoppel, assessment or transfer considerations.
- Model requested concessions. Calculate how a buyer closing-cost credit or other concession changes the seller's estimated proceeds.
- Budget for property condition. Consider likely pre-listing work and the possibility of inspection-related negotiations.
- Update the net sheet after accepting an offer. Replace preliminary assumptions with actual contract terms.
- Review the final closing statement. Ask the closing professional about charges or credits you do not understand before closing.
Should You Renovate Just to Increase Your Net Proceeds?
Not automatically. A seller can spend $30,000 preparing a property and still fail to increase the sale price by $30,000.
Before making a major improvement for resale, compare the property with the homes buyers are actually considering. Condition, functionality and presentation can matter, but the market may not reward every renovation equally.
Hunt Brothers Realty recommends evaluating renovations according to the home's condition, neighborhood, competing inventory, likely buyer, cost and expected market response rather than assuming every update will generate a positive return.
Contractors should provide property-specific estimates for contemplated work. Sellers with tax questions about improvement costs or the tax treatment of a sale should consult a qualified tax professional.
When Should a Florida Seller Calculate Closing Costs?
Ideally, before the property is listed.
Early planning allows a seller to understand the relationship between likely market value, expected expenses, mortgage payoff and potential net proceeds before making decisions based on an unrealistic number.
It is also useful to update the estimate at several stages:
- Before choosing the listing price
- When evaluating an offer
- After negotiating concessions
- After inspection negotiations
- When updated payoff information becomes available
- Before the final closing
Sellers who are still deciding when to enter the market can also review Hunt Brothers Realty's 2026 guide to the best time to sell a home in Sarasota. Timing, pricing, competition and preparation should be considered together rather than separately.
What Should Florida Sellers Ask Before Listing?
- What is a realistic market range for my property?
- What brokerage compensation am I agreeing to?
- What deed documentary stamp tax would apply at several possible sale prices?
- What title arrangement is common in my transaction, and what does the eventual contract actually require?
- What mortgage, HELOC or lien balances may need to be satisfied?
- Does my condo or HOA create additional seller expenses?
- What repairs or preparation make sense before listing?
- How would a buyer concession affect my net?
- What is my estimated net at several realistic sale prices?
Focus on Net Proceeds, Not Just the Sale Price
For Florida sellers in 2026, the most useful question is not simply, "What percentage will I pay in closing costs?"
A better question is, "Based on my property, contract, debts and negotiated terms, what am I estimated to receive after closing?"
Florida's deed documentary stamp tax can be calculated once the taxable consideration is known. Other major expenses, including brokerage compensation, title allocation, concessions and association charges, can vary. Mortgage and lien payoffs then affect the amount remaining even though they are not simply selling fees.
Building the estimate line by line provides a clearer picture of the sale than relying on a blanket closing-cost percentage.
Planning to Sell a Florida Gulf Coast Home?
Hunt Brothers Realty helps Florida Gulf Coast homeowners evaluate pricing, current competition, property preparation, offer terms and estimated seller proceeds before making a selling decision. Sellers can also review common Sarasota home-selling mistakes to avoid, consider whether to renovate before selling a Florida home, learn about the best time to sell a home in Sarasota, or explore Sarasota-area and Florida Gulf Coast communities.
Informational notice: This article provides general real estate and educational information and is not individualized legal, financial, tax, title or other professional advice. Seller closing costs, title expenses, documentary stamp taxes, association obligations, brokerage compensation, mortgage payoffs, prorations, credits and net proceeds vary by property and transaction. Sellers should verify closing figures with their real estate and title or closing professionals, obtain official payoff information from applicable lenders, consult a qualified tax professional or CPA regarding individual tax consequences, and seek advice from a qualified Florida real estate attorney when questions involve title, ownership, liens, contract rights or other individualized legal matters.
Sources
- Florida Department of Revenue, Documentary Stamp Tax
- Florida Department of Revenue, 2026 Tax Information Publications
- Florida Realtors/Florida Bar, Residential Contract for Sale and Purchase
- Florida Realtors, Florida Laws and Guidance on Real Estate Compensation
- Hunt Brothers Realty, Common Mistakes Sarasota Home Sellers Should Avoid in 2026
- Hunt Brothers Realty, Should You Renovate Before Selling Your Florida Home?
- Hunt Brothers Realty, Best Time to Sell a Home in Sarasota: 2026 Seller Guide
- Hunt Brothers Realty, August Negotiation Season in Sarasota and Manatee
Contact Hunt Brothers Realty
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3
Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1406
- Anna Maria Island 66
- Bird Key 3
- Bradenton 44
- Buying a Home 562
- Casey Key 2
- Clearwater 5
- Condos & HOA Living 472
- Ellenton 4
- Englewood 5
- First Time Homebuyers 634
- Foreclosures 3
- Homeownership 610
- Lakewood Ranch 15
- Lido Key 24
- Longboat Key 65
- Luxury/Waterfront Properties 548
- Market Updates & Trends 276
- Mortgages & Financing 27
- Move-Up Buyers 20
- Neighborhood Guides 416
- New Construction 21
- Palmetto 2
- Parrish 4
- Port Charlotte 7
- Punta Gorda 11
- Real Estate Investing 481
- Relocation to Florida 532
- Safety Harbor 2
- Sarasota - Downtown 110
- Selling a Home 134
- Siesta Key 87
- St. Petersburg 3
- Tierra Verde 3
- Vacation & Second Homes 665
- Venice 20
- Wellen Park 7
Recent Posts