How Much Money Do I Need to Buy a House in Florida?
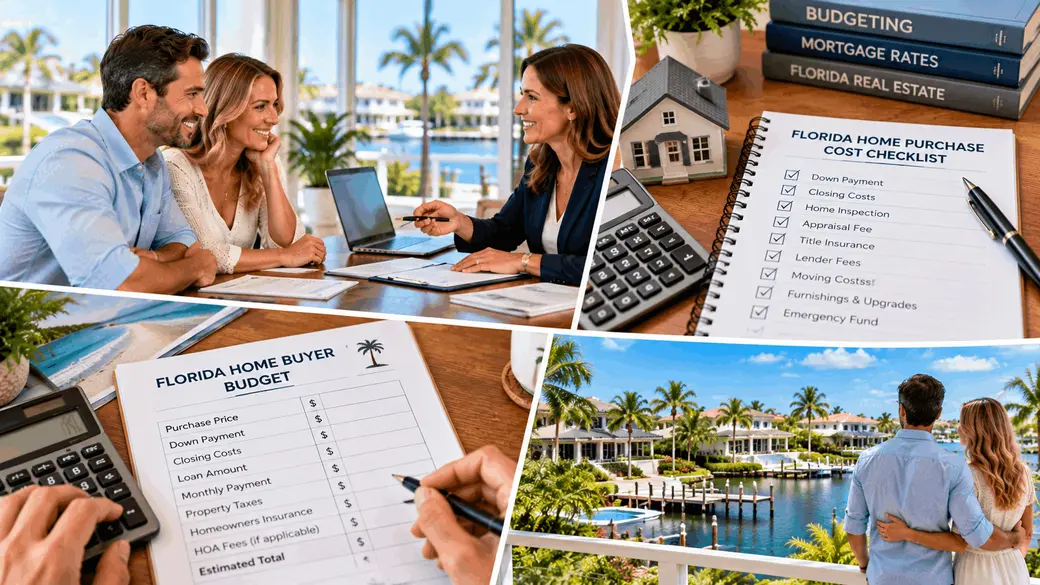
The money needed to buy a house in Florida is usually more than the down payment. Buyers should plan for four separate cash categories: the contract deposit, down payment, closing and transaction costs, and savings remaining after closing. Qualified buyers do not universally need 20% down. Some mortgage programs permit substantially smaller down payments, but closing costs alone can commonly be estimated at roughly 2% to 5% of the purchase price for early planning, excluding the down payment. Your actual cash requirement depends on the home, mortgage, insurance, contract, taxes, association expenses and other transaction-specific factors.
Quick Answers About How Much Money You Need to Buy a House in Florida
Do I Need 20% Down to Buy a House in Florida?
No. Qualified borrowers can have conventional mortgage options requiring as little as 3% down, FHA financing can permit 3.5% down for qualified borrowers, and certain eligible VA borrowers can have a no-down-payment option. Your actual minimum depends on the mortgage program, lender, borrower qualifications and property.
How Much Are Closing Costs When Buying a Florida Home?
For early budgeting, the Consumer Financial Protection Bureau uses approximately 2% to 5% of the purchase price as a typical closing-cost range, excluding the down payment. This is a broad planning estimate, not a Florida quote. Actual costs depend on financing, insurance, title and settlement arrangements, prepaid expenses, taxes, the contract and the property.
Is Earnest Money an Extra Cost?
An earnest money deposit is generally money delivered in connection with the purchase contract and held according to the agreement. If the transaction closes, the buyer's properly credited deposit is generally accounted for among funds already paid rather than simply becoming an additional closing fee. The amount, deadlines, refundability and disposition of a deposit depend on the contract.
How Much Cash Do I Need for a $400,000 Florida House?
There is no single amount. A 5% down payment would equal $20,000, while the broad 2% to 5% closing-cost planning range would represent another $8,000 to $20,000. That creates an illustrative $28,000 to $40,000 before accounting for deposits already paid, seller or lender credits, inspections, moving expenses, reserves and other transaction-specific adjustments.
Can the Seller Pay Some of My Closing Costs?
Potentially. A buyer can negotiate for a seller contribution toward eligible expenses, but the seller does not have to agree. Mortgage programs can also limit the amount and permitted use of seller concessions, so financed buyers should confirm the structure with their lender.
Should I Use All My Savings for the Down Payment?
Not automatically. Buyers also need to consider closing costs, inspections, moving, immediate property expenses and savings after closing. The Consumer Financial Protection Bureau uses three to six months of expenses as a general emergency-cushion starting point when calculating available purchase cash, although the appropriate reserve is different for every household.
When Will I Know the Actual Cash I Need at Closing?
Your lender and closing professional provide transaction-specific figures as the purchase progresses. For most covered mortgage transactions, the Closing Disclosure provides the final loan terms and calculated cash-to-close information before consummation. Review that document carefully rather than relying on an early percentage estimate.
The Four Cash Buckets Florida Buyers Should Plan For
The easiest way to understand how much money you need is to stop treating every upfront expense as the "down payment." There are four different cash categories to consider:
- Contract deposit: Money delivered according to the purchase agreement and held as provided by the contract.
- Down payment: The portion of the purchase price you pay rather than finance.
- Closing and transaction costs: Mortgage, settlement, insurance, prepaid, inspection and other applicable purchase expenses.
- Post-closing savings: Cash retained for moving, repairs, maintenance, emergencies and other needs after becoming the owner.
A buyer can have enough money for the down payment and still not have enough cash for a financially workable purchase if the other categories have not been considered.
How Much Down Payment Do You Need in Florida?
There is no universal Florida down-payment percentage. The requirement comes primarily from the financing structure rather than from a rule requiring every Florida buyer to put 20% down.
Depending on eligibility and lender requirements, current possibilities can include conventional mortgage options with down payments as low as 3%, FHA financing with 3.5% down for qualifying borrowers, and no-down-payment financing for certain eligible VA borrowers.
Minimum eligibility is not the same as the amount you should put down. A qualified mortgage lender should compare available programs, interest rates, mortgage insurance, monthly payments, closing cash and reserve requirements using your actual financial information.
What Do Different Down Payments Look Like in Dollars?
| Home Price | 3% Down | 5% Down | 10% Down | 20% Down |
|---|---|---|---|---|
| $300,000 | $9,000 | $15,000 | $30,000 | $60,000 |
| $400,000 | $12,000 | $20,000 | $40,000 | $80,000 |
| $500,000 | $15,000 | $25,000 | $50,000 | $100,000 |
| $750,000 | $22,500 | $37,500 | $75,000 | $150,000 |
These figures show the down payment only. They do not include closing costs, mortgage insurance, inspections, moving expenses or reserves, and a particular buyer may not qualify for every down-payment level shown.
For a deeper comparison, read How Much Should You Put Down on a House?
How Much Should You Budget for Florida Buyer Closing Costs?
Closing costs are separate from the down payment. They are a collection of expenses associated with completing the purchase and, when applicable, obtaining a mortgage.
For preliminary planning, the Consumer Financial Protection Bureau uses a typical closing-cost range of approximately 2% to 5% of the purchase price, excluding the down payment. Actual Florida transactions can fall outside that range.
| Purchase Price | 2% Illustration | 5% Illustration |
|---|---|---|
| $300,000 | $6,000 | $15,000 |
| $400,000 | $8,000 | $20,000 |
| $500,000 | $10,000 | $25,000 |
| $750,000 | $15,000 | $37,500 |
These are mathematical illustrations, not quotes or verified Florida averages. Your lender and closing professional should calculate the actual transaction-specific expenses.
What Can Florida Buyer Closing Costs Include?
- Mortgage origination and lender charges
- Optional mortgage discount points
- Appraisal and other loan services
- Title and settlement expenses
- Recording charges
- Applicable mortgage-related Florida taxes
- Prepaid mortgage interest
- Prepaid homeowners insurance
- Initial tax and insurance escrow deposits when applicable
- Association-related charges when applicable
- Other property, loan or contract-specific expenses
See Florida Buyer Closing Costs in 2026 for a detailed explanation of these categories.
What Is Earnest Money When Buying a Florida House?
An earnest money deposit is money delivered in connection with a purchase agreement and handled according to the contract. It is different from a closing-cost fee.
There is no universal deposit percentage that applies to every Florida residential purchase. The amount, timing and terms are part of the specific transaction and contract.
When a transaction closes, a properly credited deposit generally reduces the amount still due from the buyer because the money has already been delivered toward the transaction.
Deposit deadlines, refund rights, defaults and disputes are contractual and potentially legal matters. Buyers should carefully review the signed agreement and consult a qualified Florida real estate attorney when legal interpretation or advice is needed.
What Is the Difference Between Down Payment, Closing Costs and Cash to Close?
These terms are related but should not be used interchangeably.
Down payment: The portion of the purchase price the buyer pays rather than finances.
Closing costs: The expenses associated with completing the transaction and, when applicable, obtaining financing.
Cash to close: The final amount the buyer needs to provide at settlement after accounting for the down payment, closing expenses, deposits already paid, applicable credits and other adjustments.
A Simple Cash-to-Close Example
Consider a simplified hypothetical transaction:
- Purchase price: $400,000
- 5% down payment: $20,000
- Illustrative closing costs and prepaids: $12,000
- Deposit already paid and credited: $5,000
- Assumed eligible seller credit: $3,000
Under those assumptions, the simplified remaining cash calculation would be $20,000 + $12,000 - $5,000 - $3,000 = $24,000.
This is an educational example only. It is not a Florida closing quote and does not include every possible credit, adjustment or expense. The lender and closing professional should provide the actual cash-to-close calculation.
How Much Money Might You Need for a $300,000, $400,000 or $500,000 Florida Home?
The following table combines a hypothetical 5% down payment with the broad 2% to 5% closing-cost planning range. It is intended to show the scale of potential upfront cash, not predict an actual transaction.
| Home Price | 5% Down | 2% to 5% Closing-Cost Illustration | Combined Illustration Before Credits and Reserves |
|---|---|---|---|
| $300,000 | $15,000 | $6,000 to $15,000 | $21,000 to $30,000 |
| $400,000 | $20,000 | $8,000 to $20,000 | $28,000 to $40,000 |
| $500,000 | $25,000 | $10,000 to $25,000 | $35,000 to $50,000 |
| $750,000 | $37,500 | $15,000 to $37,500 | $52,500 to $75,000 |
These examples exclude separately paid inspections, moving expenses and post-closing savings. They also do not subtract earnest money already paid or any permitted seller or lender credits. Actual mortgage programs may require a different down payment.
Do You Need Money for Inspections Before Closing?
Potentially, and this is one reason the amount in your bank account should not equal only your estimated cash due on closing day.
Inspections are often paid during the transaction. Depending on the property and buyer's due diligence, evaluations may include:
- General home inspection
- Roof evaluation
- HVAC evaluation
- Plumbing or electrical evaluation
- Wood-destroying organism inspection
- Pool inspection
- Septic or well inspection
- Seawall or dock evaluation
- Structural or engineering evaluation when appropriate
Not every property needs every inspection listed. Buyers should discuss appropriate due diligence with qualified inspectors and use licensed contractors, engineers or other specialists when findings require additional expertise.
Why Can Homeowners Insurance Change the Money You Need?
Insurance can affect both the ongoing housing budget and the upfront cash required for a financed purchase. Depending on the transaction, buyers may need to pay a homeowners insurance premium in advance and may also fund an insurance escrow account.
Florida insurance costs should not be estimated solely from the purchase price. Availability, coverage and premiums can vary by property based on factors such as location, roof characteristics, construction, wind mitigation, selected coverage, deductibles and insurer underwriting.
Obtain a property-specific insurance quote and review the proposed coverage with a qualified insurance professional before making a purchasing decision that depends on the premium.
Do Florida Buyers Need to Budget for Flood Insurance?
Flood insurance can create an additional expense depending on the property, buyer's coverage decision and lender requirements.
The Florida Department of Financial Services explains that flood insurance is usually a separate policy from homeowners insurance, although some private homeowners insurers may offer flood coverage as an endorsement.
Buyers should investigate current official flood information and obtain property-specific insurance guidance rather than assuming a standard statewide flood-insurance cost.
What About HOA, Condo and Community Fees?
Association properties can introduce additional upfront and recurring expenses. Depending on the community and transaction, these may include application charges, transfer or administrative charges, prorated assessments, capital contributions, current assessments or other authorized obligations.
A buyer should also distinguish between money required at closing and the recurring HOA or condominium assessment that becomes part of the ownership budget.
Before purchasing an association property, verify current charges, approved assessments and applicable obligations from the association and transaction documents. Legal, accounting or association-finance questions should be directed to the appropriate qualified professional.
Should You Keep Savings After Buying the House?
Closing should not reduce your savings plan to zero simply because you technically have enough money to complete the purchase.
New homeowners can encounter expenses almost immediately. An air-conditioning system can need service, an appliance can fail, a repair identified during inspection can become more urgent, or moving costs can exceed the original estimate.
The Consumer Financial Protection Bureau suggests subtracting an emergency cushion, usually three to six months of expenses, when determining maximum available cash for a home purchase. It also recommends accounting separately for moving, renovations, furnishings and initial home expenses.
That range is general educational guidance, not an individualized savings recommendation. Your appropriate reserve depends on income stability, household obligations, property condition, insurance deductibles, anticipated repairs and broader financial circumstances. Review individualized savings decisions with an appropriate financial professional when needed.
For a more detailed discussion, see How Much Savings Should You Keep After Buying a House?
Could Putting Less Down Leave You in a Stronger Cash Position?
Potentially, but the tradeoff needs to be calculated rather than assumed.
A smaller down payment can preserve cash for closing expenses, repairs and reserves. At the same time, financing more can increase the mortgage balance and monthly principal and interest and may affect mortgage insurance, interest-rate pricing or qualification.
Ask a qualified lender to model several down-payment options so you can compare:
- Cash required at closing
- Mortgage amount
- Interest rate and loan pricing
- Monthly principal and interest
- Mortgage insurance when applicable
- Cash remaining after closing
Can a Seller Help Reduce the Cash You Need?
Potentially. Buyers can negotiate seller concessions toward allowable expenses, subject to the seller's agreement and applicable financing restrictions.
Depending on the transaction and loan, an eligible seller contribution might help with certain closing costs, prepaid expenses, mortgage discount points or other permitted items.
A concession is not unrestricted cash to the buyer, and loan programs can limit both the amount and permitted use. The purchase contract must also properly address the negotiated terms.
Learn more in Seller Concessions in Florida: What Can Homebuyers Ask For in 2026?
Could Down-Payment Assistance Reduce the Money You Need?
Some buyers may qualify for homebuyer or down-payment assistance programs. Availability, funding, income limits, purchase-price limits, occupancy requirements, first-time-buyer definitions, participating lender requirements and repayment provisions can vary by program.
Do not subtract potential assistance from your required savings until a qualified participating lender or program administrator confirms that you and the proposed transaction meet the current requirements.
How Much Money Should You Have Before You Start Looking at Florida Homes?
Before serious home shopping, you do not necessarily need the final closing figure because you do not yet have a specific property. You should, however, have a realistic preliminary cash plan.
That plan should answer:
- How much cash do I currently have available?
- How much do I want to preserve after closing?
- What down-payment options does my lender offer?
- What closing-cost range should I initially plan for?
- How much might I need for inspections and other pre-closing expenses?
- What moving or immediate repair expenses should I anticipate?
- Does the property type create additional insurance or association costs?
For the next step, read How Much House Can You Afford in Florida? and compare the upfront cash requirement with the total monthly ownership budget.
A Simple Florida Home-Buying Savings Formula
For preliminary planning, think about the money needed this way:
Target down payment + estimated closing and transaction expenses + moving and immediate property expenses + desired post-closing savings = preliminary savings target.
Deposits already paid and eligible credits can affect the amount ultimately needed at settlement, but they should be incorporated using the actual contract and financing terms rather than assumed in advance.
This approach is more useful than simply saving 20% of an estimated purchase price because it recognizes that a lower down-payment mortgage can still require meaningful cash for other expenses, while a buyer putting 20% down may want substantial savings remaining afterward.
What Is the Biggest Cash Mistake Florida Buyers Can Make?
One of the biggest planning mistakes is asking only, "Do I have enough for the down payment?"
A better question is, "Do I have enough to buy this particular home, complete the transaction and remain financially prepared after I own it?"
That means evaluating the down payment alongside closing costs, inspections, insurance, association obligations, property condition, moving expenses and post-closing reserves.
For a complete ownership-cost framework, review The True Cost of Buying a Home in Florida.
Plan the Real Estate Side of Your Florida Purchase With Hunt Brothers Realty
Hunt Brothers Realty helps Florida Gulf Coast buyers evaluate properties while accounting for the real estate factors that can affect purchase and ownership costs. Buyers can compare Florida Gulf Coast communities, understand Florida buyer closing costs, compare home down-payment options, and plan for savings after buying a house.
When you are ready to define your property search, contact Hunt Brothers Realty.
This article provides general real estate and educational information only. It is not individualized financial, lending, tax, insurance, legal, inspection, engineering, title or other professional advice. Down-payment requirements, mortgage qualification, closing costs, insurance, taxes, association expenses, contract deposits, cash-to-close requirements and appropriate financial reserves depend on the buyer, property, financing and transaction. Buyers should verify transaction-specific information and consult the appropriate qualified mortgage lender or loan professional, insurance agent, tax professional or CPA, licensed real estate professional, Florida real estate attorney, home inspector, engineer, title or closing professional, association and governmental authority before making decisions requiring individualized guidance.
Sources
- Consumer Financial Protection Bureau, Determine Your Down Payment
- Consumer Financial Protection Bureau, Figure Out How Much You Want to Spend
- Florida Department of Financial Services, Flood Insurance Consumer Information
- Hunt Brothers Realty, How Much Should You Put Down on a House?
- Hunt Brothers Realty, Florida Buyer Closing Costs in 2026
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
- Hunt Brothers Realty, How Much Savings Should You Keep After Buying a House?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2070
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1131
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1049
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1240
- Foreclosures 3
- Home Selling 3
- Homeownership 1263
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1204
- Market Updates & Trends 730
- Mortgages & Financing 42
- Move-Up Buyers 21
- Neighborhood Guides 842
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1121
- Relocation to Florida 1163
- Safety Harbor 2
- Sarasota 77
- Sarasota - Downtown 162
- Selling a Home 144
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1313
- Venice 169
- Wellen Park 16
Recent Posts