How Much Should I Save Before Buying a Home?
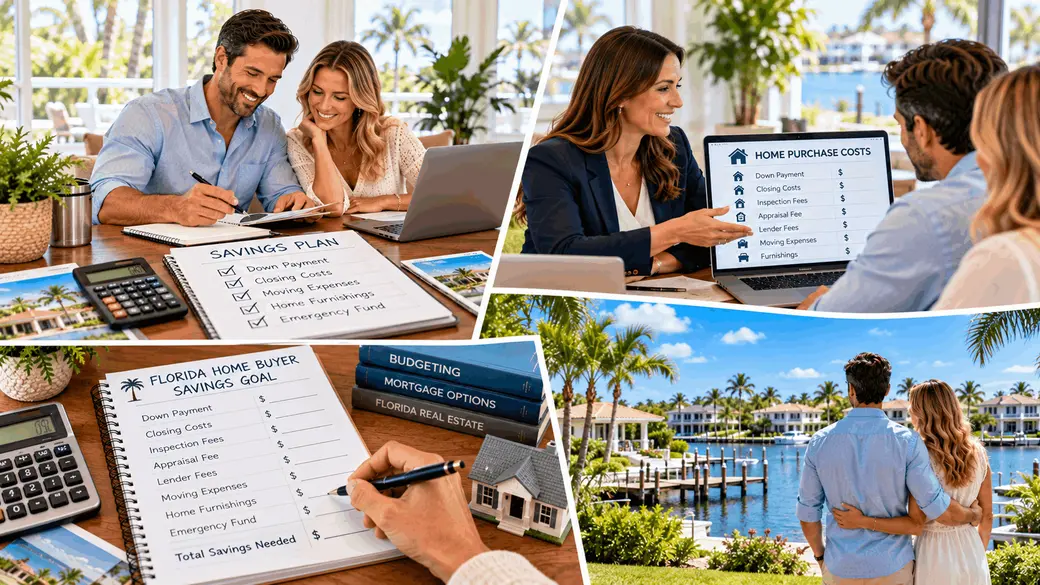
Before buying a home, save for more than the down payment. A practical savings target should cover your selected down payment, estimated closing costs, inspections and other pre-closing expenses, moving and immediate home expenses, plus savings you intend to keep after closing. The Consumer Financial Protection Bureau recommends subtracting an emergency cushion of at least three to six months of expenses when determining how much cash is actually available for a home purchase. Your appropriate savings target depends on your financing, household budget, property and risk tolerance, so there is no single dollar amount that fits every buyer.
Quick Answers About How Much to Save Before Buying a Home
Do I Need to Save 20% Before Buying a House?
No. A 20% down payment is not universally required. Depending on eligibility, loan program and lender requirements, some buyers can qualify with substantially less, but a smaller down payment can affect the mortgage amount, monthly payment, mortgage insurance and other financing terms.
What Should I Save for Besides the Down Payment?
Plan separately for closing costs, inspections, moving expenses, immediate repairs or purchases and post-closing savings. Depending on the property, insurance, association charges and specialized inspections can also affect how much cash you need.
How Much Should I Budget for Closing Costs?
For preliminary planning, approximately 2% to 5% of the purchase price can help illustrate the possible scale of closing costs, excluding the down payment. This is not a guaranteed Florida average or transaction quote. Your lender and closing professional should provide property-specific figures.
Should I Use All My Savings to Buy a House?
Not automatically. Closing with little cash remaining can make routine repairs or an unexpected expense more difficult to absorb. Decide how much you want to preserve for emergencies and known post-closing expenses before deciding how much cash to commit to the purchase.
Is Three to Six Months of Expenses Enough After Closing?
Three to six months of expenses is a useful general emergency-cushion starting point, not a rule for every household. Your appropriate reserve may be different based on income stability, other obligations, property condition, insurance deductibles and anticipated expenses.
How Much Should I Save for a $400,000 Home?
With a hypothetical 5% down payment, you would need $20,000 for the down payment alone. A broad 2% to 5% closing-cost illustration adds $8,000 to $20,000, producing $28,000 to $40,000 before inspections, moving expenses and the savings you want to keep after closing. Actual costs can be higher or lower.
When Should I Start Saving for a Home?
Start as early as practical because your target includes more than the down payment. Once you know your approximate purchase range and financing options, you can replace a generic savings goal with a specific monthly target.
What Should Your Home-Buying Savings Actually Cover?
Instead of asking only how large your down payment should be, divide your savings goal into separate categories. This makes it easier to see how much money is available for the purchase without accidentally spending cash intended for another purpose.
- Down payment: The portion of the purchase price you plan to pay rather than finance.
- Closing costs: Loan, settlement, title, government, prepaid and other applicable transaction expenses.
- Pre-closing expenses: Inspections, specialized evaluations and other costs that may be paid before settlement.
- Moving and initial home expenses: Moving, utility setup, furnishings, immediate repairs and other near-term costs.
- Post-closing savings: Money intentionally kept available after the transaction.
Your total savings goal should account for all five categories rather than assuming every dollar saved belongs in the down payment.
How Much Should You Save for a Down Payment?
The right down payment is not necessarily the largest one you can make. It should be evaluated alongside your financing costs, monthly payment and remaining savings.
For example, here is what several down-payment percentages represent mathematically:
| Home Price | 3% Down | 5% Down | 10% Down | 20% Down |
|---|---|---|---|---|
| $300,000 | $9,000 | $15,000 | $30,000 | $60,000 |
| $400,000 | $12,000 | $20,000 | $40,000 | $80,000 |
| $500,000 | $15,000 | $25,000 | $50,000 | $100,000 |
| $750,000 | $22,500 | $37,500 | $75,000 | $150,000 |
These figures are arithmetic illustrations only. They do not indicate that a particular buyer qualifies for financing at any of the percentages shown.
A qualified mortgage lender can compare down-payment scenarios and explain how each one changes your loan amount, interest rate, mortgage insurance when applicable, monthly payment and cash required to close.
Why Should Closing Costs Have Their Own Savings Bucket?
Closing costs are separate from the down payment, so saving only enough for the down payment can leave a significant gap in your purchase budget.
For preliminary planning, a broad range of approximately 2% to 5% of the purchase price can help illustrate the potential scale of closing costs. Actual expenses can fall outside this range.
| Purchase Price | 2% Illustration | 5% Illustration |
|---|---|---|
| $300,000 | $6,000 | $15,000 |
| $400,000 | $8,000 | $20,000 |
| $500,000 | $10,000 | $25,000 |
| $750,000 | $15,000 | $37,500 |
Depending on the transaction, buyer expenses can include mortgage charges, appraisal costs, title and settlement services, recording charges, applicable Florida mortgage taxes, prepaid interest, homeowners insurance and initial escrow deposits.
For a detailed Florida breakdown, read Florida Buyer Closing Costs in 2026.
How Much Should You Save for Inspections?
Inspection costs should be planned separately because they are often paid during the transaction rather than included in the final amount due at closing.
The appropriate inspections depend on the property. A Florida buyer may consider a general home inspection and, when appropriate, specialized evaluation of items such as:
- Roof
- HVAC system
- Electrical system
- Plumbing
- Pool and pool equipment
- Wood-destroying organisms
- Well or septic system
- Dock or seawall
- Structural conditions requiring specialized evaluation
There is no appropriate universal inspection budget because scope and pricing depend on the property and professionals selected. Inspection findings should be evaluated with the appropriate licensed inspector, contractor, engineer or other qualified professional before the buyer makes a property decision.
How Much Should You Keep in Savings After Closing?
The amount left after closing can be just as important as the amount you bring to closing.
The Consumer Financial Protection Bureau's down-payment guidance recommends subtracting money for other savings goals, moving and renovations before calculating available purchase cash. It then recommends subtracting an additional emergency cushion, using at least three to six months of expenses as a rule-of-thumb starting point.
That does not mean every buyer must have exactly six months of expenses remaining. A household with stable income and few obligations may assess reserves differently from a self-employed buyer or a buyer purchasing an older property with several aging systems.
Read How Much Savings Should You Keep After Buying a House? for a more detailed reserve-planning framework.
Why Do Florida Buyers Need to Think About Insurance Before Setting a Savings Target?
Insurance can affect both the cash required to complete a purchase and the amount of savings you may want to preserve afterward.
A financed buyer may encounter prepaid homeowners insurance and initial insurance escrow funding at closing. After purchasing, the homeowner also needs to understand policy deductibles and other potential out-of-pocket exposure.
Insurance availability, coverage, exclusions, deductibles and premiums can vary substantially by property. Buyers should obtain property-specific quotes and review coverage with a qualified insurance professional before making a purchasing decision based on an assumed insurance cost.
Should Florida Buyers Save for Repairs Before Purchasing?
Yes, particularly when a property has known maintenance needs or aging components. A home inspection reduces uncertainty but cannot guarantee that nothing will require attention after closing.
Potential early ownership expenses can include:
- HVAC service or replacement
- Roof repairs
- Plumbing or electrical work
- Appliance replacement
- Painting
- Landscaping
- Pool equipment
- Pest treatment
- Property-specific maintenance
A newer home is not automatically maintenance-free, and an older home is not automatically a poor financial choice. The appropriate repair reserve should reflect the actual property's condition and the findings of qualified professionals.
Do Condo and HOA Buyers Need Additional Savings?
Potentially. Association properties can have financial obligations that differ from those of a home without a mandatory association.
Depending on the community and transaction, buyers may encounter:
- Recurring association assessments
- Application or administrative charges
- Capital contributions or other authorized charges
- Current special assessments
- Property expenses not covered by the association
- Future expenses associated with ownership of the individual unit or home
Before relying on a savings estimate, verify current association charges, approved assessments and applicable financial obligations. Questions about association financial condition, reserves, structural obligations or legal rights should be reviewed with the association and the appropriate qualified attorney, CPA, inspector, engineer or other professional.
What Does a Realistic Home Savings Target Look Like?
Consider a hypothetical buyer targeting a $400,000 home with a 5% down payment.
| Savings Category | Illustrative Amount |
|---|---|
| 5% down payment | $20,000 |
| Illustrative 2% to 5% closing-cost range | $8,000 to $20,000 |
| Inspections and other pre-closing expenses | Property-specific |
| Moving and immediate home expenses | Household-specific |
| Emergency and post-closing reserves | Household-specific |
The first two categories alone produce a preliminary $28,000 to $40,000 illustration. But calling $28,000 the amount this buyer "needs to save" would be misleading because it ignores inspections, moving, immediate expenses and whatever reserve the buyer decides to maintain.
It also does not account for deposits already paid, negotiated seller concessions or other credits that could change the final cash required at settlement.
Can Seller Concessions Reduce the Amount You Need at Closing?
Potentially. Depending on the transaction and financing, buyers may negotiate seller contributions toward allowable closing costs, prepaid expenses, mortgage discount points, rate buydowns or other permitted expenses.
Seller concessions are negotiable, and mortgage programs can limit their amount and permitted use. They should therefore be treated as a possible transaction benefit rather than assumed when establishing your initial savings goal.
For more detail, read Seller Concessions in Florida: What Can Homebuyers Ask For in 2026?
Should You Wait Until You Have a 20% Down Payment?
Not necessarily. Whether waiting is appropriate depends on your financing options, housing needs, monthly budget, savings position and broader financial circumstances.
A larger down payment can reduce the amount financed and may affect mortgage insurance or loan pricing. But waiting specifically to reach 20% can also delay a purchase that may otherwise fit a buyer's circumstances using an eligible lower-down-payment mortgage.
Rather than treating 20% as an automatic target, ask a qualified lender to compare multiple financing scenarios. Evaluate the resulting monthly payment, upfront cash requirement, mortgage insurance when applicable and savings remaining after closing.
How Can You Build a Home-Buying Savings Target?
A useful starting formula is:
Target down payment + estimated closing costs + inspections and pre-closing expenses + moving and immediate home expenses + desired post-closing savings = preliminary home-buying savings target.
Once you have that target, divide the remaining amount you need by the number of months before your desired purchase date.
For example, if your preliminary goal is $50,000 and you already have $26,000 specifically available for the home purchase and related reserves, the remaining gap is $24,000. Reaching that amount in 24 months would require an average of $1,000 per month, assuming no investment gains, interest, withdrawals or changes in the target.
That is simply savings arithmetic, not individualized financial advice. A qualified financial professional can help evaluate savings priorities when home buying competes with retirement, debt repayment, education or other financial goals.
When Should You Talk to a Mortgage Lender?
You do not need to wait until you believe your savings are complete before speaking with a qualified mortgage professional.
An early conversation can help identify:
- Potential mortgage programs
- Possible down-payment requirements
- Estimated closing expenses
- Applicable mortgage insurance
- Lender reserve requirements when applicable
- Credit issues that may need attention
- Potential assistance programs for which you may qualify
The goal is not to obtain the largest possible approval. It is to understand your financing choices so you can build a realistic savings and purchase plan.
How Do You Know When You Have Saved Enough to Start Looking?
You do not necessarily need to have every eventual dollar sitting in one account before beginning preliminary research. But before serious home shopping and making offers, you should understand where the required funds are expected to come from and whether your target is realistic.
A prepared buyer should be able to answer:
- What price range fits my total monthly budget?
- What down-payment options have I discussed with a lender?
- What preliminary closing-cost range am I using?
- Do I have funds available for inspections?
- How much do I want to keep after closing?
- Have I budgeted for moving and immediate property expenses?
- Can I adjust the budget when taxes, insurance and association costs become property-specific?
The Hunt Brothers Realty guide to the true cost of buying a home in Florida can help you identify expenses that are easy to overlook during this stage.
The Best Savings Target Is More Than the Minimum Needed to Close
The amount required to reach the closing table and the amount you should personally save before buying are not necessarily the same number.
Your lender and closing professional can eventually calculate the transaction's required cash to close. Your broader savings plan also needs to consider inspections, moving, immediate home expenses and the cash you intentionally want to preserve after the purchase.
That is why the strongest answer to "How much should I save before buying a home?" is not a fixed percentage. Build the target from the actual components of your purchase and preserve enough flexibility for homeownership after closing.
Prepare for Your Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty helps buyers evaluate Florida Gulf Coast properties while considering the real estate factors that can affect the purchase and ownership budget. Before beginning your search, review Florida buyer closing costs, understand the true cost of buying a Florida home, and consider how much savings to keep after buying.
You can also explore Florida Gulf Coast communities to see how property type, location and community structure can affect your home-buying plan.
When you are ready to define your search and compare properties, contact Hunt Brothers Realty.
This article provides general real estate and educational information only. It is not individualized financial, lending, tax, insurance, legal, inspection, engineering, title or other professional advice. The appropriate amount to save, down-payment requirements, mortgage qualification, closing costs, insurance, taxes, association expenses and financial reserves depend on the buyer, property, financing and transaction. Buyers should verify transaction-specific information and consult the appropriate qualified mortgage lender or loan professional, financial or tax professional, insurance agent, licensed real estate professional, Florida real estate attorney, home inspector, engineer, association, title or closing professional and governmental authority before making decisions requiring individualized guidance.
Sources
- Consumer Financial Protection Bureau, Determine Your Down Payment
- Hunt Brothers Realty, Florida Buyer Closing Costs in 2026
- Hunt Brothers Realty, How Much Savings Should You Keep After Buying a House?
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
- Hunt Brothers Realty, Seller Concessions in Florida
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2070
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1131
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1049
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1240
- Foreclosures 3
- Home Selling 3
- Homeownership 1263
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1204
- Market Updates & Trends 730
- Mortgages & Financing 42
- Move-Up Buyers 21
- Neighborhood Guides 842
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1121
- Relocation to Florida 1163
- Safety Harbor 2
- Sarasota 77
- Sarasota - Downtown 162
- Selling a Home 144
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1313
- Venice 169
- Wellen Park 16
Recent Posts