How Do I Compare Two Homes Before Deciding Which One to Buy?
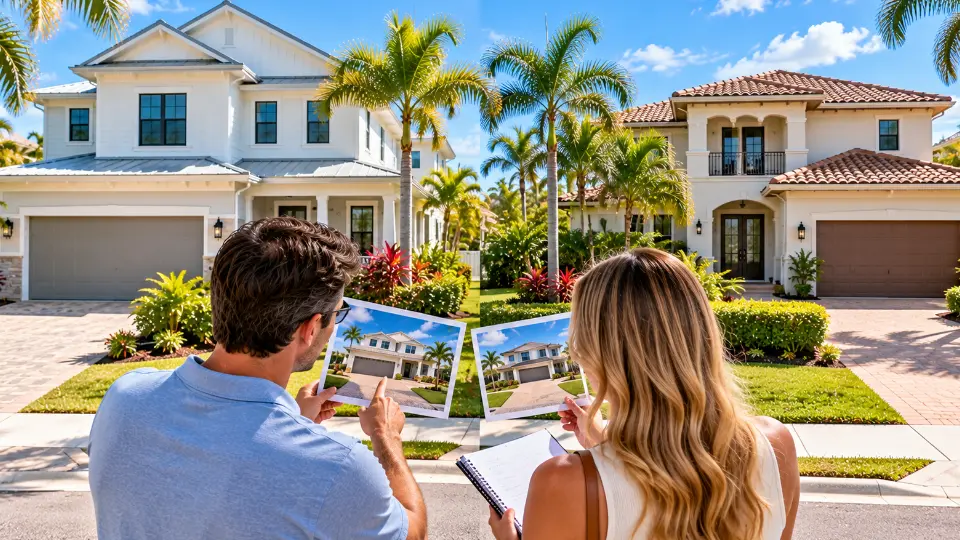
When two homes both seem like good choices, compare more than price, square footage, and finishes. Start with the factors you cannot easily change, including location, lot, floor plan, ownership structure, and community. Then compare total ownership costs, property-specific insurance, taxes, HOA or condominium expenses, flood considerations, and expected repairs. Finally, separate true priorities from cosmetic preferences. A slightly more expensive home can sometimes be the better fit if it has fewer near-term projects or lower recurring costs, while the less expensive home may make more sense when its disadvantages are inexpensive to correct.
Quick Answers About Comparing Two Homes
What is the best way to compare two homes?
Compare them in the same categories: location, layout, condition, total ownership cost, insurance, taxes, association obligations, flood considerations, future maintenance, and lifestyle fit. Using the same criteria prevents one home's renovated kitchen from distracting you from more consequential differences.
Should I simply buy the less expensive home?
Not necessarily. Purchase price is only one part of the comparison. Insurance, taxes, HOA or condominium assessments, repairs, maintenance, utilities, financing, and renovations can make two similarly priced homes very different financially.
What matters more, the house or the location?
There is no universal answer, but location deserves substantial weight because you generally cannot move the lot after purchasing. Paint, appliances, flooring, and many interior finishes can be changed. Distance from work, lot orientation, waterfront position, surrounding land uses, and access to places important to you usually cannot.
How should I compare the condition of two homes?
Pay particular attention to potentially expensive systems such as the roof, HVAC, electrical system, plumbing, windows and doors, water heater, pool equipment, and structural components. A qualified home inspector and appropriate specialists should evaluate material concerns before you make a decision based on technical condition.
Should I get insurance quotes before choosing?
When two Florida properties are serious candidates, property-specific insurance information can reveal meaningful differences. Coverage availability, premiums, deductibles, flood insurance considerations, and underwriting requirements can vary substantially between homes. Review actual quotes and coverage with a qualified insurance professional.
What if one home is in an HOA and the other is not?
Compare both the cost and the ownership experience. An HOA may provide amenities or services, but it can also impose assessments, maintenance responsibilities, architectural requirements, and use restrictions. Review the specific association rather than assuming an HOA is automatically an advantage or disadvantage.
What if I still cannot decide?
Return to your original must-haves and compare the homes without considering easily changed cosmetic features. If both still work, focus on the differences that will affect everyday life and long-term ownership, not which property produced the stronger first impression.
Start by Separating Must-Haves From Preferences
The hardest home comparisons often happen because buyers have two properties they like for completely different reasons. One may have the better location. The other may have the better kitchen. One may be newer. The other may have the larger lot.
Before comparing those features, divide your priorities into three groups:
- Must-have: A requirement that materially affects whether the property works for you.
- Strong preference: Important enough to influence the decision, but not necessarily a deal breaker.
- Nice-to-have: Something you would enjoy but could comfortably live without.
This distinction prevents a dramatic lanai, new countertops, attractive staging, or another memorable feature from receiving the same weight as something fundamental to your plans.
Compare the Things You Cannot Easily Change First
A useful rule is to evaluate permanent or difficult-to-change characteristics before cosmetic ones.
Depending on the properties, those characteristics might include:
- Location
- Lot size and orientation
- Property type
- Overall floor plan
- Number of bedrooms and bathrooms
- Garage configuration
- Waterfront or golf-course position
- Condominium or HOA structure
- Distance from frequently visited destinations
- Community amenities
- Views
- Surrounding land uses
Interior paint can be changed. Flooring can be replaced. A dated bathroom can be renovated. Changing the lot, moving the house closer to downtown, creating a waterfront location, or removing association restrictions is usually not realistic.
Compare Total Ownership Cost, Not Just Purchase Price
Two homes listed at similar prices can produce substantially different ownership costs. Hunt Brothers Realty's guide to the true cost of buying a home in Florida explains why buyers should look beyond the mortgage when establishing a realistic budget.
For each property, compare:
- Purchase price
- Financing costs
- Estimated property taxes after purchase
- Homeowners insurance
- Flood insurance when applicable or desired
- HOA or condominium assessments
- CDD assessments when applicable
- Known or anticipated special assessments
- Utilities
- Pool maintenance
- Landscaping
- Routine maintenance
- Immediate repairs or renovations
- Likely future major replacements
- Optional club or membership expenses important to your plans
Do not automatically use the seller's current property-tax bill or insurance premium as your future cost. Taxes, insurance underwriting, coverage, exemptions, and financing circumstances can change after a sale. Obtain property-specific estimates from the appropriate county property appraiser, lender, insurance professional, and tax professional when individualized guidance is needed.
Compare the Homes Using the Same Cost Worksheet
| Comparison | Home A | Home B |
|---|---|---|
| Purchase price | ||
| Estimated post-purchase property taxes | ||
| Homeowners insurance quote | ||
| Flood insurance, if applicable | ||
| HOA or condo assessments | ||
| CDD or other recurring assessments | ||
| Immediate repairs | ||
| Desired renovations | ||
| Major systems nearing replacement |
The goal is not to predict every future dollar. It is to expose meaningful cost differences that may be hidden when you compare only listing prices.
Compare Insurance Before It Becomes a Surprise
Insurance deserves its own comparison for Florida homes. Properties that appear similar on paper can receive different insurance quotes because of characteristics such as age, construction, roof information, wind-mitigation features, location, and other underwriting factors.
An older home with a lower asking price may not remain the less expensive option if insurance costs or required improvements are substantially higher. Conversely, a newer or updated home should not automatically be assumed to have lower insurance without obtaining property-specific information.
Insurance availability, coverage, deductibles, exclusions, underwriting requirements, and premiums can vary substantially by property. Buyers should obtain property-specific quotes and review the proposed coverage with a qualified insurance professional before making a purchasing decision that depends on those numbers.
Compare the Roof, HVAC, Plumbing, Electrical, and Other Major Systems
Cosmetic condition is easy to notice during a showing. The more important differences can be less obvious.
When comparing Florida homes, investigate major components such as:
- Roof age, type, condition, permits, and available documentation
- HVAC age and condition
- Electrical system and panels
- Plumbing materials and condition
- Water heater
- Windows and exterior doors
- Documented storm-protection features
- Moisture or water-intrusion concerns
- Drainage
- Pool and pool equipment when applicable
- Septic or well systems when applicable
- Seawalls, docks, lifts, and other waterfront infrastructure when applicable
Florida Realtors recommends paying particular attention to potentially expensive items such as roofs, windows, HVAC equipment, water heaters, foundations, and evidence of termite or water damage when reviewing inspection information.
A showing is not a substitute for a professional inspection. Inspection findings should be evaluated with the appropriate licensed home inspector, contractor, structural engineer, electrician, plumber, pool professional, or other qualified specialist before you make a purchasing decision based on a technical property issue.
Compare Flood Considerations Property by Property
Flood exposure can differ between two homes in the same general area, and a property does not need to be directly waterfront to warrant flood due diligence.
Florida's residential real property flood disclosure requirement took effect October 1, 2024. Among other information, the disclosure reminds buyers that homeowners insurance does not include flood coverage and requires disclosure of certain seller flood-claim and federal-assistance history.
For coastal properties, Hunt Brothers Realty's questions to ask before buying a home near the coast includes flood zones, elevation, storm history, drainage, insurance, wind protection, seawalls, docks, and boating considerations in the due-diligence process.
Current flood-zone designations, elevation information, insurance requirements, premiums, drainage conditions, and engineering issues are property-specific. Verify material concerns with the appropriate insurance professional, surveyor, engineer, lender, local authority, or other qualified professional.
If One Home Has an HOA, Compare More Than the Fee
A $200 monthly HOA and a $400 monthly HOA cannot be compared meaningfully without knowing what each association provides and what the homeowner remains responsible for maintaining.
Review the governing documents, current assessments, budget, available financial information, reserves where applicable, special assessments, maintenance responsibilities, architectural requirements, rental policies, pet rules, parking restrictions, and other provisions important to your intended use.
Hunt Brothers Realty's Florida HOA buyer guide also explains why buyers should check whether a property is subject to a Community Development District, multiple associations, or other recurring obligations.
Association documents create legal rights and obligations. Questions about the meaning or enforceability of restrictions, assessments, contracts, ownership rights, or other legal provisions should be reviewed with the association and a qualified Florida real estate attorney when individualized legal guidance is required.
If You Are Comparing Condos, Compare the Associations Too
Choosing between two condominiums requires two comparisons: unit versus unit and association versus association.
Florida condominium buyers may need to evaluate current budgets, financial statements, reserves, assessments, association insurance, governing documents, maintenance responsibilities, and applicable structural inspection information. For qualifying buildings, milestone inspection reports and Structural Integrity Reserve Studies can provide important information about building condition and future reserve funding.
Florida's Department of Business and Professional Regulation explains that a milestone inspection evaluates an aging building for substantial structural deterioration, while a Structural Integrity Reserve Study is a budget-planning tool addressing specified building components and future reserve funding. They serve different purposes.
A beautifully renovated condo in an association facing major unfunded work can present a very different ownership picture from a less updated unit in a building with stronger reserves and fewer near-term projects. Buyers should have structural, financial, insurance, association, and legal questions reviewed by the appropriate qualified professionals before relying on those factors in a purchase decision.
Compare the Floor Plans, Not Just the Square Footage
A larger home does not automatically function better. A well-designed 1,900-square-foot property may work better for a particular buyer than a 2,200-square-foot home with space allocated in less useful ways.
Walk through both homes while thinking about everyday routines:
- Where will groceries enter the house?
- Is there enough kitchen storage?
- Does the primary bedroom provide the privacy you want?
- Will guests have appropriate space?
- Is there a workable home office?
- Can your existing furniture fit?
- Is laundry conveniently located?
- Is there enough garage and storage space?
- Will the layout still work if your needs change?
Try mentally living in each house rather than simply touring it.
Compare Location Based on Your Actual Routine
Instead of deciding that one location is generally "better," compare how each location works for you.
Consider your travel to places you expect to use regularly, such as:
- Work
- Shopping and groceries
- Healthcare providers
- Beaches
- Downtown
- Golf
- Marinas or boat ramps
- Restaurants and entertainment
- Airport
- Friends and family
- Parks and recreational facilities
If location is a major difference between the properties, drive the routes you expect to use at realistic times rather than relying only on a mapping application's best-case estimate.
Compare Renovation Needs Realistically
Buyers sometimes describe one property as needing "$20,000 of work" without obtaining any meaningful estimate. That assumption can distort the comparison.
Separate work into three categories:
- Necessary now: Repairs or deficiencies requiring prompt attention.
- Likely later: Aging components that may require future replacement.
- Optional: Changes based primarily on your preferences.
When renovation cost materially affects which home you choose, obtain realistic estimates from qualified contractors or tradespeople and verify permitting requirements with the appropriate local authority. Do not base a major purchase decision on an informal renovation estimate.
Do Not Give Cosmetic Upgrades Too Much Weight
A recently remodeled kitchen can make one house feel dramatically more appealing during a showing. That does not mean it should outweigh every other category.
Try asking a simple question:
If both homes had identical paint, furniture, flooring, and countertops, which one would I choose?
That question can reveal whether you prefer the underlying property or simply its current presentation.
Use a Weighted Home Comparison Scorecard
A scorecard can help when the decision feels emotional, but the categories should reflect your priorities rather than someone else's formula.
Assign each category an importance level from 1 to 5, with 5 meaning extremely important. Then rate each property from 1 to 5 in that category. Multiply the two numbers to create a weighted score.
| Category | Importance | Home A | Home B |
|---|---|---|---|
| Location | 1-5 | 1-5 | 1-5 |
| Floor plan | 1-5 | 1-5 | 1-5 |
| Property condition | 1-5 | 1-5 | 1-5 |
| Total ownership cost | 1-5 | 1-5 | 1-5 |
| Insurance considerations | 1-5 | 1-5 | 1-5 |
| Outdoor space | 1-5 | 1-5 | 1-5 |
| Community and amenities | 1-5 | 1-5 | 1-5 |
| Maintenance requirements | 1-5 | 1-5 | 1-5 |
| Lifestyle fit | 1-5 | 1-5 | 1-5 |
The score should help organize your thinking, not make the decision for you. A property that violates a genuine must-have should not necessarily win simply because it accumulated more points elsewhere.
Visit Both Homes Again Before Deciding
If circumstances permit, a second showing can be valuable. The first visit often answers, "Do I like this house?" The second can focus on, "How would I actually live here?"
During the second visit, spend less time looking at finishes and more time checking practical details:
- Storage
- Closet sizes
- Garage dimensions
- Natural light
- Outdoor space
- Traffic and access
- Room dimensions
- Furniture placement
- Laundry location
- Visible maintenance needs
- Lot orientation
- Views from the rooms you will use most
You may discover that something you barely noticed during the first showing becomes important once you compare the homes directly.
Ask Which Home Solves More Problems Without Creating New Ones
A useful final comparison is to stop asking which home has more features and ask which one better supports your reason for moving.
If you are moving because your current house requires too much maintenance, choosing another maintenance-intensive property may not solve the problem. If you want more space for guests, a home with greater square footage but an awkward guest layout may not accomplish the goal. If you want to spend more time boating, golf, beach access, or downtown proximity may matter less than practical access to the water.
Return to the reason you began the home search. The better choice is often the property that addresses that objective with the fewest meaningful compromises.
Do Not Let Fear of Choosing Wrong Become the Decision
When two homes both meet your major requirements, there may not be one objectively perfect answer. Each property may offer a different combination of benefits and compromises.
The purpose of comparison is not to eliminate every uncertainty. It is to understand the important differences well enough to make an informed decision based on your priorities, budget, and intended use of the property.
A strong comparison should leave you able to explain why one home fits you better without relying solely on statements such as "it felt nicer" or "the kitchen was prettier."
A Final Two-Home Comparison Checklist
- Which home meets more of my genuine must-haves?
- Which location works better for my actual routine?
- Which floor plan functions better?
- What are the realistic total ownership costs?
- Have I obtained property-specific insurance information?
- Have I evaluated flood considerations where relevant?
- Which home has more near-term maintenance or repair exposure?
- What do professional inspections reveal?
- Have I reviewed HOA or condominium obligations where applicable?
- Are special assessments or major association projects relevant?
- What would I want to renovate immediately?
- Have qualified contractors provided realistic estimates for material projects?
- Which home's disadvantages can actually be changed?
- Which home's disadvantages are permanent?
- Which property better accomplishes the reason I am moving?
Compare Florida Homes With Hunt Brothers Realty
A useful buyer's agent should help you compare properties beyond listing photos and asking prices. That can include researching property information, discussing comparable sales and market context, identifying questions for further investigation, coordinating inspections, and helping you evaluate how each property fits the objectives of your search.
The Hunt Brothers Realty Florida Buyer Resource Center provides additional guidance on Florida contracts, financing, relocation, lifestyle considerations, and buyer representation.
If you are deciding between two Sarasota, Manatee County, Charlotte County, or other Florida Gulf Coast properties, contact Hunt Brothers Realty to discuss your home search.
This article is provided for general informational and educational purposes only. It is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction, title, association, or other professional advice. Financing, taxes, insurance, flood considerations, property condition, association obligations, inspection findings, contract rights, and ownership costs vary by buyer and property. Buyers should verify material information with a licensed real estate professional and consult the appropriate mortgage lender, insurance agent, Florida real estate attorney, tax professional or CPA, home inspector, structural engineer, contractor or qualified tradesperson, title or closing professional, surveyor, condominium or homeowners association, local government authority, or other qualified professional when a purchasing decision requires individualized guidance.
Sources
- Florida Realtors, 15 Essential Questions for Smart House Hunting
- Florida Realtors, Navigating HOA Rules
- Florida Department of Business and Professional Regulation, Condominium Inspections and Structural Integrity Reserve Studies
- Florida Department of Business and Professional Regulation, Condominium Information and Resources
- Florida Department of Financial Services, Property Insurance and Flood Disclosure Changes
- Hunt Brothers Realty, Florida Buyer Resource Center
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
- Hunt Brothers Realty, Buying a Home in a Florida HOA
- Hunt Brothers Realty, Questions to Ask Before Buying a Home Near the Coast
- Hunt Brothers Realty, 4-Point Inspections in Florida
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2232
- Anna Maria Island 86
- Bird Key 4
- Bradenton 237
- Buying a Home 1284
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1203
- Ellenton 6
- Englewood 12
- First Time Homebuyers 1395
- Foreclosures 5
- Home Selling 7
- Homeownership 1421
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1362
- Market Updates & Trends 880
- Mortgages & Financing 64
- Move-Up Buyers 25
- Neighborhood Guides 997
- New Construction 37
- Palmetto 3
- Parrish 6
- Port Charlotte 11
- Punta Gorda 57
- Real Estate Investing 1278
- Relocation to Florida 1316
- Safety Harbor 3
- Sarasota 93
- Sarasota - Downtown 165
- Selling a Home 146
- Siesta Key 92
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1472
- Venice 209
- Wellen Park 20
Recent Posts