Is Buying a Condo in Florida Worth It?
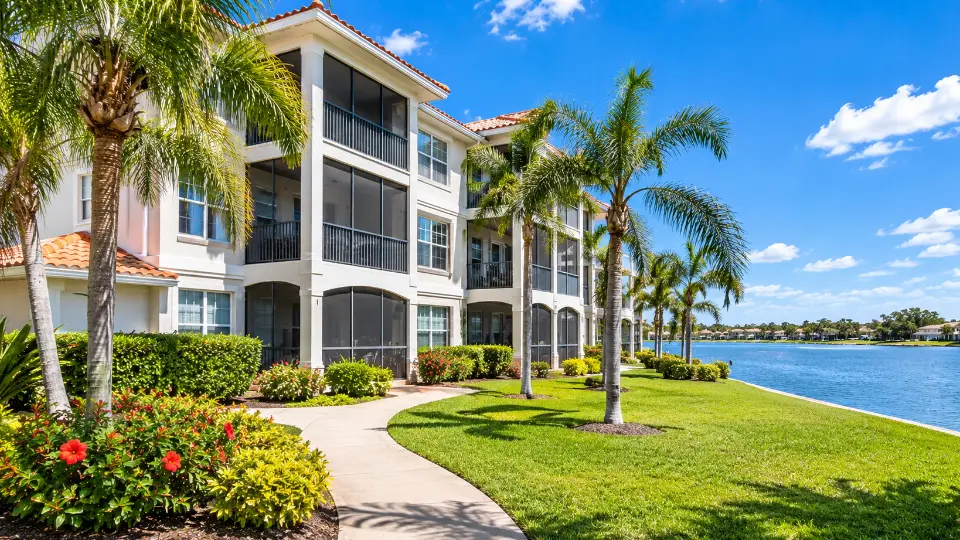
Buying a condo in Florida can be worth it when the location, lower-maintenance lifestyle, amenities and purchase price fit your goals, and the condominium association is financially and physically positioned for its obligations. The mistake is judging a condo only by the unit, view or monthly fee. Buyers also need to investigate reserves, special assessments, insurance, major building projects, applicable milestone inspections and Structural Integrity Reserve Studies, association rules and financing eligibility. A well-chosen condominium can provide an attractive Florida lifestyle, but a seemingly inexpensive unit can become costly if important building-level obligations are overlooked.
Quick Answers About Buying a Condo in Florida
Is buying a Florida condo a good idea?
It can be. Condos can provide desirable locations, shared amenities and less direct exterior maintenance than many single-family homes. Whether a particular condo is a sound choice depends on the unit, association finances, building condition, insurance, fees, assessments, rules and your individual plans.
What is the biggest risk when buying a condo in Florida?
One significant risk is buying the individual residence without adequately investigating the condominium association and shared building obligations. Underfunded future expenses, major repairs, insurance costs or special assessments can materially change the cost of ownership.
Are Florida condo fees getting higher because of reserve requirements?
Some associations subject to Florida's Structural Integrity Reserve Study requirements may need greater reserve contributions to follow their funding plans. However, condo assessments can also change because of insurance, utilities, staffing, maintenance, repairs and other operating expenses, so buyers should investigate the reason behind a specific building's fee changes.
Do all Florida condos require milestone inspections?
No. Current Florida requirements generally apply milestone inspections to condominium and cooperative buildings that are three or more habitable stories high once they reach the applicable age. The standard initial age is 30 years, although a local enforcement agency can require the initial inspection at 25 years based on local circumstances.
What is a Structural Integrity Reserve Study?
A Structural Integrity Reserve Study, commonly called a SIRS, evaluates specified association-maintained building components and the reserve funding needed for future repair and replacement obligations. Florida generally requires a SIRS at least every 10 years for residential condominium association buildings that are three or more habitable stories high, subject to statutory requirements and exceptions.
Does a low monthly condo fee mean a building is a better deal?
Not necessarily. A low fee may reflect fewer amenities and lower expenses, or it may warrant closer investigation of reserve funding and anticipated projects. Buyers should determine what the assessment covers and how the association plans to fund its obligations.
Can a special assessment make a Florida condo a bad purchase?
Not automatically. A special assessment may be funding necessary or valuable work such as structural repairs, roofing or waterproofing. Buyers should determine what the assessment funds, how much applies to the unit, whether the project is complete and whether additional major expenses are anticipated.
Is a condo less expensive than a house in Florida?
A condo can have a lower purchase price than a comparable single-family home, but purchase price is only part of the comparison. Regular association assessments, insurance, taxes, special assessments and unit maintenance all contribute to the actual ownership cost.
When Is Buying a Condo in Florida Worth It?
Condominium ownership can make particular sense when it provides access to a location or lifestyle that would otherwise be difficult to achieve. In Sarasota, for example, condos are a major part of the housing market in Downtown Sarasota, Siesta Key, Lido Key and Longboat Key.
A buyer may prefer a condominium because exterior maintenance and common property are handled through the association. Depending on the community, assessments may also support pools, fitness facilities, landscaping, security or controlled access, elevators, building insurance and other shared services.
The tradeoff is shared financial responsibility and shared governance. A condo owner cannot evaluate ownership solely from inside the unit because the association's decisions, finances and common property can directly affect the owner's costs and experience.
For a deeper overview, read Hunt Brothers Realty's Florida condo buyer guide.
What Are the Main Advantages of Florida Condo Ownership?
Access to Desirable Locations
Condominiums can make waterfront, beach-area and downtown locations accessible at price points that may differ substantially from detached homes in the same area. This is particularly relevant along Florida's Gulf Coast, where land near the water and urban centers can carry a significant premium.
Less Direct Exterior Maintenance
The association generally handles designated common property and building responsibilities. Exactly where association responsibility ends and unit-owner responsibility begins depends on the declaration, governing documents and applicable law, so buyers should verify the division for the specific condominium.
Shared Amenities
Pools, fitness centers, clubrooms, tennis and pickleball courts, concierge services, gated access and waterfront facilities are common examples. A buyer can gain access to amenities that would be expensive to own and maintain individually.
A Different Maintenance Model for Part-Time Owners
A condominium can appeal to owners who do not want direct responsibility for maintaining a yard, roof, exterior walls or other association-maintained common components. That does not make ownership maintenance-free, because owners remain responsible for their units and their share of association expenses.
What Are the Biggest Drawbacks of Buying a Florida Condo?
The biggest drawbacks generally involve costs and control. Owners share responsibility for the association's expenses and must follow the condominium's governing documents and rules.
Potential considerations include:
- Regular condominium assessments
- Potential special assessments
- Reserve funding obligations
- Association insurance expenses
- Rules affecting pets, leasing, parking and renovations
- Shared decision-making through the association
- Potential financing requirements involving the condominium project
- Major repair projects affecting common property
These considerations do not make condos inherently undesirable. They mean that condominium due diligence extends beyond the individual residence.
Florida's Condo Reserve Rules Make Financial Review More Important
Florida's condominium reserve framework has changed substantially in recent years. For qualifying residential condominium buildings three or more habitable stories high, a Structural Integrity Reserve Study is generally required at least every 10 years.
According to the Florida Department of Business and Professional Regulation, a SIRS is a budget-planning tool designed to evaluate specified building components, existing reserve funding and the amount needed for anticipated repair or replacement expenses.
Required components include the roof, structural systems, fireproofing and fire-protection systems, plumbing, electrical systems, waterproofing and exterior painting, windows and exterior doors, plus qualifying additional components affecting structural integrity. DBPR lists the inflation-adjusted reserve threshold at $25,675 for 2026.
For associations subject to the SIRS requirements, owners generally cannot simply vote to waive the required reserve funding for the applicable SIRS components, subject to current statutory exceptions and alternative provisions.
Hunt Brothers Realty's Florida condo reserves guide explains why buyers should compare reserve balances with anticipated expenses rather than judging a building from one number.
What Is a Milestone Inspection?
A milestone inspection is a structural inspection used to determine whether substantial structural deterioration exists in an aging condominium or cooperative building. It is different from a Structural Integrity Reserve Study.
Current DBPR guidance states that residential condominium and cooperative buildings three or more habitable stories high generally require an initial milestone inspection at 30 years and every 10 years thereafter. A local enforcement agency may determine that local circumstances require the initial inspection at 25 years instead.
A Phase 1 milestone inspection is a visual structural assessment. If evidence of substantial structural deterioration is identified, a Phase 2 inspection may be required to further evaluate the building and recommend necessary repairs.
A milestone inspection should not be interpreted casually. Findings that could affect a purchase should be reviewed with an appropriately licensed engineer, architect or other qualified professional rather than relying solely on a summary from a seller, association or real estate professional.
Do Higher Reserve Contributions Make Condos a Worse Investment?
Not automatically. Higher reserve contributions increase current ownership costs, but reserves are intended to prepare for future repair and replacement obligations. A low monthly assessment achieved by postponing predictable funding needs is not necessarily a financial advantage.
The useful question is whether the association's funding plan makes sense in relation to its documented obligations. A building with a large reserve balance could still face expensive upcoming projects, while a building with a smaller balance may recently have completed substantial capital work.
There is no universal reserve balance or percentage that identifies a financially strong Florida condominium. Buyers should examine the complete financial picture and seek qualified accounting or financial review when the association's finances could materially affect the purchase decision.
Special Assessments Deserve Investigation, Not an Automatic Rejection
A special assessment is an additional association charge for a particular expense beyond regular assessments. It may fund structural repairs, roofing, waterproofing, storm-related work, insurance expenses, improvements or other association obligations.
An existing assessment does not automatically make a condo a poor purchase. If the assessment is paying for completed or well-defined improvements, the building may be in a different position from another property that has significant unfunded work approaching.
The buyer should determine why the assessment was imposed, the total project cost, the amount allocated to the unit, payment schedule, project status and whether additional work is anticipated. Hunt Brothers Realty's guide to Florida condo special assessments provides a more detailed review.
Questions about whether a buyer or seller is legally responsible for a particular assessment depend on the contract, timing, governing documents and applicable law and should be reviewed with a qualified Florida real estate attorney.
How Much Do Florida Condo Fees Really Matter?
Monthly assessments matter, but comparing buildings solely by the fee can be misleading. One condominium may include building insurance, reserves, water, cable, staffing, security and extensive amenities, while another provides fewer services.
Ask what the regular assessment actually pays for. Then compare that with expenses you would pay directly in another property.
More importantly, determine whether the current fee appears consistent with the association's budget, reserve plan and known obligations. A low fee today does not guarantee a low ownership cost tomorrow.
Florida Condo Insurance Has Two Important Layers
Condo buyers need to understand both association-level insurance and individual unit-owner coverage. The association's policy does not automatically eliminate the need for personal insurance.
The Florida Department of Financial Services explains that condominium owners generally use an HO-6 condominium unit-owner policy. This can address personal property, liability and certain unit-level building coverage, subject to the policy's terms, limits and exclusions.
Buyers should investigate the association's master insurance, deductibles, individual HO-6 needs, loss-assessment coverage and flood and wind considerations. Insurance availability, coverage and premiums vary substantially by property and building. Obtain property-specific information from a qualified Florida insurance professional before making a purchasing decision.
Can the Condo Association Affect Your Mortgage?
Yes. Being personally preapproved for a mortgage does not necessarily mean every condominium project will qualify for the intended financing.
Depending on the lender and loan program, project-level review can involve association insurance, finances, structural condition, litigation, owner delinquencies, assessments and other condominium characteristics.
Financing requirements vary by lender, loan program and condominium. Buyers using financing should have the specific project reviewed by a qualified mortgage professional early in the process rather than assuming personal preapproval guarantees project eligibility.
Older Florida Condos Are Not Automatically Bad Purchases
Building age is a reason to investigate, not a reason to automatically reject a condominium. An established building may have completed substantial roofing, structural, plumbing, waterproofing, window or mechanical projects.
Conversely, a visually attractive renovated unit does not tell you whether the common building has major expenses approaching. Kitchen cabinets and flooring reveal little about reserve funding, concrete restoration, elevators, roofs or insurance.
Review applicable inspection reports, engineering information, completed projects, planned work, reserves and assessment history. Structural or engineering findings should be evaluated with the appropriate licensed professionals.
Newer Condos Are Not Automatically Risk-Free
A newer condominium may not face the same immediate age-related capital projects as an older tower, but buyers still need to investigate the association, warranty matters, insurance, rules, fees and future maintenance obligations.
New buildings also may have amenities and service levels that create significant operating expenses. The relevant comparison is the complete ownership structure, not simply the construction year.
Are Florida Condos Worth It for Part-Time Residents?
They can be particularly appealing when an owner wants a residence without direct responsibility for much of the exterior and common-property maintenance. Controlled access and onsite management or staff may also be valuable features in some buildings.
However, part-time occupancy does not reduce the owner's obligation to pay assessments, and the unit still needs appropriate monitoring and insurance. Rules concerning vacancy, hurricane preparation, access to units and leasing should be checked in the applicable documents.
What About Buying a Florida Condo as a Rental?
Do not assume that purchasing a condominium automatically gives the owner unrestricted rental rights. Associations may regulate lease duration, frequency, tenant approval and other aspects of leasing, subject to the governing documents and applicable law.
Local government rules may also affect short-term rentals. Buyers considering rental use should verify association restrictions and applicable local requirements before relying on rental income in a purchasing decision.
Rental projections, tax consequences and legal restrictions should be evaluated with the appropriate property management, tax, legal and other qualified professionals. No rental income, occupancy level or investment return should be assumed or guaranteed.
Is a Florida Condo Better Than a Single-Family Home?
Neither is inherently better. They divide costs, responsibilities and control differently.
A single-family homeowner typically has more direct control over the property but also assumes more responsibility for the roof, exterior, landscaping and other components. A condominium owner shares many building responsibilities through the association but also shares the resulting costs and must follow association rules.
Hunt Brothers Realty's condo versus single-family home guide for Sarasota buyers provides a more detailed side-by-side comparison.
What Should You Review Before Buying a Florida Condo?
Strong condo due diligence looks in two directions at once: at the individual unit and at the condominium association. Depending on the property, buyers should investigate:
- Current regular condominium assessment
- Exactly what the assessment covers
- Current association budget
- Recent financial statements
- Reserve balances and contributions
- Applicable Structural Integrity Reserve Study
- Applicable milestone inspection reports
- Current and pending special assessments
- Major completed building projects
- Planned or discussed capital projects
- Association insurance and deductibles
- Individual HO-6 insurance requirements
- Flood and wind considerations
- Association debt and material liabilities
- Recent board and owner meeting minutes
- Pet restrictions
- Rental restrictions
- Parking and storage rights
- Renovation restrictions
- Financing eligibility
- Condition of the individual unit
For a more detailed document review, see Hunt Brothers Realty's guide to reading Florida condo documents before buying.
What Are Some Warning Signs That Deserve More Investigation?
No single issue automatically proves that a condominium is a poor purchase. However, several conditions can justify deeper due diligence:
- Major projects discussed without a clear funding plan
- Reserve balances that appear inconsistent with documented upcoming obligations
- Unresolved structural or engineering issues
- Large assessments with uncertain project scope
- Significant association debt or financial obligations requiring explanation
- Difficulty obtaining necessary association records
- Insurance issues that could affect ownership cost or financing
- Project-level financing concerns
These are reasons to obtain more information, not automatic conclusions about the condominium. Financial records may require review by a CPA or other qualified financial professional, legal issues by a Florida real estate attorney, and structural questions by an appropriately licensed engineer or other qualified building professional.
Florida Condo Buyers May Have More Choices in Some Markets
Market conditions can also affect whether a condo purchase is attractive at a particular time. For example, Hunt Brothers Realty's analysis of August 2026 Sarasota County data reported 5.2 months of condo and townhome supply compared with 3.7 months for single-family homes.
Additional inventory can give buyers more properties to compare and may create negotiating opportunities in some buildings or price ranges. It does not mean every condo seller will negotiate or that every condominium represents good value.
Building-specific information remains more important than a broad market label. Review Hunt Brothers Realty's Sarasota months-of-supply guide for current local market context.
Additional Questions About Buying a Condo in Florida
Can Florida condo owners still face special assessments if reserves are funded?
Yes. Reserve planning cannot anticipate every storm, unexpected condition, insurance expense, project overrun or owner-approved improvement. Strong reserves can help prepare for anticipated expenses but cannot guarantee that no future assessment will occur.
Is a newer Florida condo always safer financially?
No. Building age is only one factor. Buyers should evaluate the association's finances, insurance, responsibilities, construction and warranty matters, fees and long-term maintenance obligations regardless of age.
Should I avoid any condo with a high monthly fee?
No. Determine what the fee covers and why it is at that level. A higher fee can reflect substantial amenities, insurance, utilities, staffing and reserve contributions, while a lower fee may simply correspond to fewer services or different funding needs.
Should I inspect the individual condo unit?
A buyer should consider appropriate property inspections even when the association is responsible for much of the building. Unit-level plumbing, electrical components, HVAC equipment, appliances, moisture conditions, renovations and other items may still require evaluation by qualified inspectors or tradespeople.
Can I renovate a Florida condo however I want?
Not necessarily. Condominium documents can regulate flooring, plumbing changes, windows, doors, structural modifications, work hours, contractor requirements and approval procedures. Permitting requirements may also apply, so renovation plans should be verified before purchasing.
Are waterfront condos more complicated to evaluate?
They can involve additional considerations such as salt exposure, waterfront structures, flood risk, wind exposure and potentially higher insurance or maintenance costs. A water view also does not guarantee private dockage, a boat slip or unrestricted boating access, so those features should be independently verified.
So, Is Buying a Condo in Florida Worth It?
A Florida condo can absolutely be worth considering when it provides the location, lifestyle and maintenance arrangement you want at a total ownership cost that works for you. The decision becomes much stronger when the buyer understands both the individual residence and the association behind it.
The important distinction is between an inexpensive unit and a well-understood condominium purchase. Purchase price alone does not reveal reserves, upcoming projects, insurance expenses, assessment exposure, financing considerations or association rules.
For buyers considering Florida's Gulf Coast, Hunt Brothers Realty can help compare individual buildings, current listings and property-specific condominium information. Start with the Florida condo buyer guide, learn how Florida condo reserves work, review 12 questions to ask before buying a Florida condo, or contact Hunt Brothers Realty to discuss current condominium opportunities.
Informational notice: This article provides general real estate and condominium information for educational purposes and is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction or other professional advice. Condominium laws, association finances, reserves, assessments, inspection requirements, insurance, financing and building conditions are property-specific and can change. Buyers should verify current information for the condominium they are considering and consult the appropriate Florida real estate attorney, CPA or financial professional, insurance agent, lender, licensed inspector, engineer and other qualified professionals before making a purchasing decision.
Sources
- Florida Department of Business and Professional Regulation, Condominium Inspections and Structural Integrity Reserve Studies
- Florida DBPR, Condominium and Cooperative FAQs
- Florida DBPR, Structural Integrity Reserve Study Reserve Threshold
- Florida DBPR, SIRS Reporting and Database
- Florida Department of Financial Services, Homeowners and Condominium Unit-Owner Insurance Overview
- Hunt Brothers Realty, What to Know Before Buying a Florida Condo
- Hunt Brothers Realty, Florida Condo Reserves Explained
- Hunt Brothers Realty, Florida Condo Special Assessments
- Hunt Brothers Realty, How to Read Florida Condo Documents Before Buying
Hunt Brothers Realty
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2473
- Anna Maria Island 88
- Bird Key 4
- Bradenton 239
- Buying a Home 1510
- Casey Key 2
- Clearwater 14
- Condos & HOA Living 1434
- Ellenton 6
- Englewood 13
- First Time Homebuyers 1625
- Foreclosures 4
- Home Selling 7
- Homeownership 1659
- Lakewood Ranch 29
- Lido Key 29
- Longboat Key 80
- Luxury/Waterfront Properties 1601
- Market Updates & Trends 1109
- Mortgages & Financing 73
- Move-Up Buyers 24
- Neighborhood Guides 1232
- New Construction 42
- Palmetto 4
- Parrish 19
- Port Charlotte 36
- Punta Gorda 164
- Real Estate Investing 1514
- Relocation to Florida 1547
- Safety Harbor 4
- Sarasota 109
- Sarasota - Downtown 168
- Selling a Home 146
- Siesta Key 93
- St. Petersburg 9
- Taxes and Homestead 3
- Tierra Verde 7
- Vacation & Second Homes 1707
- Venice 215
- Wellen Park 22
Recent Posts