Buying a Condo in Florida in 2026: 12 Questions to Ask Before You Make an Offer
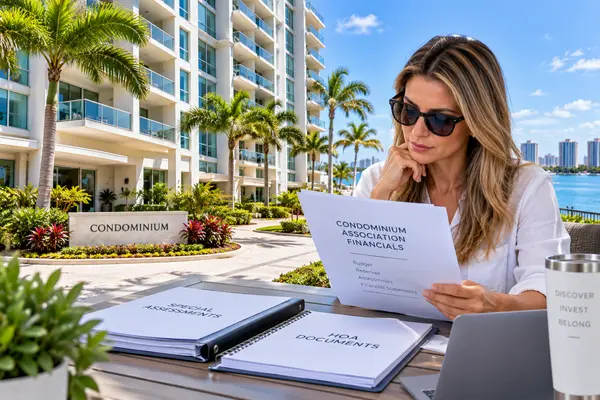
Buying a condo in Florida in 2026 requires investigating more than the unit, view and monthly association fee. Before making an offer, buyers should understand the condominium association's finances, reserves, special assessments, insurance, major building projects, applicable milestone inspections and Structural Integrity Reserve Study information, along with rental, pet, parking and renovation rules. Financing can also depend on the condominium project, not just the buyer's personal qualifications. The goal is to understand both the residence you are buying and the association you will be joining.
Quick Answers About Buying a Condo in Florida in 2026
What is the biggest mistake Florida condo buyers can make?
One major mistake is evaluating only the individual unit. Condo ownership also involves shared financial obligations, association rules, insurance responsibilities and common building components. A beautiful residence can still require substantial due diligence at the association and building level.
Should I worry about a Florida condo with a special assessment?
A special assessment is a reason to investigate, not automatically a reason to reject a condominium. Determine what the assessment funds, its status, the amount allocated to the unit, who is responsible for payment under the transaction, whether the project cost is settled and whether other major expenses may follow.
What is a Structural Integrity Reserve Study?
A Structural Integrity Reserve Study, commonly called a SIRS, addresses specified condominium property, estimated remaining useful life, replacement or deferred-maintenance costs and recommended reserve funding for applicable components. Whether SIRS requirements apply depends on the condominium and current Florida law.
Is a milestone inspection the same as a SIRS?
No. They address different issues. A milestone inspection focuses on the structural condition of applicable condominium and cooperative buildings, while a SIRS focuses on specified components and reserve funding. Buyers should review both when they apply to the building.
Does a low condo fee mean the association is financially healthy?
Not necessarily. The better question is what the assessment covers, whether the association is meeting its operating obligations, how reserves compare with anticipated projects and whether additional assessments or major capital expenses are expected. A higher fee can sometimes reflect broader services or greater reserve contributions.
Does the condo association's insurance cover everything?
No. Association insurance and individual unit-owner insurance address different exposures. Buyers should investigate the master policy, deductibles, flood and wind considerations, and the individual HO-6 coverage appropriate for the specific residence.
Can a condo association affect whether I get a mortgage?
Yes. Condo financing can involve review of the project as well as the borrower. Depending on the loan program and property, association insurance, finances, litigation, structural conditions, owner delinquencies and other project characteristics may affect financing. Buyers should involve their lender early.
1. What Exactly Does the Condo Fee Cover?
Start with the monthly, quarterly or annual assessment, but do not stop at the number shown in the listing. Florida condominium assessments can support building maintenance, landscaping, amenities, management, common-area utilities, insurance, reserves and other association responsibilities.
Different condominiums include different services. Water, sewer, cable, internet, security, concierge services or other expenses may be included in one community and paid separately in another.
Hunt Brothers Realty's guide to what Florida condo fees usually include explains why buyers should compare what an assessment actually pays for rather than ranking buildings solely by the monthly amount.
Before making an offer, ask:
- What is the current regular assessment?
- How often is it paid?
- What services and expenses are included?
- How has the assessment changed in recent years?
- Has the board discussed another increase?
2. How Financially Healthy Is the Condo Association?
When you purchase a condominium, you become part of an association responsible for maintaining and paying for common property. Depending on the community, that can involve roofs, structural systems, elevators, waterproofing, exterior walls, pools, parking structures, plumbing, electrical systems and other shared components.
Review the current budget, recent financial statements, reserve information and other available financial records. Hunt Brothers Realty's guide to evaluating a condo association's financial health explains why buyers should look beyond the current bank balance.
Issues that can justify further investigation include:
- Recurring operating deficits
- Repeated special assessments for predictable maintenance
- Major projects without a clearly understood funding plan
- Substantial association debt
- Significant owner delinquencies reflected in available financial information
- Large insurance deductibles or unresolved insurance issues
- Material expenses discussed in meeting minutes but not clearly reflected in the current budget
These are reasons for additional due diligence, not automatic conclusions about an association. Complex financial or accounting questions should be reviewed with a qualified CPA or other appropriate financial professional.
3. What Do the Reserves and SIRS Tell You?
Reserve information helps buyers understand how an association is preparing for major repair and replacement obligations. This can be especially important in established Florida buildings with roofs, elevators, structural components, waterproofing and other expensive common systems.
Florida condominium reserve requirements have changed substantially in recent years. For condominiums subject to Structural Integrity Reserve Study requirements, the SIRS addresses specified components, their estimated remaining useful lives, estimated replacement or deferred-maintenance costs and recommended reserve funding.
Do not simply ask whether the building "has reserves." Ask how the available funding compares with the association's documented obligations and anticipated projects.
Investigate:
- Current reserve balances
- Current reserve contributions
- The most recent applicable SIRS
- Estimated remaining useful lives of major components
- Estimated repair and replacement costs
- Projects already completed
- Projects anticipated in coming years
- How the association expects to fund those projects
Reserve studies combine technical and financial information. Findings that could materially affect a purchase should be reviewed with the appropriate engineer, inspector, CPA, attorney or other qualified professional.
4. Has the Building Completed Any Required Milestone Inspection?
Florida has milestone inspection requirements for certain condominium and cooperative buildings. Applicability depends on factors established under current Florida law, so buyers should determine whether the building is subject to those requirements and, if so, obtain the applicable inspection information.
A milestone inspection and a SIRS are not interchangeable. The milestone process addresses structural condition, while the reserve study addresses specified components and funding needs.
If milestone inspection information exists, investigate:
- Whether the required inspection has been completed
- The applicable inspection summary and reports
- Any structural findings requiring further evaluation
- Repairs recommended or required
- Whether repair work is completed, underway or planned
- How the association expects to pay for the work
Structural reports should be interpreted by an appropriately qualified engineer or other licensed professional when their findings could affect your purchasing decision. A real estate listing summary is not a substitute for the underlying documents.
5. Are There Current, Pending or Proposed Special Assessments?
A special assessment can materially affect the economics of a condo purchase. Ask about assessments that are already approved, currently being collected, proposed or actively discussed.
If an assessment exists, Hunt Brothers Realty's guide to buying a condo with a pending special assessment recommends determining exactly what "pending" means and reviewing the assessment in the context of reserves, insurance, engineering information and other planned projects.
Ask:
- What is the assessment for?
- Is it proposed, noticed, approved or already being collected?
- What amount is allocated to this unit?
- What has the seller already paid?
- What balance remains?
- Is the project cost fixed or still estimated?
- Could additional work or assessments follow?
Who is legally or contractually responsible for an assessment can depend on the purchase contract, association documents, assessment status and transaction circumstances. Have legal questions reviewed by a qualified Florida real estate attorney rather than relying on a general rule.
6. What Major Repairs or Capital Projects Are Coming?
The absence of a current special assessment does not mean there are no major expenses ahead. Review recent board and association meeting minutes, budgets, reserve information, engineering documents and project discussions for evidence of anticipated capital work.
Depending on the building, significant projects can involve:
- Roof replacement
- Concrete restoration
- Waterproofing
- Elevators
- Plumbing or electrical systems
- Windows or exterior doors when they are an association responsibility
- Balconies and exterior components
- Parking structures
- Pools and other major amenities
A major project is not automatically negative. Recently completed and properly funded work can be valuable. The important questions are what has been completed, what remains, what it cost, how it was funded and what other projects are anticipated.
7. What Does the Association's Insurance Cover?
Florida condo buyers should investigate both association-level insurance and the coverage they may need individually. The shorthand that the association covers "outside the walls" and the owner covers "inside the walls" can oversimplify the actual allocation of insurance responsibilities.
Hunt Brothers Realty's guide to condo association insurance versus HO-6 insurance in Florida explains why buyers should examine the two layers together.
Before making a purchasing decision, investigate:
- Current association master insurance
- Applicable deductibles
- Wind coverage
- Flood considerations
- Unit-owner insurance responsibilities
- HO-6 coverage availability and premium
- Loss assessment coverage and its limitations
Do not assume that loss assessment coverage will pay every special assessment. Coverage depends on the policy terms, covered cause of loss, limits, exclusions and circumstances. Obtain a property-specific quote and have a qualified insurance professional review both the association's coverage and your individual insurance needs.
8. Will the Condominium Qualify for Your Financing?
Mortgage preapproval does not necessarily mean every condominium project will satisfy a lender's requirements. Condo financing can involve underwriting both the borrower and the project.
Depending on the loan program and circumstances, a lender may review association finances, insurance, litigation, owner delinquencies, structural conditions, assessments and other project characteristics.
If you are financing, identify the condominium early and ask your lender whether the project presents any known eligibility or documentation issues. Loan requirements vary, so financing questions should be confirmed directly with a qualified mortgage lender or loan professional.
9. What Are the Rental Rules?
Never assume you can rent a Florida condo simply because other units in the building appear to be rentals. Rental restrictions vary significantly among associations and can affect investors, seasonal owners and buyers who simply want flexibility in the future.
Verify current rules concerning:
- Minimum lease period
- Maximum number of leases per year
- Whether ownership for a minimum period is required before leasing
- Tenant application or approval procedures
- Rental-related fees
- Occupancy restrictions
- Short-term rental restrictions
Buyers intending to rent should also investigate applicable municipal, county and state requirements rather than assuming association permission alone establishes that a particular rental use is allowed.
10. What Pet, Parking, Storage and Renovation Rules Apply?
Rules that seem secondary during a showing can become important after closing. Read the current declaration, bylaws and rules rather than relying solely on a listing description or verbal summary.
Verify issues important to your intended use, including:
- Number and size of permitted pets
- Other applicable pet restrictions
- Assigned, deeded or limited-common-element parking
- Guest parking
- Storage rights
- Vehicle restrictions
- Balcony rules
- Flooring requirements
- Renovation approval procedures
- Contractor and construction-hour requirements
If you are buying with plans for a substantial renovation, verify association approval requirements and applicable permitting before assuming your planned changes are feasible.
11. What Do the Condo Documents and Meeting Minutes Reveal?
The condominium documents can reveal financial obligations, restrictions, planned projects and building-level issues that are not visible during a showing. Hunt Brothers Realty's Florida condo document checklist provides a detailed starting point.
Depending on the condominium and transaction, review materials such as:
- Declaration of condominium and amendments
- Articles of incorporation
- Bylaws
- Current rules
- Current annual budget
- Recent financial statements
- Reserve information
- Applicable SIRS information
- Applicable milestone inspection information
- Recent board and association meeting minutes
- Current and proposed special assessments
- Association insurance information
- Documentation concerning major completed and planned projects
Meeting minutes deserve particular attention because they may show recurring discussions about repairs, insurance, assessments, owner delinquencies, litigation, maintenance or capital projects that deserve further investigation.
Condominium documents create legal rights and obligations. Buyers who need interpretation of the declaration, bylaws, assessments, ownership rights, contract provisions or other legal matters should consult a qualified Florida real estate attorney.
12. What Is the True Cost of Owning This Condo?
The purchase price is only one part of condominium ownership. Before making an offer, build a realistic picture of recurring and known near-term costs for the specific residence.
Depending on the property, investigate:
- Mortgage principal and interest, if financed
- Property taxes
- Regular condominium assessments
- Current special assessments
- Individual HO-6 insurance
- Flood insurance when applicable or selected
- Utilities not included in the association fee
- Parking or storage expenses when applicable
- Known renovation or repair expenses
- Potential near-term association expenses identified during due diligence
Taxes, insurance and financing costs depend on the buyer and property. Obtain property-specific estimates from the appropriate lender, insurance professional, tax professional and other qualified professionals rather than assuming the seller's current expenses will transfer unchanged.
Should You Ask These Questions Before or After Making an Offer?
Investigate as much material information as reasonably available before making an offer, particularly information that could change what you are willing to pay or whether the condominium fits your plans. Additional documents and formal disclosures may become available during the transaction, depending on the property and circumstances.
Your purchase contract also matters. Review applicable document-review, inspection, financing and other deadlines with your licensed real estate professional. Questions about cancellation rights, statutory review periods, contract interpretation or legal obligations should be addressed by a qualified Florida real estate attorney.
Does an Older Florida Condo Automatically Mean More Risk?
No. Building age is one piece of the analysis, not a verdict. An established building may have completed substantial restoration, roof replacement, mechanical improvements and other capital work while maintaining appropriate reserves. A newer building can still have insurance, construction, financial or association issues that require investigation.
Compare actual condition, maintenance history, completed projects, reserves, inspection findings, insurance and association finances rather than relying on age alone.
What Should Sarasota Condo Buyers Investigate?
For buyers considering Downtown Sarasota condominiums, barrier-island properties or other Gulf Coast buildings, association due diligence should be combined with location-specific questions.
Coastal buyers may also need to investigate flood exposure, evacuation considerations, wind protection, building elevation, insurance and storm-related repair history. Hunt Brothers Realty's guide to questions to ask before buying near the Florida coast provides a broader framework for these issues.
Buyers focused specifically on the urban core can also review Hunt Brothers Realty's guide to Downtown Sarasota condo living, including the tradeoffs involving amenities, fees, shared ownership responsibilities, parking and building rules.
Florida Condo Buyer Checklist for 2026
Before making a final purchasing decision, confirm that you have investigated the issues relevant to the specific condominium:
- Current condo fee and exactly what it covers
- Association budget and recent financial statements
- Reserve balances and current reserve contributions
- Applicable Structural Integrity Reserve Study information
- Applicable milestone inspection information
- Current, pending and discussed special assessments
- Major completed and planned building projects
- Association insurance and deductibles
- Property-specific HO-6 and flood insurance considerations
- Financing eligibility for the condominium project
- Rental and leasing restrictions
- Pet rules
- Parking and storage rights
- Renovation restrictions
- Recent association and board meeting minutes
- Unit inspection and renovation history when relevant
- The complete estimated ownership cost
The Bottom Line for Florida Condo Buyers in 2026
The best condo due diligence looks in two directions at once: inside the residence and beyond its front door. Inspect the individual unit, but also investigate the association responsible for the building and common property.
The current fee alone cannot tell you whether a condominium is financially well positioned. A special assessment alone cannot tell you whether it is poorly managed. Building age alone cannot tell you whether it is structurally problematic. The useful answers come from current documents, inspection information, reserve planning, financial records, insurance, project history and qualified professional review.
The more you understand before making an offer, the better you can evaluate the residence as a complete ownership opportunity rather than simply comparing square footage, finishes and views.
Buying a Florida Condo? Investigate the Building as Carefully as the Unit
Hunt Brothers Realty helps buyers evaluate Florida Gulf Coast condominiums as complete ownership opportunities. That means comparing the residence, location and amenities while also identifying association finances, assessments, reserves, insurance, building projects, restrictions and available structural information that deserve investigation.
Buyers considering Sarasota can explore Sarasota-area communities with Hunt Brothers Realty and use the firm's condo document review guide as a starting point for property-specific due diligence.
This article provides general real estate information for educational purposes and is not individualized legal, financial, tax, insurance, lending, accounting, inspection, engineering, construction, association or other professional advice. Florida condominium requirements and individual building circumstances vary. Buyers should review current association documents and have legal matters addressed by a qualified Florida real estate attorney, structural matters by an appropriate engineer or licensed professional, financial and accounting matters by a qualified CPA or financial professional, insurance questions by a qualified insurance professional, financing questions by their mortgage lender, and property condition by appropriate licensed inspectors and other qualified professionals before making a purchasing decision.
Sources
- Florida Legislature, 2026 Florida Statutes, Chapter 718, Condominiums
- Hunt Brothers Realty, What Condo Documents Should Buyers Review Before Closing?
- Hunt Brothers Realty, How to Tell If a Condo Association Is Financially Healthy
- Hunt Brothers Realty, Should I Buy a Condo With a Pending Special Assessment?
- Hunt Brothers Realty, Condo Association Insurance vs. HO-6 Insurance in Florida
- Hunt Brothers Realty, What Does a Condo Fee Usually Include in Florida?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1506
- Anna Maria Island 68
- Bird Key 3
- Bradenton 92
- Buying a Home 651
- Casey Key 2
- Clearwater 5
- Condos & HOA Living 556
- Ellenton 4
- Englewood 5
- First Time Homebuyers 728
- Foreclosures 3
- Homeownership 709
- Lakewood Ranch 15
- Lido Key 24
- Longboat Key 65
- Luxury/Waterfront Properties 646
- Market Updates & Trends 317
- Mortgages & Financing 32
- Move-Up Buyers 20
- Neighborhood Guides 470
- New Construction 24
- Palmetto 2
- Parrish 4
- Port Charlotte 7
- Punta Gorda 11
- Real Estate Investing 580
- Relocation to Florida 630
- Safety Harbor 2
- Sarasota - Downtown 132
- Selling a Home 136
- Siesta Key 87
- St. Petersburg 3
- Tierra Verde 4
- Vacation & Second Homes 763
- Venice 21
- Wellen Park 7
Recent Posts