What Sellers Should Know About Offers
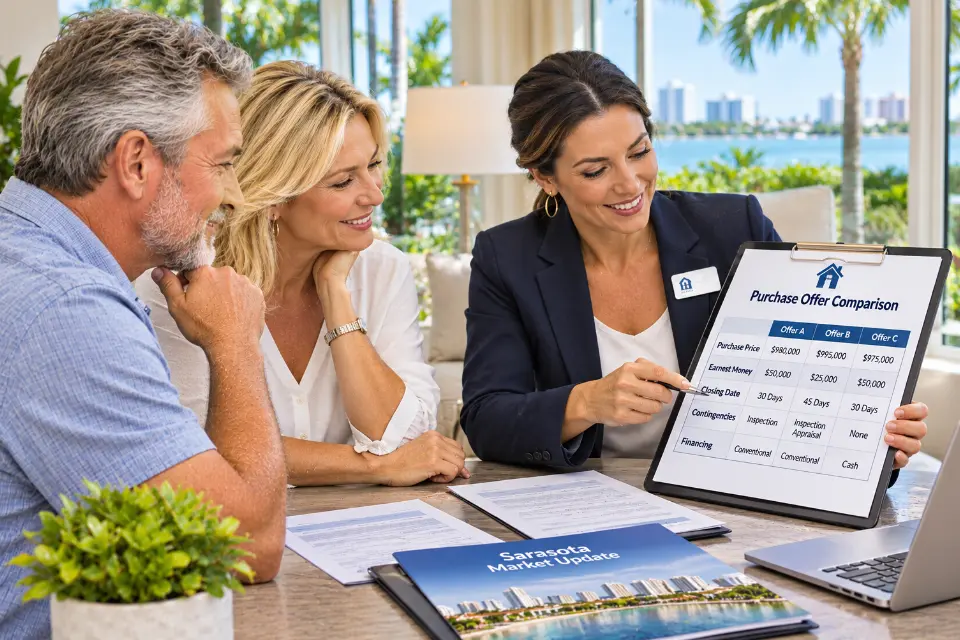
When an offer arrives on a Sarasota home, the purchase price is only the beginning of the evaluation. Sellers should also review financing, deposits, contingencies, inspection provisions, appraisal terms, requested concessions, closing timing and other contract terms. The strongest offer is not automatically the one with the highest price. A useful comparison asks what the seller may receive, what conditions must be satisfied before closing, how the proposed timeline fits the seller's plans, and what uncertainties are built into each offer.
Quick Answers About What Sellers Should Know About Offers
Should a seller always accept the highest offer?
No. Price matters, but financing, contingencies, deposits, concessions, inspection provisions and closing timing can make two similarly priced offers substantially different. Sellers should compare the complete terms.
Does a seller have to accept a full-price offer?
Florida Realtors notes that a seller is not required to accept an offer simply because it meets the asking price. Price is only one component of a proposed contract, and the seller can consider the complete terms before deciding how to respond.
What are the seller's basic choices when an offer arrives?
Depending on the circumstances, a seller may accept an offer, reject it, make a counteroffer or continue evaluating other offers. The legal effect of any response depends on the actual contract and communications, so sellers should understand the consequences before acting.
Is a cash offer automatically better than a financed offer?
No. Cash can remove mortgage-related uncertainty, but price, proof of funds, deposits, contingencies, inspection terms, closing date and other conditions still matter. A financed offer can sometimes provide a seller with a more favorable overall proposal.
What is an earnest money deposit?
An earnest money deposit is money provided under the purchase agreement and held according to the contract's escrow provisions. Sellers should review the amount, timing and contractual terms rather than assuming a larger deposit automatically eliminates other transaction risks.
What are seller concessions?
Seller concessions are negotiated amounts or costs the seller agrees to cover for the buyer as part of the transaction. Sellers should consider concessions when comparing the economics of competing offers because the headline purchase price does not show the complete financial picture.
Can a seller accept another offer after already signing a contract?
A signed purchase agreement can create binding contractual obligations. A seller who later receives another offer should not assume the existing agreement can simply be canceled. Questions about termination rights, defaults, backup offers or another proposed transaction should be reviewed with the seller's real estate professional and a qualified Florida real estate attorney when legal advice is needed.
Why Isn't the Highest Offer Automatically the Best Offer?
The highest offer may be the best offer, but sellers should not know that from price alone. The National Association of Realtors' guide to navigating multiple offers explains that financial terms, contingencies, closing timelines and earnest money deposits can make offers more or less attractive to an individual seller.
Consider two hypothetical offers. One buyer offers more but requests a significant seller concession, includes financing and appraisal conditions, and proposes a closing date that creates a problem for the seller. Another buyer offers somewhat less but proposes terms that better match the seller's timing and financial priorities.
The point is not that lower offers are inherently stronger. It is that sellers should compare the entire proposal before deciding which offer best fits their objectives.
What Should a Seller Review in Every Offer?
A seller should review every material term that could affect the economics, timing or likelihood of completing the proposed transaction. The exact provisions depend on the contract being used, but several categories commonly deserve attention.
- Purchase price
- Cash or financing terms
- Earnest money or escrow deposits
- Deposit deadlines
- Financing provisions
- Inspection provisions and deadlines
- Appraisal-related terms when applicable
- Requested seller concessions or credits
- Closing date
- Possession arrangements
- Personal property requested with the sale
- Sale-of-property or other contingencies when included
- Additional riders, addenda or special terms
Sellers should read the actual proposed agreement rather than relying solely on a verbal summary. Contract forms and negotiated provisions can differ, and small differences in language can have important consequences.
How Should Sellers Evaluate a Buyer's Financing?
Financing matters because a financed buyer generally depends on a lender to complete the purchase. Sellers can review the financing terms included in the offer along with available documentation about the buyer's financing preparation.
A preapproval letter can provide useful information, but it is not final loan approval. Underwriting, borrower documentation, the property, appraisal, insurance and other lending conditions can still affect financing after a contract is signed.
Sellers should also distinguish the type of financing from the complete strength of the offer. Conventional, FHA, VA and other financing structures can have different requirements, but sellers should evaluate actual proposed terms rather than making assumptions about a buyer based solely on a loan label.
How Should Sellers Evaluate a Cash Offer?
A cash offer can remove mortgage financing from the transaction, but sellers should still evaluate the buyer's ability to complete the purchase and every other proposed contract term. Cash does not automatically remove inspection provisions, title issues, association requirements or other contingencies that may be included in the agreement.
Proof of funds can help document that the buyer has resources available for the proposed purchase. Sellers should work with their real estate professional and closing professionals to determine what transaction-specific documentation is appropriate.
A seller comparing cash with financing should therefore consider the difference in price along with deposits, contingencies, closing timing, requested concessions and the other terms that affect the complete proposal.
Why Does the Earnest Money Deposit Matter?
The deposit is one component of an offer that sellers can compare, but its meaning depends on the contract. The amount, deadline, escrow arrangements and circumstances under which funds may be returned, released or disputed are governed by the applicable agreement and law.
A larger deposit may look appealing, but sellers should not treat it as a guarantee that the transaction will close or assume they automatically receive the money if the transaction does not close. Contractual rights involving escrow deposits can be fact-specific.
Questions about entitlement to a deposit, default, escrow disputes or release of funds can involve legal issues and should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional when individualized advice is required.
How Do Contingencies Affect an Offer?
Contingencies and contractual conditions can affect what must happen before a transaction reaches closing and, depending on the agreement, when a party may have particular rights or options. Sellers should understand each proposed provision rather than simply counting how many contingencies appear in an offer.
Hunt Brothers Realty's guide to contingencies in Florida home offers explains that financing, deposits, inspection provisions, appraisal exposure, concessions, closing dates and other terms can influence how sellers compare offers.
Fewer contingencies do not automatically make an offer better for every seller. The significance depends on the specific language, the buyer's circumstances, the property and the seller's own priorities.
What Should Sellers Know About Inspection Terms?
Inspection terms can affect both the transaction timeline and the parties' rights after the contract is signed. Sellers should review the inspection provisions in the actual proposed contract, including applicable deadlines and any negotiated modifications.
An inspection provision does not necessarily mean the seller has agreed in advance to repair everything an inspector identifies. What the buyer and seller may request, negotiate or do after an inspection depends on the contract.
Technical inspection findings should be evaluated with the appropriate licensed inspector, contractor, engineer or qualified tradesperson. Questions about contractual inspection rights or obligations should be reviewed with a qualified Florida real estate attorney when legal interpretation is needed.
What Should Sellers Know About Appraisal Terms?
An appraisal can become important when a buyer is financing the purchase, but sellers should not assume every contract handles appraisal risk in the same way. The specific contract language determines what appraisal-related rights or obligations may exist between buyer and seller.
Florida Realtors' Florida real estate contract guidance specifically cautions that an appraisal-to-purchase-price contingency is not automatically built into every core contract form. That is one reason sellers should review the actual form and riders being proposed rather than assuming an appraisal creates a universal cancellation right.
An appraisal is also different from a comparative market analysis prepared for listing purposes. When questions involve a formal appraisal or valuation, the appropriate licensed or certified appraiser should address appraisal-specific matters.
How Do Seller Concessions Change the Economics of an Offer?
Seller concessions can reduce certain costs for a buyer while also affecting the seller's estimated proceeds. That means sellers should compare an offer's purchase price together with the concessions or credits being requested.
The National Association of Realtors notes that concessions may involve costs associated with the transaction, repairs or other negotiated expenses. Agreed concessions should be documented in the purchase agreement.
When financing is involved, lender and loan-program rules can affect permissible concessions. Buyers and sellers should rely on the applicable lender or loan professional for financing-specific requirements rather than assuming that every requested concession can be structured in the same way.
Why Can the Closing Date Matter as Much as Price?
Closing timing can have real value to a seller because it affects moving plans, another home purchase, temporary housing and other logistics. A higher offer with an inconvenient timeline may not necessarily serve a seller's priorities as well as another proposal.
Sellers should also distinguish the proposed closing date from certainty that closing will occur on that date. Financing, title, association requirements and other contract matters can affect a transaction before closing.
If the seller needs possession after closing or another unusual timing arrangement, the terms should be properly documented. Such arrangements can create insurance, liability, possession and legal considerations that deserve property-specific professional review.
How Should Sellers Compare Estimated Net Proceeds?
Sellers should compare what an offer may mean financially after considering more than the contract price. Requested concessions, negotiated credits, transaction expenses, mortgage payoffs, taxes, association-related amounts and other adjustments can affect estimated net proceeds.
For example, a higher purchase price accompanied by a larger seller concession may produce a different financial result than the headline price initially suggests. A seller's real estate and closing professionals can help organize transaction-specific estimates as the proposed terms become known.
Estimated proceeds should not be confused with tax consequences. Capital gains and other tax questions depend on the individual owner and property, so sellers should consult a qualified tax professional or CPA regarding their specific circumstances.
What Is a Counteroffer?
A counteroffer proposes different terms rather than simply accepting the offer as written. A seller might counter price, closing date, concessions or another contract provision.
Counteroffers have legal consequences. Florida Realtors' contract guidance explains that a counteroffer operates as a rejection of the initial offer, meaning sellers should not assume they can counter and still preserve an unconditional right to return to the original proposal later.
Sellers considering counteroffers, particularly in a multiple-offer situation, should understand exactly what is being proposed and the legal effect of the response. Questions about contract formation, withdrawal, acceptance or competing counteroffers should be reviewed with a qualified Florida real estate attorney when individualized legal advice is needed.
What Happens When a Seller Receives Multiple Offers?
Multiple offers give the seller choices, but they also make careful comparison more important. Florida Realtors explains that sellers may have several potential response strategies depending on the circumstances, including accepting an offer, countering an offer or asking buyers for revised proposals.
The seller does not have to select an offer simply because it arrived first. Florida Realtors' seller's guide to navigating multiple offers emphasizes comparing price with closing timing, financing and other terms.
Negotiating several offers can become complicated quickly. Sellers should work with their real estate professional to understand available real estate strategies and obtain legal guidance when questions involve contractual rights, disclosure of offer terms, competing counteroffers or other legal consequences.
Should Sellers Automatically Ask for Highest and Best?
Not necessarily. Asking buyers to submit their strongest terms is one possible multiple-offer strategy, but it is not automatically the right response to every situation. A seller may already have an offer that satisfies the seller's objectives, or another negotiation strategy may be more appropriate.
Inviting revised offers may produce stronger proposals, but buyers can also choose not to change their terms or may pursue another property. No negotiation strategy guarantees a better result.
The appropriate approach depends on the offers already received, seller priorities, current competition and timing. Sellers should avoid treating a multiple-offer strategy as an automatic formula.
Can Sellers Disclose That Other Offers Exist?
The handling and disclosure of competing offers can involve brokerage duties, seller instructions and legal or ethical requirements. Sellers should discuss the strategy with their real estate professional rather than assuming that the existence or terms of competing offers will automatically be disclosed.
Florida Realtors notes that multiple-offer situations can involve decisions about whether to disclose competing offers, request revised offers or negotiate with particular buyers. The appropriate process should be handled in accordance with applicable law, brokerage obligations and the seller's lawful instructions.
Questions about confidentiality, disclosure of specific offer terms or legal duties should be reviewed with the appropriate real estate and legal professionals before a seller adopts a negotiation strategy.
Can a Seller Change Their Mind After Accepting an Offer?
Sellers should not assume they can simply change their mind after entering a binding purchase agreement. The National Association of Realtors cautions that sellers generally have less flexibility than buyers to exit a signed agreement and that attempting to do so can create legal issues.
Whether a seller has a contractual basis to terminate depends on the agreement and circumstances. A later, higher offer does not by itself establish a right to cancel an existing contract.
A seller considering termination, a backup offer or any action that could conflict with an existing agreement should obtain individualized guidance from a qualified Florida real estate attorney before acting.
What Questions Should a Sarasota Seller Ask Before Accepting an Offer?
Before accepting an offer, a seller should understand both what the buyer is proposing and how those terms fit the seller's priorities. A structured review can make the comparison more useful than focusing on one headline number.
- What is the purchase price?
- Is the buyer paying cash or using financing?
- What financing terms are included?
- What deposits are proposed, and when are they due?
- What inspection provisions and deadlines apply?
- What appraisal-related provisions apply?
- Is the buyer requesting seller concessions or credits?
- Are there other contingencies?
- What closing date is proposed?
- Does the timing fit the seller's next move?
- Is personal property included or requested?
- What additional riders or special terms are attached?
- What are the estimated financial effects of the proposed terms?
- Are there any provisions the seller does not fully understand?
If the final question is yes, the seller should obtain clarification before signing. Once an offer becomes a contract, the parties' rights and obligations are governed by that agreement and applicable law.
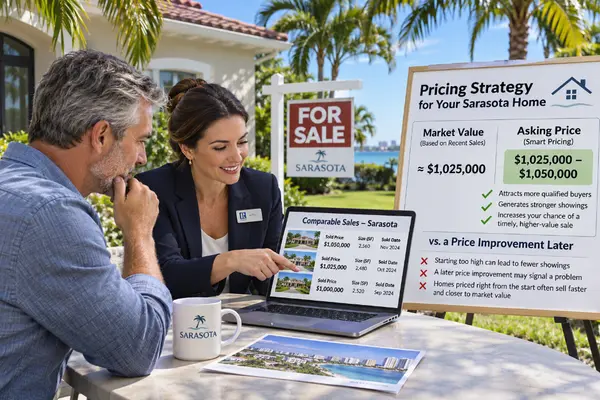
How Does Pricing Strategy Affect the Offers a Seller Receives?
Pricing and offer evaluation are connected because the original market position influences which buyers consider the property and how they may structure proposals. An asking price should be supported by current comparable sales, competing inventory, condition, location and other property-specific evidence.
A seller receiving an offer below the asking price should not automatically interpret it as an unusable proposal. The National Association of Realtors' pricing guide notes that an offer below list price can sometimes still be attractive depending on cash terms, contingencies and other factors.
Hunt Brothers Realty's guide to common Sarasota home-selling mistakes similarly recommends comparing financing, deposits, inspection provisions, appraisal exposure, concessions, contingencies and closing dates instead of assuming the highest price is automatically the best proposal.
The Best Offer Is the One That Best Fits the Seller's Priorities
There is no universal formula for identifying the best offer. One seller may prioritize the highest estimated proceeds. Another may place greater value on a particular closing date. Another may prefer terms that reduce certain transaction uncertainties.
The useful comparison is therefore not simply offer price versus offer price. It is price, financing, deposits, contingencies, concessions, inspections, appraisal terms, timing and other provisions evaluated together against the seller's objectives.
Once the seller understands that complete picture, an offer becomes easier to evaluate as a proposed transaction rather than merely a number.
Review Your Sarasota Home Offers With Hunt Brothers Realty
Hunt Brothers Realty helps Sarasota-area sellers understand the real estate components of purchase offers and compare proposed terms with their selling priorities. If you are preparing to sell, review Hunt Brothers Realty's guide to common mistakes Sarasota home sellers should avoid, learn how contingencies can affect a Florida offer, visit Hunt Brothers Realty, or contact Hunt Brothers Realty to discuss your selling plans.
Informational notice: This article provides general real estate information for educational purposes and is not individualized legal, financial, tax, lending, appraisal, inspection, title or other professional advice. Purchase contracts, contingencies, deposits, counteroffers, concessions, financing provisions, appraisal terms, termination rights and other obligations depend on the actual agreement and circumstances. Sellers should work with a licensed real estate professional for property-specific real estate guidance. Questions involving contractual rights, legal obligations, default, cancellation, escrow disputes or interpretation of contract language should be reviewed with a qualified Florida real estate attorney. Financing and appraisal questions should be reviewed with the appropriate qualified lender or licensed appraiser when individualized guidance is required.
Sources
- National Association of Realtors, Consumer Guide: Navigating Multiple Offers
- National Association of Realtors, Consumer Guide: What Goes Into Pricing Your Home
- Florida Realtors, Seller's Guide to Navigating Multiple Offers
- Florida Realtors, Florida Real Estate Contract Laws
- Hunt Brothers Realty, Common Mistakes Sarasota Home Sellers Should Avoid
- Hunt Brothers Realty, What Contingencies Should I Include in a Home Offer?
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2654
- Anna Maria Island 92
- Bird Key 5
- Bradenton 242
- Buying a Home 1675
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1603
- Ellenton 8
- Englewood 15
- First Time Homebuyers 1795
- Foreclosures 4
- Home Selling 10
- Homeownership 1840
- Lakewood Ranch 36
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1781
- Market Updates & Trends 1283
- Mortgages & Financing 85
- Move-Up Buyers 24
- Neighborhood Guides 1410
- New Construction 46
- Palmetto 4
- Parrish 38
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1694
- Relocation to Florida 1722
- Safety Harbor 4
- Sarasota 157
- Sarasota - Downtown 175
- Selling a Home 149
- Siesta Key 94
- St. Petersburg 11
- Taxes and Homestead 3
- Tierra Verde 7
- Vacation & Second Homes 1888
- Venice 225
- Wellen Park 24
Recent Posts