Can I Buy a House in Florida With 5% Down?
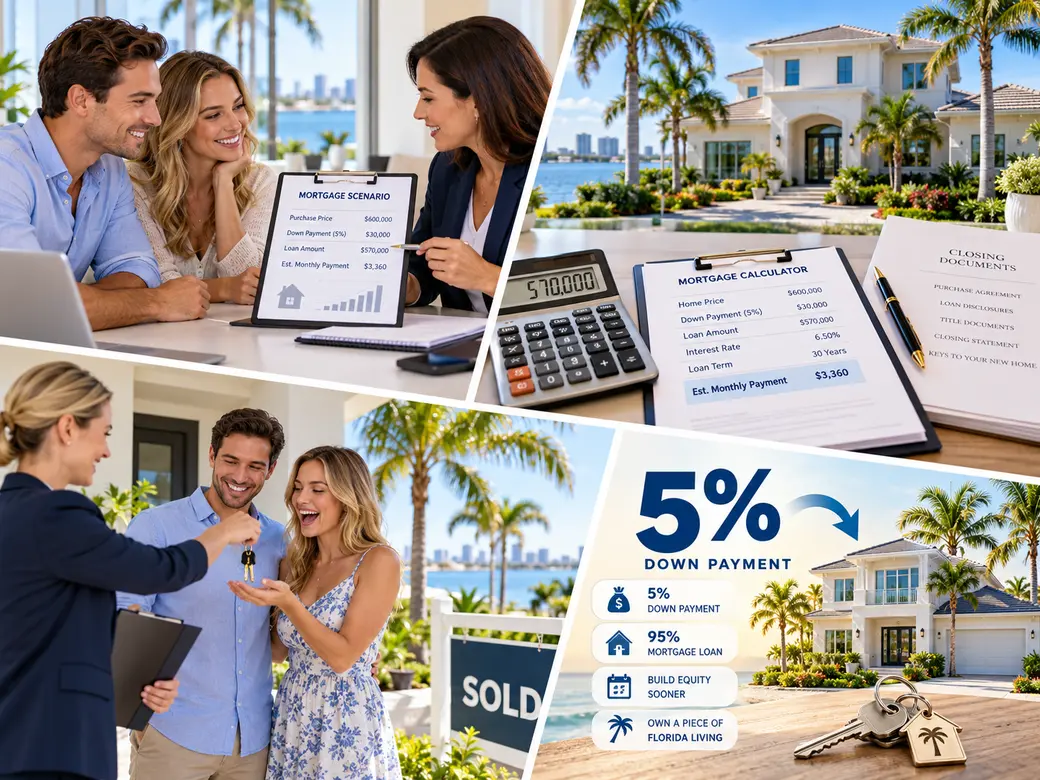
Yes. Many qualified buyers can purchase a primary residence in Florida with a 5% down payment using conventional financing. In fact, some eligible conventional programs can permit even less than 5% down. On a $400,000 home, 5% equals $20,000, while on a $500,000 home it equals $25,000. The down payment is not the buyer's complete cash requirement, however. Closing costs, prepaid insurance, escrow funding, inspections, moving expenses and post-closing savings should also be considered. Eligibility depends on the borrower, mortgage program, lender, occupancy and property, so buyers should have a qualified mortgage professional price the actual loan before making an offer.
Quick Answers About Buying a Florida Home With 5% Down
Can You Really Buy a Florida House With Only 5% Down?
Yes. Current conventional mortgage guidelines can permit qualified buyers to finance 95% of an eligible primary residence, leaving a 5% down payment. Approval still depends on underwriting, credit, income, debts, assets, property eligibility and lender requirements.
Do You Have to Be a First-Time Homebuyer to Put 5% Down?
Not necessarily. Conventional 95% loan-to-value financing is not universally limited to first-time buyers. Particular programs can have additional eligibility requirements, so the lender should determine which 5% down options apply to the borrower.
How Much Is 5% Down on a $400,000 Florida House?
Five percent of $400,000 is $20,000. A simplified 95% mortgage would therefore be $380,000 before considering any financing adjustments. Closing costs and other purchase expenses are separate from the $20,000 down payment.
Will I Have PMI With 5% Down?
With a conventional mortgage beginning at 95% loan-to-value, mortgage insurance will generally be part of the financing structure. The actual private mortgage insurance cost depends on the loan, borrower and insurer. Ask the lender to quote the complete payment and mortgage-insurance terms for the specific financing scenario.
Can I Buy a Florida Condo With 5% Down?
Potentially. Current Fannie Mae rules can permit 95% loan-to-value financing on qualifying Florida condominium units used as principal residences, but the condominium project itself can be subject to additional eligibility and review requirements. Buyer qualification alone does not guarantee that a particular condo project will satisfy mortgage requirements.
Can I Buy a Florida Second Home With 5% Down?
Do not assume so. Fannie Mae's April 2026 standard eligibility matrix generally shows a maximum 90% loan-to-value for qualifying one-unit second-home purchases, which corresponds to at least 10% down under that structure. Other lenders or loan products may differ, so second-home buyers should obtain property-specific financing requirements directly from their lender.
Can I Buy a Florida Investment Property With 5% Down?
A standard 5% down conventional primary-residence structure should not be assumed for an investment property. Fannie Mae's current standard matrix shows a maximum 85% loan-to-value for qualifying one-unit investment-property purchases, which corresponds to 15% down under that framework. Investment financing varies, so buyers should verify current requirements with qualified lenders.
How Does a 5% Down Conventional Mortgage Work?
A 5% down payment means the buyer contributes 5% of the purchase price and, in a simplified example, finances the remaining 95%.
Fannie Mae's current 2026 eligibility matrix permits up to 97% loan-to-value for certain qualifying one-unit principal-residence fixed-rate purchase transactions and up to 95% in additional qualifying conventional scenarios. Freddie Mac also offers qualifying low-down-payment conventional financing.
That means a 95% mortgage with 5% down is well within the range of established conventional financing for many eligible owner-occupied purchases.
It does not mean every applicant will receive a 95% mortgage. Mortgage underwriting evaluates the complete transaction, including the borrower and the property.
How Much Money Is 5% Down?
The calculation is straightforward:
Purchase price × 0.05 = 5% down payment
| Florida Home Price | 5% Down Payment | Illustrative 95% Loan |
|---|---|---|
| $250,000 | $12,500 | $237,500 |
| $300,000 | $15,000 | $285,000 |
| $400,000 | $20,000 | $380,000 |
| $500,000 | $25,000 | $475,000 |
| $600,000 | $30,000 | $570,000 |
| $750,000 | $37,500 | $712,500 |
These are mathematical illustrations only. The loan amount available to a specific buyer depends on underwriting, applicable loan limits, appraisal and other mortgage requirements.
For a broader comparison of 3%, 5%, 10% and 20% down, read Hunt Brothers Realty's guide to choosing a home down payment.
Do You Need to Be a First-Time Buyer for 5% Down?
No universal rule says that every buyer using 5% down must be a first-time homebuyer.
This distinction matters because some of the lowest conventional down-payment programs have additional requirements. For example, Fannie Mae's standard 97% loan-to-value option requires at least one borrower to qualify as a first-time homebuyer, while HomeReady can offer up to 97% financing without a first-time-buyer requirement but applies its own income and program rules.
At 95% loan-to-value, financing options can be broader. A repeat buyer should therefore not assume that owning a previous home prevents a 5% down purchase.
Have a qualified mortgage lender evaluate the exact borrower profile rather than choosing a loan based solely on a general program description.
What Does a Lender Review When You Put 5% Down?
The down payment is only one part of mortgage underwriting. Depending on the loan, lenders can evaluate factors including:
- Income and qualifying employment or income history
- Existing monthly debts
- Credit history and applicable credit scores
- Assets available for closing
- Source of down-payment funds
- Required financial reserves when applicable
- Occupancy as a primary residence, second home or investment property
- Property type
- Appraised value
- Other program and underwriting requirements
There is also no single credit score that guarantees approval for a 5% down Florida mortgage. Current conventional underwriting is more nuanced than a universal score threshold. Hunt Brothers Realty's 2026 Florida credit-score guide explains how current conventional, FHA, VA and USDA standards differ.
Will You Pay PMI With a 5% Down Conventional Loan?
Generally, conventional financing above 80% loan-to-value involves private mortgage insurance, commonly called PMI. A 5% down purchase begins around 95% loan-to-value, so mortgage insurance will ordinarily need to be included in the financing analysis.
PMI is designed to protect the lender against part of the risk associated with a higher loan-to-value mortgage. It does not provide property insurance coverage to the homeowner.
The cost is not one universal percentage. It can vary based on the borrower, loan-to-value, credit profile, loan structure, insurer and other factors.
Mortgage-insurance cancellation rights and requirements depend on the mortgage and applicable law. Buyers should ask their lender to explain the initial premium, monthly cost, cancellation rules and how a larger down payment would change the mortgage-insurance expense.
How Does 5% Down Compare With 20% Down?
The most obvious difference is the amount of cash committed to the purchase.
On a $500,000 Florida home:
| Scenario | Down Payment | Illustrative Loan |
|---|---|---|
| 5% Down | $25,000 | $475,000 |
| 10% Down | $50,000 | $450,000 |
| 20% Down | $100,000 | $400,000 |
Choosing 5% instead of 20% in this example preserves $75,000 of upfront cash, but it also increases the illustrative mortgage balance by $75,000 and would generally introduce conventional mortgage insurance.
Whether preserving that cash is preferable depends on the buyer's actual loan pricing, PMI, monthly-payment target, financial reserves and broader circumstances. A qualified lender or financial professional can help a buyer evaluate those tradeoffs using property-specific numbers.
Does 5% Down Mean You Only Need 5% of the Home Price in Cash?
No. This is one of the most important distinctions for Florida buyers.
The down payment is only one part of the purchase budget. Buyers may also need money for:
- Lender and mortgage charges
- Appraisal and applicable loan services
- Title and settlement expenses
- Recording and applicable Florida mortgage taxes
- Prepaid homeowners insurance
- Flood insurance when applicable
- Initial tax and insurance escrow funding when applicable
- Prepaid mortgage interest
- Home inspections
- Association-related expenses when applicable
- Moving costs
- Immediate repairs or maintenance
- Post-closing savings and reserves
Hunt Brothers Realty's Florida buyer closing-cost guide uses approximately 2% to 5% of the purchase price as a broad preliminary planning range for closing costs, excluding the down payment. It is not a guaranteed average or a quote for a specific transaction.
How Much Cash Might You Need for a $400,000 Home With 5% Down?
Consider a simplified $400,000 purchase:
- Purchase price: $400,000
- 5% down payment: $20,000
- Broad 2% to 5% closing-cost illustration: $8,000 to $20,000
Under those simplified assumptions, the down payment plus the illustrative closing-cost range equals approximately $28,000 to $40,000.
That still does not necessarily represent the buyer's complete savings target. Inspections may be paid before closing, and the buyer may need moving money, immediate repair funds and post-closing reserves.
The actual cash-to-close figure can also be reduced or changed by earnest-money deposits already paid, allowable seller concessions, lender credits, prorations and other transaction adjustments.
Does Your Earnest-Money Deposit Count Toward the Transaction?
Generally, yes, when the transaction closes and the deposit is properly credited. Earnest money is a contractual deposit rather than an additional down-payment percentage.
For example, assume a buyer needs a $20,000 down payment on a $400,000 purchase and previously deposited $10,000 in earnest money. If the transaction closes and that entire deposit is properly credited, the buyer does not simply pay the same $10,000 again as though it had disappeared.
The final amount due will also account for closing costs, prepaid expenses, credits, prorations and other settlement items. Contractual rights concerning deposits, including circumstances in which they may be refundable or at risk, depend on the purchase agreement and applicable law. Buyers with legal questions about deposits should consult a qualified Florida real estate attorney.
Can Seller Concessions Help When You Put 5% Down?
Potentially. Buyers and sellers can negotiate a seller contribution toward certain allowable buyer expenses, subject to the mortgage program and transaction.
A properly structured seller credit may be usable for eligible closing costs, prepaid expenses, discount points or other permitted expenses. This can be particularly useful to a lower-down-payment buyer because it may reduce eligible closing expenses without requiring the buyer to commit additional cash.
The seller must agree, and mortgage programs limit how contributions can be structured and used. A concession generally cannot simply become unrestricted cash handed to the buyer.
Learn more in Hunt Brothers Realty's 2026 Florida seller-concession guide.
Can You Put 5% Down on a Florida Condo?
A qualified buyer can potentially finance an eligible Florida condominium used as a primary residence with 5% down, but condo financing introduces another layer of underwriting: the project itself.
Fannie Mae's April 22, 2026 Selling Guide contains Florida-specific project-review requirements for attached condominium units. For established Florida condo projects, qualifying principal-residence units can reach 95% loan-to-value under applicable full-review requirements and up to 97% through qualifying Desktop Underwriter scenarios, subject to the complete project and loan requirements.
The lender may need to evaluate matters involving the association and project, which can include applicable insurance, finances, structural issues, litigation, assessments and other project characteristics under current mortgage guidelines.
That means a buyer can be personally qualified for a 5% down mortgage while a particular condominium still presents financing issues.
Before making a purchasing decision, buyers should have their lender evaluate the specific condo project and separately review association documents, reserves, assessments, insurance and building information with the appropriate real estate, legal, insurance, inspection and other qualified professionals.
Can You Put 5% Down on a Florida Second Home?
Do not assume that a primary-residence down-payment rule carries over to a second home.
Fannie Mae's April 2026 standard eligibility matrix shows a maximum 90% loan-to-value for qualifying one-unit second-home purchases. In a straightforward purchase-price example, 90% financing corresponds to a 10% down payment.
Other mortgage products and individual lender requirements can differ. Second-home classification also has occupancy and use requirements, so a property intended primarily as a rental should not simply be labeled a second home to obtain different financing terms.
Buyers considering a Florida vacation or second home should explain the intended use accurately and obtain current financing requirements from their mortgage professional.
Can You Put 5% Down on a Florida Rental Property?
A conventional 5% down primary-residence loan should not be assumed to apply to a non-owner-occupied rental property.
Fannie Mae's April 2026 standard eligibility matrix shows a maximum 85% loan-to-value for qualifying one-unit investment-property purchases. In a simplified purchase, that corresponds to at least 15% down. Two- to four-unit investment properties have lower maximum loan-to-value limits under the standard matrix.
Portfolio, bank and other investment loan products can use different standards. Buyers should accurately disclose the intended occupancy and obtain the applicable requirements from qualified lenders before evaluating the property's cash needs.
Is FHA Better Than Conventional Financing With 5% Down?
There is no universal answer. FHA and conventional financing have different underwriting, mortgage-insurance, property and pricing structures.
An eligible FHA borrower can potentially use the program's 3.5% minimum required investment rather than 5%. But a lower minimum down payment does not by itself establish that FHA is the less expensive or more appropriate loan.
Ask the lender to compare the same purchase using both programs when the buyer qualifies. The comparison should include:
- Down payment
- Interest rate
- Annual percentage rate
- Mortgage insurance
- Lender charges
- Estimated monthly payment
- Estimated cash to close
- Mortgage-insurance duration and applicable cancellation rules
The better option depends on the actual borrower and financing terms, not simply which program advertises the smaller minimum down payment.
What If You Qualify for a 3% Down Conventional Loan?
Then 5% may not be your minimum required down payment.
Fannie Mae currently permits up to 97% loan-to-value for certain qualifying principal-residence purchases. Its standard 97% option requires at least one borrower to be a first-time homebuyer, while HomeReady can provide up to 97% financing for qualified borrowers who satisfy that program's income and other requirements. Freddie Mac's Home Possible program can also provide up to 97% loan-to-value for eligible one-unit properties.
That creates an important planning question. If you qualify for both 3% and 5% down, should you put down the extra 2%?
There is no universal answer. The additional down payment lowers the loan amount and may change mortgage-insurance pricing or other financing terms, but it also reduces the cash you retain after closing.
Have the lender price both options using the same purchase price so you can compare the actual cash requirement and monthly cost.
Why Might 5% Down Make Sense for Some Buyers?
The potential advantage is cash preservation. A buyer can purchase with less cash committed to equity than with a 10% or 20% down payment.
For example, on a $500,000 home:
- 5% down requires $25,000
- 10% down requires $50,000
- 20% down requires $100,000
The 5% structure preserves $75,000 compared with putting 20% down.
For some buyers, keeping more cash available for emergency savings, repairs, furnishings, insurance deductibles or other financial priorities can be important. For others, reducing the mortgage balance and potentially avoiding PMI may be more valuable.
This is a personal financial decision. Buyers should evaluate the tradeoff with a qualified lender and, when appropriate, a financial professional rather than treating either 5% or 20% as automatically superior.
What Are the Tradeoffs of Putting Only 5% Down?
Lower upfront cash does not mean there are no tradeoffs. Compared with putting substantially more money down, a 5% down conventional purchase can involve:
- A larger mortgage balance
- A higher monthly principal-and-interest payment, all else equal
- Private mortgage insurance
- Less initial equity
- Potential differences in loan pricing
- Greater sensitivity to the complete monthly ownership cost
The complete monthly housing expense matters especially in Florida because homeowners insurance, flood insurance when applicable, property taxes and HOA or condominium assessments can differ substantially among properties.
Hunt Brothers Realty's Florida home-affordability guide explains why buyers should budget around the complete monthly housing cost rather than mortgage principal and interest alone.
How Much Savings Should You Keep After a 5% Down Purchase?
The lender's minimum cash requirement and the amount a buyer personally wants available after closing answer different questions.
After purchasing a Florida home, owners can encounter expenses involving:
- Insurance deductibles
- HVAC repairs
- Roof maintenance
- Plumbing or electrical repairs
- Appliances
- Pool equipment
- Landscaping
- Condominium or HOA assessments
- Other unexpected ownership expenses
A buyer who technically qualifies with 5% down but would have almost no savings remaining after closing may want to reconsider the complete purchase budget. The appropriate reserve depends on the household and property, so buyers should make that decision based on their individual finances rather than a universal dollar amount.
What Should You Do Before Shopping With 5% Down?
Get the financing structure established before relying on a 5% down budget.
Ask qualified mortgage professionals to provide scenarios showing:
- 5% down
- Any lower-down-payment option for which you qualify
- 10% down
- 20% down when financially realistic
- Interest rate for each scenario
- Annual percentage rate
- Mortgage insurance
- Estimated closing costs
- Estimated monthly payment
- Estimated cash to close
Then evaluate actual properties using their estimated taxes, insurance, flood insurance when applicable, HOA or condominium assessments and likely maintenance needs.
The Bottom Line: 5% Down Can Be a Realistic Florida Homebuying Option
Yes, qualified buyers can purchase many Florida primary residences with a 5% down conventional mortgage. It is not an unusual or theoretical financing structure.
On a $400,000 home, 5% equals $20,000. On a $500,000 home, it equals $25,000. On a $750,000 home, it equals $37,500.
But those numbers represent only the down payment. Closing costs, insurance, inspections, reserves and other purchase expenses still matter. A 5% down conventional mortgage will also generally involve mortgage insurance.
Most importantly, do not assume that the same 5% structure applies to every property. Primary residences, second homes, investment properties and Florida condominiums can have different financing requirements.
Have your lender establish the financing first, then shop for homes using a budget that accounts for the complete cost of buying and owning the property.
Start Your Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty helps buyers evaluate Sarasota and Florida Gulf Coast homes based on more than the listing price. Property taxes, insurance considerations, HOA or condominium expenses, property condition and location can all affect the complete ownership budget.
Before shopping, review Hunt Brothers Realty's guide to choosing a home down payment, learn about Florida buyer closing costs, and use the Florida home-affordability guide to think beyond the mortgage payment alone.
You can also explore Florida Gulf Coast communities or contact Hunt Brothers Realty to discuss your property search.
This article provides general real estate and educational information only and is not individualized mortgage, lending, financial, tax, legal or insurance advice. Mortgage programs, loan-to-value limits, underwriting requirements, mortgage insurance, rates, fees and eligibility can change and vary by borrower, lender, occupancy and property. Buyers should verify their financing, down payment, mortgage insurance, closing costs and estimated cash to close with a qualified mortgage lender or loan professional. Insurance availability, coverage and premiums can vary substantially by property, so buyers should obtain property-specific quotes from a qualified insurance professional before making a purchasing decision. Legal or contractual questions should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional.
Sources
- Fannie Mae, 2026 Eligibility Matrix
- Fannie Mae, Selling Guide, April 22, 2026
- Fannie Mae, 97% Loan-to-Value Options
- Freddie Mac, Home Possible Mortgage
- Hunt Brothers Realty, How Much Should You Put Down on a House?
- Hunt Brothers Realty, Florida Buyer Closing Costs in 2026
- Hunt Brothers Realty, What Credit Score Do I Need to Buy a House in Florida?
- Hunt Brothers Realty, How Much House Can You Afford in Florida?
- Hunt Brothers Realty, Seller Concessions in Florida
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2090
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1151
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1069
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1260
- Foreclosures 4
- Home Selling 4
- Homeownership 1283
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1224
- Market Updates & Trends 747
- Mortgages & Financing 45
- Move-Up Buyers 21
- Neighborhood Guides 860
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1141
- Relocation to Florida 1181
- Safety Harbor 3
- Sarasota 79
- Sarasota - Downtown 162
- Selling a Home 144
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1333
- Venice 179
- Wellen Park 17
Recent Posts