How Do HOA and CDD Fees Affect How Much Home You Can Afford?
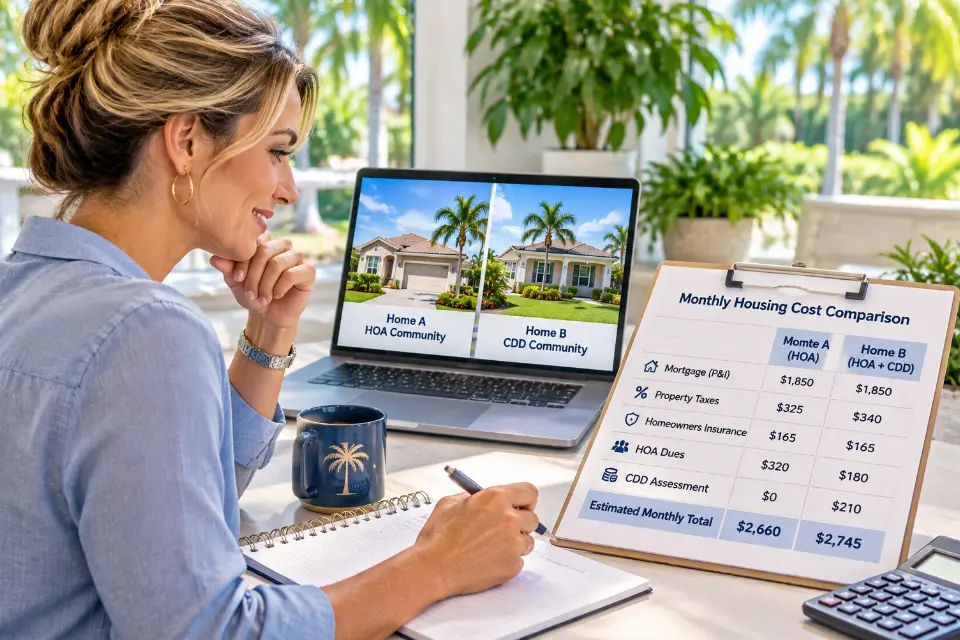
HOA dues and CDD assessments can reduce how much room you have in your monthly housing budget, and they may also affect mortgage qualification. A $500,000 home with substantial recurring community charges can have a higher total monthly cost than another $500,000 home with lower fees. HOA dues are generally association charges, while a Florida Community Development District, or CDD, is a governmental district that may levy assessments for infrastructure, debt, operations and maintenance. Because a property can have both, buyers should compare homes using the complete monthly ownership cost, not purchase price or mortgage principal and interest alone.
Quick Answers About HOA and CDD Fees and Home Affordability
Do HOA fees affect how much house I can afford?
Yes. HOA dues increase the recurring cost of owning the property. For mortgage qualification, applicable association dues can also be included in the monthly housing expense considered by the lender.
Do CDD fees affect home affordability?
Yes. CDD assessments are recurring property-related costs and should be included when comparing your total ownership budget. Buyers should ask their mortgage professional how the specific property's CDD assessment will be treated for loan qualification and escrow purposes.
Are HOA and CDD fees the same thing?
No. An HOA is generally a private homeowners association operating under community governing documents, while a CDD is a governmental district established under Florida law. A home may be subject to one, both or neither.
Are CDD fees included in HOA dues?
Generally, no. HOA dues and CDD assessments are separate obligations. Buyers should verify both independently instead of assuming an advertised HOA amount represents every community-related cost.
Are CDD assessments included in the property tax bill?
They often can be collected through the county tax bill, including as non-ad valorem assessments, but collection arrangements can vary. Buyers should verify the exact parcel and avoid adding a CDD assessment twice when building a budget if it is already included in the tax figure being used.
Do CDD fees eventually go away?
Not necessarily. A debt-related assessment may end after the applicable debt is satisfied, but operations and maintenance assessments may continue. Buyers should not assume the entire CDD charge will disappear on a particular date without verifying the district's records.
Is a home with lower HOA fees automatically more affordable?
No. A lower HOA fee may come with fewer included services, while a higher assessment may cover expenses you would otherwise pay separately. Compare the complete ownership budget, what the fees include and the property's other recurring costs.
Why Do HOA and CDD Fees Change the Affordability Calculation?
HOA and CDD charges matter because the purchase price is only one part of what a home costs each month. Buyers also need to account for mortgage principal and interest, property taxes, insurance and other property-specific obligations.
For example, imagine two homes with identical purchase prices and similar mortgage terms. One has $100 per month in community-related costs, while another has $500 per month when its HOA and CDD obligations are converted to monthly equivalents. The second property requires an additional $400 every month before considering differences in insurance, taxes, maintenance or utilities.
That example is purely illustrative, but the budgeting principle is important. Hunt Brothers Realty's guide to the true cost of buying a home in Florida explains why buyers should evaluate recurring ownership expenses instead of focusing only on the mortgage payment.
How Do HOA Fees Affect Mortgage Qualification?
Applicable HOA dues can be included in the monthly housing expense a lender uses when evaluating a mortgage. That means the association fee can affect qualification even when the HOA bill itself is paid directly to the association rather than through the mortgage servicer.
The Fannie Mae Selling Guide identifies principal and interest, applicable insurance, real estate taxes, special assessments and owners' association dues among the components of monthly housing expense. For a principal residence, that housing expense is used in calculating the borrower's debt-to-income ratio under applicable underwriting requirements.
This does not mean there is one universal formula that tells every buyer how much an HOA fee will reduce purchasing power. Loan program, income, existing debts, interest rate, down payment, credit profile and other underwriting factors can change the result. A qualified mortgage lender should calculate the effect for the buyer's specific financing scenario.
How Do CDD Assessments Affect Your Housing Budget?
A CDD assessment increases the recurring cost associated with the property and therefore belongs in the affordability calculation. The important difference is that a CDD is not simply another HOA.
As explained in Hunt Brothers Realty's Florida CDD fee guide, a Community Development District is a special-purpose local government created under Florida law. Depending on the district, assessments can help fund infrastructure, facilities, operations, maintenance and applicable debt obligations.
Florida law authorizes Community Development Districts to levy certain assessments, including benefit special assessments associated with district facilities and projects. Under Section 190.021 of the 2026 Florida Statutes, certain district assessments may be entered on county tax rolls and collected with county taxes.
For mortgage qualification, the treatment of a particular CDD assessment can depend on how the charge is structured and reflected in the property's recurring expenses. Buyers should provide the property's actual CDD information to their lender and ask how it is being incorporated into the lender's calculations.
What Is the Difference Between an HOA Fee and a CDD Assessment?
An HOA and a CDD are legally different organizations, even though both can create recurring costs for a homeowner. Understanding the distinction helps buyers determine what they are paying, who controls the charge and what responsibilities it supports.
| Question | HOA | CDD |
|---|---|---|
| What is it? | Generally a private homeowners association | A governmental district established under Florida law |
| What can it fund? | Association operations, common areas, amenities, management and other responsibilities established by applicable documents | Authorized infrastructure, facilities, operations, maintenance and applicable financing obligations |
| How is it commonly billed? | Directly by the association or its management company on its billing schedule | Often through the property tax bill, although collection methods can vary |
| Can the same property have both? | Yes | Yes |
For a deeper review of association ownership, see Hunt Brothers Realty's 2026 guide to buying a home in a Florida HOA.
Can a Home Have Both HOA and CDD Fees?
Yes. A Florida property can be subject to both HOA dues and CDD assessments, and buyers need to include both when evaluating affordability. This structure can be encountered in master-planned communities where the association and governmental district have different responsibilities.
A buyer might see an advertised HOA assessment and mistakenly assume it represents the property's complete community-related cost. The property could also have a CDD assessment on the tax bill, a master association charge, a neighborhood association assessment or another applicable recurring obligation.
Ask for the exact fee structure associated with the individual property. Do not assume every home within a large development has identical obligations, because different neighborhoods, districts or property types can have different assessments.
How Can Two Homes With the Same Price Have Different Monthly Costs?
Two identically priced homes can have substantially different monthly ownership costs because taxes, insurance, HOA dues, CDD assessments and other expenses can differ. Purchase price alone is therefore an incomplete affordability comparison.
Consider this hypothetical example:
| Monthly Expense | Home A | Home B |
|---|---|---|
| Mortgage principal and interest | $2,600 | $2,600 |
| Property taxes | $450 | $450 |
| Homeowners insurance | $300 | $300 |
| HOA dues | $100 | $350 |
| CDD assessment | $0 | $150 |
| Illustrative total | $3,450 | $3,850 |
In this illustration, Home B costs $400 more per month even though the purchase price and assumed mortgage principal and interest are identical. That difference equals $4,800 over one year before considering changes in fees or other expenses.
These figures are hypothetical and are not a mortgage quote, tax estimate, insurance quote or representation of a particular community. When calculating a real property, also make sure a CDD assessment is not being counted separately if it is already included in the property-tax figure used in the calculation.
Does a $300 Monthly HOA Fee Mean You Can Afford $300 Less in Mortgage Payment?
The HOA charge uses part of the monthly housing budget, but you should not convert it into a specific reduction in purchase price without a lender's calculation. Mortgage qualification is more complicated than subtracting the fee from a payment and converting the difference directly into a loan amount.
Interest rates, loan term, down payment, mortgage insurance, taxes, insurance, income and other debts all influence qualification. A $300 recurring charge can have a different effect for different borrowers and properties.
For that reason, buyers comparing an HOA property with a non-HOA property should ask their lender to run both addresses or realistic scenarios. That provides a much more useful comparison than relying on a generic online mortgage calculator that may omit association or CDD expenses.
How Should You Convert Quarterly or Annual Fees Into a Monthly Budget?
Convert recurring assessments to a monthly equivalent so homes with different billing schedules can be compared consistently. A quarterly bill can feel less significant when viewed only at the time it is due, but it remains part of the annual ownership cost.
For example, an HOA charging $900 each quarter would have a $3,600 annual cost. Dividing $3,600 by 12 produces a $300 monthly equivalent. Likewise, a $1,800 annual CDD assessment represents a $150 monthly equivalent for budgeting purposes.
Hunt Brothers Realty's Florida HOA fee guide uses this monthly-equivalent approach to help buyers compare recurring costs across communities with different billing schedules.
Can HOA Fees Increase After You Buy?
Yes. Buyers should not assume today's HOA assessment will remain unchanged for as long as they own the home. Association expenses can change because of insurance, maintenance, contracts, reserve needs, capital projects and other authorized obligations.
This is why affordability analysis should include more than the current fee printed in a listing. Review the current budget, recent assessment history, available reserve information, meeting records when relevant, major projects and approved or proposed special assessments.
A low HOA fee is not automatically evidence of a financially stronger community. One association may maintain only limited common areas, while another may maintain private roads, extensive landscaping, pools, club facilities or other significant assets. Buyers should compare responsibilities along with the dollar amount.
Can CDD Assessments Change Over Time?
Yes. Buyers should not assume the current CDD amount will remain exactly the same or that every component will end at the same time. A district can have different assessment components with different purposes.
A debt-service component may be associated with financing district infrastructure. Operations and maintenance assessments support ongoing district expenses and may continue after particular debt obligations have been satisfied. Annual amounts can change based on the district's adopted budget and authorized obligations.
Before relying on a future payoff date, request current information from the applicable CDD. If prepayment of a debt assessment is important to your purchase decision, obtain the district's official information regarding the specific parcel rather than relying on an informal estimate.
Should You Avoid a Home Because It Has an HOA or CDD?
No. The existence of an HOA or CDD does not by itself determine whether a property is a good financial fit. The more useful comparison is what you pay, what the applicable organization is responsible for and how the complete cost fits your budget.
An HOA assessment might cover landscaping, recreational facilities, common areas or other services that a homeowner elsewhere would pay for separately. A CDD may finance or maintain infrastructure and facilities within a development. Those responsibilities vary substantially by community.
The opposite assumption is also risky. Amenities do not make an otherwise unaffordable monthly payment affordable. Buyers should decide whether the services and community characteristics are useful to them after confirming that the complete housing cost works within their financial plan.
What Should You Include in a Florida Home Affordability Calculation?
A useful affordability calculation should extend beyond principal and interest to the recurring and longer-term costs associated with the specific property. Not every expense below will apply to every home, but each should be investigated when relevant.
- Mortgage principal and interest
- Estimated property taxes after purchase
- Homeowners insurance
- Flood insurance when applicable or desired
- Mortgage insurance when applicable
- HOA or condominium assessments
- CDD assessments
- Master association or sub-association charges
- Known special assessments
- Mandatory club or amenity charges when applicable
- Utilities
- Lawn, pool or exterior maintenance not included in association dues
- Routine maintenance and longer-term repairs
The seller's current expenses should not automatically be treated as the buyer's future expenses. Property taxes can change after a sale, insurance quotes are property and buyer specific, and association or district assessments can change.
What Should You Verify Before Making an Offer in an HOA or CDD Community?
Verify the exact property's current obligations rather than relying on a general community estimate. This is particularly important in large Florida developments where different neighborhoods can have different associations, districts or fee structures.
- Current regular HOA or condominium assessment
- Billing frequency
- What the association assessment includes
- Master and sub-association charges, if any
- Approved or proposed special assessments
- Current association budget and relevant financial information
- CDD debt-service assessment, if applicable
- CDD operations and maintenance assessment, if applicable
- Whether CDD charges are already reflected in the tax figure you are using
- Any mandatory club, amenity or other recurring community charges
- How the lender will treat each applicable charge for qualification
For HOA properties, review the governing documents and financial information rather than relying solely on the listing. For CDD properties, review the applicable district's current records and parcel-specific assessment information. Legal questions about association obligations, assessment authority or property rights should be reviewed with a qualified Florida real estate attorney.
How Should New-Construction Buyers Handle HOA and CDD Costs?
New-construction buyers should identify every association and district charge before comparing a builder's advertised payment with the real ownership budget. Newer master-planned communities can have multiple layers of recurring expenses.
Hunt Brothers Realty's Florida new-construction buyer guide notes that HOA dues and CDD assessments are separate obligations even when both apply to the same property. Buyers should also determine whether additional master association, neighborhood, club or amenity charges apply.
Do not estimate the completed home's future affordability from the tax bill for a vacant homesite or partially completed property. Ask the lender and appropriate local sources for a reasonable property-specific estimate of post-purchase taxes and other recurring expenses.
What Is the Best Way to Compare Homes With Different Fees?
Compare homes using a property-specific monthly ownership worksheet instead of ranking them by purchase price or HOA fee alone. Convert annual and quarterly expenses into monthly equivalents, then compare the complete picture side by side.
For example, a home with a higher HOA assessment could still have a competitive overall budget if the association covers landscaping or other expenses you would otherwise pay separately. Another home may advertise a very low HOA assessment but have a separate CDD, private lawn service, pool maintenance or other costs.
The objective is not to find the lowest fee. It is to understand the total cost, what each charge funds and whether the complete property fits your budget and priorities.
What Is the Bottom Line on HOA and CDD Fees?
HOA and CDD fees can materially affect home affordability because they add recurring costs beyond mortgage principal and interest. HOA dues can also be part of the monthly housing expense used in mortgage underwriting, while the treatment of a property's CDD assessment should be confirmed with the lender based on the actual charge and financing.
The safest comparison is property specific. Verify the HOA, CDD, taxes, insurance, special assessments and other recurring obligations for each home you are seriously considering, then have your lender calculate the financing using those actual figures.
A home with community fees is not automatically less attractive, and a home without them is not automatically less expensive to own. What matters is the complete cost and whether the property works for your financial plan.
Compare the Complete Cost of Florida Homes With Hunt Brothers Realty
Hunt Brothers Realty can help buyers identify HOA, CDD and other property-specific costs when comparing homes across Sarasota and Florida Gulf Coast communities. Review our guides to Florida HOA fees, Florida CDD assessments and the true cost of buying a Florida home, or contact Hunt Brothers Realty to discuss a property search.
Informational notice: This article provides general real estate and educational information only and is not individualized financial, mortgage, tax, legal, association or other professional advice. Mortgage qualification and the treatment of HOA dues, CDD assessments, taxes and other obligations depend on the borrower, property, loan program and lender requirements. Buyers should obtain property-specific calculations from a qualified mortgage professional, verify HOA information with the applicable association, verify CDD assessments with the applicable district and county records, and consult a qualified Florida real estate attorney or tax professional when legal or tax interpretation is required.
Sources
- Fannie Mae Selling Guide, Monthly Housing Expense for the Subject Property
- 2026 Florida Statutes, Section 190.021, Community Development District Taxes and Assessments
- Hunt Brothers Realty, What Is a CDD Fee in Florida?
- Hunt Brothers Realty, Buying a Home in a Florida HOA: 2026 Buyer's Guide
- Hunt Brothers Realty, How Much Are HOA Fees in Florida?
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2694
- Anna Maria Island 93
- Bird Key 6
- Bradenton 242
- Buying a Home 1708
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1643
- Ellenton 9
- Englewood 16
- First Time Homebuyers 1832
- Foreclosures 4
- Home Selling 12
- Homeownership 1878
- Lakewood Ranch 37
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1821
- Market Updates & Trends 1321
- Mortgages & Financing 88
- Move-Up Buyers 24
- Neighborhood Guides 1449
- New Construction 47
- Palmetto 4
- Parrish 39
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1734
- Relocation to Florida 1762
- Safety Harbor 4
- Sarasota 163
- Sarasota - Downtown 175
- Selling a Home 149
- Siesta Key 95
- St. Petersburg 11
- Taxes and Homestead 5
- Tierra Verde 7
- Vacation & Second Homes 1927
- Venice 225
- Wellen Park 24
Recent Posts