What Should I Know Before Buying an Older Florida Condo?
Before buying an older Florida condo, investigate both the individual unit and the condominium association responsible for the building and common property. Review the association's finances, reserve funding, special assessments, insurance, major repair history, governing documents and recent meeting records. For applicable buildings, examine the current milestone inspection and Structural Integrity Reserve Study, commonly called a SIRS. Buyers should also investigate financing eligibility, flood and insurance considerations, unit condition, rental and pet restrictions, parking and storage rights, and upcoming capital projects. An older condominium is not automatically a poor choice, but its age makes documented maintenance, financial planning and building-specific due diligence especially important.
Quick Answers About Buying an Older Florida Condo
Are older Florida condos risky to buy?
Not necessarily. Age alone does not tell you whether a condominium is well maintained or financially prepared for future repairs. An older building with documented maintenance, completed capital projects and appropriate financial planning may compare favorably with another property that requires substantial upcoming work.
What is a Florida condo milestone inspection?
A milestone inspection is a structural inspection of a qualifying aging condominium or cooperative building used to determine whether substantial structural deterioration exists. Under current Florida law, qualifying buildings generally receive an initial milestone inspection at 30 years and every 10 years thereafter, although a local enforcement agency may require the initial inspection at 25 years based on local circumstances.
What is a Structural Integrity Reserve Study?
A Structural Integrity Reserve Study, or SIRS, evaluates specified condominium components, their estimated remaining useful lives, anticipated replacement or deferred-maintenance costs and a recommended reserve funding plan. Under current Florida law, residential condominium associations generally must complete a SIRS at least every 10 years for each condominium building that is three habitable stories or higher.
Are a milestone inspection and SIRS the same thing?
No. A milestone inspection focuses on structural condition, while a SIRS is a reserve-planning study involving specified building components and future funding needs. They are separate requirements, although Florida law permits them to be coordinated in certain circumstances.
Should I worry about a special assessment?
A special assessment deserves careful investigation, but it is not automatically a reason to reject a condominium. Determine why the assessment was imposed, the total obligation, the unit's share, payment schedule, work being funded and whether additional projects or assessments are being discussed.
Is a low monthly condo fee always better?
No. A lower fee can reflect fewer services, but the fee alone does not reveal whether reserves are appropriate or major expenses are approaching. Compare the current fee with the budget, reserve funding, insurance, maintenance responsibilities and anticipated capital projects.
Do I still need a unit inspection if the building had a milestone inspection?
Yes, buyers should consider an independent inspection of the individual unit. A milestone inspection has a different scope and does not replace an evaluation of accessible unit systems and conditions by an appropriate qualified inspector.
Can an older condo be harder to finance or insure?
It can be, depending on the building and transaction. Project condition, association finances, insurance, assessments and other factors can affect lending or insurance availability. Buyers should obtain property-specific guidance from their lender and insurance professional early in the purchase process.
Why Does Buying an Older Florida Condo Require Extra Due Diligence?
Older Florida condos require careful due diligence because the buyer is purchasing more than an individual residence. Condo ownership also creates an interest in common property and financial responsibility for association expenses according to the condominium's governing documents and applicable law.
An attractive renovated unit can be located in a building facing significant roof, structural, waterproofing, plumbing, electrical, elevator or other capital work. Conversely, an older unit with dated finishes can be located in a building that has already completed substantial common-area improvements.
That is why buyers should evaluate both sides of the purchase. Hunt Brothers Realty's Florida condo buying guide explains the broader association, financial, insurance and ownership questions that apply when comparing Florida condominiums.
What Is a Florida Milestone Inspection?
A milestone inspection is a structural inspection of an aging condominium or cooperative building intended to determine whether substantial structural deterioration exists. It is a building-level inspection and should not be confused with a buyer's inspection of an individual condo unit.
Under Section 553.899 of the 2026 Florida Statutes, condominium and cooperative buildings that are three habitable stories or more generally must have a milestone inspection by December 31 of the year in which the building reaches 30 years of age, followed by another inspection every 10 years.
The Florida Department of Business and Professional Regulation condominium inspection guidance also explains that a local enforcement agency may determine that local circumstances require the initial milestone inspection at 25 years rather than 30 years.
For a buyer, the practical question is not simply, "How old is this building?" Ask whether a milestone inspection applies, whether it has been completed, what the report found and what work has been recommended, planned or completed as a result.
What Is a Structural Integrity Reserve Study?
A Structural Integrity Reserve Study is a reserve-planning study that evaluates specified building components and estimates future funding needs for repair, replacement or deferred maintenance. It is commonly referred to as a SIRS.
Under Section 718.112 of the 2026 Florida Statutes, a residential condominium association generally must have a SIRS completed at least every 10 years after the condominium's creation for each building that is three habitable stories or higher, as determined by the Florida Building Code.
The current statute identifies components including:
- Roof
- Structural systems
- Fireproofing and fire protection systems
- Plumbing
- Electrical systems
- Waterproofing and exterior painting
- Windows and exterior doors
- Certain other qualifying components affecting structural integrity
The study identifies estimated remaining useful lives, anticipated replacement costs or deferred-maintenance expenses and a recommended reserve funding schedule. Buyers can use the report as one part of understanding the association's anticipated capital needs, but technical findings should be reviewed with an appropriately qualified engineer, architect, inspector or other professional when they materially affect a purchasing decision.
Is a SIRS the Same as a Milestone Inspection?
No. A milestone inspection and a Structural Integrity Reserve Study are separate requirements with different purposes. The milestone inspection focuses on the structural condition of an aging building, while the SIRS addresses specified components and the reserve funding needed for anticipated repairs and replacement.
The Florida DBPR condominium FAQs specifically distinguish the two. Current law permits coordination between the inspections in certain circumstances, but buyers should not assume that completion of one means the other requirement has been satisfied.
When reviewing an older building, ask for the applicable documentation for each requirement separately.
What Should You Look for in a Milestone Inspection Report?
Look for the report's findings, whether additional investigation was required and what repairs or corrective work have been recommended or completed. Do not reduce a technical inspection report to a simple "pass" or "fail" without understanding what the report actually says.
Useful follow-up questions include:
- When was the inspection completed?
- Was additional inspection or testing required?
- What repairs were recommended?
- Which repairs have been completed?
- Which projects remain outstanding?
- What is the expected funding source for remaining work?
- Are permits, engineering plans or construction contracts involved?
- Has the association discussed additional assessments or borrowing?
Structural and engineering reports can contain technical conclusions that require professional interpretation. Buyers with material concerns should have the applicable findings evaluated by an appropriate Florida-licensed engineer, architect, inspector, contractor or other qualified professional before making a purchasing decision.
How Should You Evaluate an Older Condo Association’s Reserves?
Do not evaluate reserves solely by looking at the amount of money in a reserve account. The meaningful question is whether available funds and planned contributions make sense relative to the association's anticipated repair and replacement obligations.
A building with a large reserve balance can still have substantial upcoming expenses. A building with a smaller balance may have recently completed major projects. Context matters.
Review items such as:
- Current reserve balances
- Annual reserve contributions
- The current SIRS when applicable
- Estimated remaining useful lives of major components
- Estimated repair and replacement costs
- Major projects recently completed
- Projects expected in upcoming years
- Association loans or other significant obligations
- How anticipated projects are expected to be funded
Florida's reserve requirements have changed substantially in recent years. Buyers should rely on current records and current law rather than assuming that historical reserve practices will continue. Hunt Brothers Realty's guide to reading Florida condo documents provides a more detailed framework for reviewing reserve and financial information.
Why Can Reserve Requirements Affect Condo Fees?
Reserve requirements can affect owner costs because an association must fund anticipated common-property obligations in accordance with applicable law and its current financial plan. If a SIRS identifies funding needs that exceed available reserves and planned contributions, the association may need to change assessments or consider other permitted funding methods.
Florida DBPR explains that when a SIRS indicates insufficient reserve funding for anticipated major structural expenses, an association may need additional assessments or financing to satisfy the applicable funding schedule.
This is one reason the current monthly condo fee should never be viewed in isolation. A buyer should investigate what the fee covers, current reserve contributions, upcoming projects and any approved or discussed changes to the association's financial plan.
What Should You Know About Special Assessments?
A special assessment is an important financial obligation to investigate because it can materially change the real cost of purchasing a condo. Buyers should ask about approved assessments, unpaid balances and assessments being discussed or proposed.
For each relevant assessment, determine:
- What project or expense is being funded?
- What is the unit's total assessment obligation?
- How much has already been paid?
- What balance remains?
- Can the balance be paid over time?
- Who is responsible for payment under the applicable contract and closing arrangements?
- Has the project started or been completed?
- Are additional major projects being considered?
A large assessment is not automatically evidence of a poorly managed building. It might be paying for substantial improvements that extend the useful life of major components. The buyer still needs to understand the obligation, project scope and financial context.
Questions involving contractual responsibility for an assessment, closing obligations or other legal rights should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional.
What Condo Documents Should You Read Before Buying?
Review the governing documents and financial records, not just the listing information and current monthly fee. The documents can reveal ownership restrictions, financial obligations and planned building work that may not be apparent during a showing.
Depending on the condominium and transaction, relevant records can include:
- Declaration of condominium and amendments
- Articles of incorporation
- Bylaws
- Current association rules
- Current annual budget
- Recent financial statements
- Reserve information
- Current SIRS when applicable
- Milestone inspection information when applicable
- Special-assessment information
- Association insurance information
- Recent board and association meeting minutes
- Information concerning major completed and planned projects
- Rental, pet and renovation restrictions
- Parking and storage documentation
For a deeper explanation, see Hunt Brothers Realty's condo document checklist for Florida buyers and guide to reading Florida condominium documents.
Why Should You Read Condo Meeting Minutes?
Recent meeting minutes can help buyers identify projects, repair discussions, insurance concerns, proposed assessments and other association matters that may not be obvious from the annual budget alone. They provide useful context for understanding what the board and owners have recently been discussing.
Look for recurring discussions involving:
- Concrete or structural repairs
- Roof replacement
- Waterproofing
- Balcony or exterior work
- Elevator projects
- Plumbing or electrical projects
- Insurance renewals and deductibles
- Reserve funding
- Association borrowing
- Special assessments
One mention of a repair does not necessarily indicate a serious problem. Repeated discussion can, however, identify an issue worth investigating through additional records or professional review.
Should You Inspect the Individual Condo Unit?
Yes, buyers should consider an independent inspection of the individual residence even when the condominium building has undergone association-level inspections. A building milestone inspection does not replace a unit-specific evaluation.
Depending on the property and inspection scope, a unit inspection may help identify issues involving accessible electrical, plumbing, HVAC, appliances, moisture, windows, doors and interior components.
Older renovated units also deserve careful attention. New flooring, cabinetry and finishes do not establish the age or condition of systems behind the walls or confirm that renovations were completed with all required approvals or permits.
Inspection findings should be evaluated with the appropriate licensed inspector, contractor, engineer or other qualified professional before the buyer makes a decision.
What Should You Know About Insurance Before Buying an Older Condo?
Investigate both the association's insurance program and the insurance available for the individual unit before making a final purchasing decision. Condominium insurance involves different layers of responsibility, and buyers should not assume that the association's policy covers everything inside the residence.
Questions can include:
- What association insurance policies are currently in place?
- What are the relevant deductibles?
- What property is the association responsible for insuring?
- What should the individual unit owner insure?
- What coverage is available for the specific unit?
- What will the individual policy cost?
- What flood-insurance considerations apply?
Insurance availability, coverage and premiums can vary substantially by condominium and unit. Buyers should obtain property-specific quotes and have the association's coverage and their individual insurance needs reviewed by a qualified insurance professional before making a purchasing decision.
Can an Older Florida Condo Create Financing Issues?
Yes, condominium project characteristics can affect financing, so buyers using a mortgage should discuss the specific project with their lender early. Approval of the individual borrower does not necessarily mean every condominium project will satisfy the lender or loan program's requirements.
Building condition, insurance, assessments, association finances, litigation and other project characteristics may be relevant depending on the loan program and lender.
A buyer should therefore ask a qualified mortgage lender or loan professional to evaluate the specific condominium project rather than assuming that financing will be available simply because the buyer has been preapproved for a particular loan amount.
What Should Waterfront Condo Buyers Investigate?
Older waterfront condo buyers should investigate building condition and association finances along with property-specific coastal, flood and boating considerations. A water view does not answer questions about flood exposure, seawalls, docks or boat-slip rights.
Depending on the condominium, useful questions may include:
- What flood-zone information applies to the property?
- Has the association completed significant seawall or waterfront infrastructure work?
- Who is responsible for maintaining waterfront structures?
- Are docks or boat slips part of the condominium property?
- Is a particular boat slip legally assigned to or conveyed with the unit?
- Are there vessel-size, water-depth or access limitations?
- What insurance considerations apply to the individual unit?
Boat-slip rights, parking, storage and other limited-use rights can be unit-specific and should be independently confirmed through the appropriate association and transaction documents. Flood and insurance questions should likewise be evaluated using current property-specific information.
Should You Verify Rental and Pet Rules Before Buying?
Yes. Verify current rental, pet and occupancy rules before buying if any of those issues matter to your intended use. Do not rely solely on an old listing, a verbal statement or rules from a different condominium in the same area.
For rentals, investigate minimum lease periods, frequency limitations, approval procedures and other current restrictions. A buyer planning vacation or seasonal rentals should also investigate applicable governmental licensing and rental requirements.
Pet policies can include number, size or other restrictions and may change over time. Current requirements should be verified directly through the applicable condominium documents and association.
How Should You Verify Parking and Storage?
Confirm exactly what parking and storage rights are associated with the individual unit rather than assuming all residences receive the same rights. These details can vary by condominium and sometimes by unit.
Determine whether parking is assigned, deeded, a limited common element, or otherwise governed by association documents. Verify the location and number of spaces and whether guest-parking restrictions apply.
Use the same approach for storage. A listing that states a storage area exists should not substitute for confirming the unit's actual rights through the applicable records.
Is a Low Condo Fee a Sign of a Better Association?
No. The amount of the monthly or quarterly fee does not, by itself, establish whether an association is financially strong or weak. Buyers need to understand what the fee covers and how the association plans for major expenses.
One condominium may have a higher fee because it provides extensive amenities, includes certain utilities or contributes substantially to reserves. Another may have a lower regular fee but fewer included services or different future funding requirements.
Instead of comparing fees alone, compare the complete financial picture, including regular assessments, reserve contributions, insurance, special assessments, association debt and anticipated capital projects.
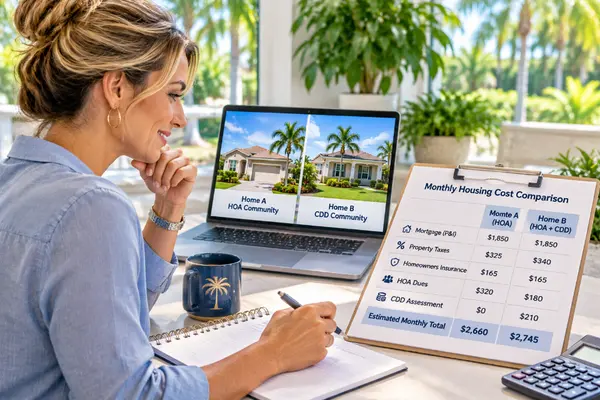
How Do You Calculate the Real Cost of an Older Florida Condo?
Calculate ownership costs beyond the mortgage payment and advertised condo fee. The complete financial picture can materially change how two similarly priced units compare.
Depending on the property and buyer, costs may include:
- Purchase price and financing costs
- Regular condominium assessments
- Current special-assessment obligations
- Property taxes
- Individual unit insurance
- Applicable flood-insurance costs
- Utilities not included in association assessments
- Unit maintenance and repairs
- Renovation costs
- Parking, storage or other property-specific charges where applicable
Future association fees, assessments, insurance premiums and repair costs cannot be predicted with certainty. Buyers should use current documentation and obtain individualized estimates from the appropriate professionals rather than relying on generalized assumptions.
What Are Warning Signs That Deserve More Investigation?
Certain findings should lead to additional questions, but they should not automatically be treated as reasons to reject an older condominium. The objective is to understand the facts and their implications before making a decision.
Issues worth investigating can include:
- Large capital projects without a clearly understood funding plan
- Repeated discussion of substantial building repairs
- Significant approved or proposed special assessments
- Material insurance changes or large deductibles
- Reserve funding that requires closer evaluation against anticipated projects
- Structural or engineering findings requiring further investigation
- Major projects whose final scope or cost remains uncertain
- Association loans or significant financial obligations
- Rules that conflict with the buyer's intended use
- Uncertainty about parking, storage, boat slips or other rights important to the buyer
Context is essential. A substantial assessment may be funding valuable completed improvements, while an older condominium may have a long history of documented capital maintenance. Investigate rather than assuming.
What Questions Should You Ask Before Buying an Older Florida Condo?
Ask questions about the building, association and individual unit before focusing exclusively on finishes, views and amenities. A structured checklist makes it easier to compare one condominium with another.
- How old is the building?
- Is a milestone inspection required, and what is its current status?
- Is a SIRS required, and can I review the current study?
- What major building projects have recently been completed?
- What major projects are planned or being discussed?
- What are the current reserve balances and contributions?
- Are there approved, pending or discussed special assessments?
- Does the association have outstanding loans or other major obligations?
- What does the association's insurance cover?
- Can I obtain appropriate insurance for the individual unit?
- Will my lender finance a unit in this specific condominium project?
- What did the individual unit inspection identify?
- What are the current rental and pet restrictions?
- What parking and storage rights belong to this unit?
- Are there renovation restrictions or approval procedures?
- What are the complete estimated monthly and annual ownership costs?
For additional questions, review Hunt Brothers Realty's questions to ask before buying a Florida condo in 2026.
Is an Older Florida Condo a Good Buy?
An older Florida condo can be a good fit when the individual unit, building condition, association finances, ownership costs and rules align with the buyer's priorities. Building age alone is not enough to make that determination.
Established condominiums can offer locations, views, floor plans, mature surroundings or other characteristics that appeal to buyers. The key is understanding the responsibilities and financial obligations that accompany the purchase.
Compare buildings using current records rather than assumptions. Review inspection information, reserve planning, assessments, insurance, association documents and unit condition, then involve the appropriate qualified professionals when an issue requires legal, financial, engineering, inspection, insurance or lending expertise.
Compare Florida Gulf Coast Condos With Hunt Brothers Realty
Hunt Brothers Realty can help buyers compare Florida Gulf Coast condominiums while keeping building-level and association-level considerations in view. Start with our complete Florida condo buying guide, learn how to read Florida condo documents, review our condo document checklist, or contact Hunt Brothers Realty to discuss condominium options in Sarasota and along Florida's Gulf Coast.
Informational notice: This article provides general real estate and educational information only and is not individualized legal, financial, insurance, lending, inspection, engineering, construction, association or other professional advice. Florida condominium laws and association circumstances can change, and inspection, reserve, assessment, insurance and financing issues are building-specific. Buyers should review current condominium records and applicable requirements for the specific property. Questions involving contracts, ownership rights, assessments or other legal matters should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional. Structural and inspection findings should be evaluated by the appropriate licensed inspector, engineer, architect, contractor or other qualified professional. Buyers should also obtain property-specific insurance guidance from a qualified insurance professional and financing guidance from their mortgage lender or loan professional before making a purchasing decision.
Sources
- Florida Senate, 2026 Florida Statutes, Section 553.899, Mandatory Structural Inspections for Condominium and Cooperative Buildings
- Florida Senate, 2026 Florida Statutes, Section 718.112, Condominium Bylaws, Reserves and Structural Integrity Reserve Studies
- Florida Department of Business and Professional Regulation, Condominium Inspections and Structural Integrity Reserve Studies
- Florida Department of Business and Professional Regulation, Condominium and Cooperative FAQs
- Hunt Brothers Realty, What Should I Know Before Buying a Florida Condo?
- Hunt Brothers Realty, How to Read Florida Condo Documents Before Buying a Unit
- Hunt Brothers Realty, Buying a Condo in Florida in 2026: Questions to Ask
- Hunt Brothers Realty, What Condo Documents Should Buyers Review Before Closing?
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2694
- Anna Maria Island 93
- Bird Key 6
- Bradenton 242
- Buying a Home 1708
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1643
- Ellenton 9
- Englewood 16
- First Time Homebuyers 1832
- Foreclosures 4
- Home Selling 12
- Homeownership 1878
- Lakewood Ranch 37
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1821
- Market Updates & Trends 1321
- Mortgages & Financing 88
- Move-Up Buyers 24
- Neighborhood Guides 1449
- New Construction 47
- Palmetto 4
- Parrish 39
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1734
- Relocation to Florida 1762
- Safety Harbor 4
- Sarasota 163
- Sarasota - Downtown 175
- Selling a Home 149
- Siesta Key 95
- St. Petersburg 11
- Taxes and Homestead 5
- Tierra Verde 7
- Vacation & Second Homes 1927
- Venice 225
- Wellen Park 24
Recent Posts