How Long Does Mortgage Pre-Approval Take?
Mortgage pre-approval can sometimes be completed within a few hours or the same business day when a borrower has straightforward finances and quickly provides the information a lender needs. Other pre-approvals can take several business days or longer when the lender needs additional documentation or must evaluate self-employment, variable income, assets, debts or credit issues. There is no universal pre-approval turnaround time because lenders use different processes. The fastest approach is usually to gather financial documents before applying, respond promptly to lender requests and ask the lender what its particular pre-approval process includes.
Quick Answers About How Long Mortgage Pre-Approval Takes
Can You Get Mortgage Pre-Approved the Same Day?
Sometimes. A lender with an automated or digital process may be able to evaluate a straightforward borrower quickly when credit, income, employment and assets are readily available for review. Same-day pre-approval should not be treated as a guarantee because the required review depends on the lender and borrower's circumstances.
Can Mortgage Pre-Approval Take Several Days?
Yes. Several business days can be reasonable when documents need to be reviewed manually or the lender needs additional information. Self-employment, variable or commission income, multiple asset accounts, gift funds, credit questions and other financial circumstances can add review steps.
What Documents Do I Need for Mortgage Pre-Approval?
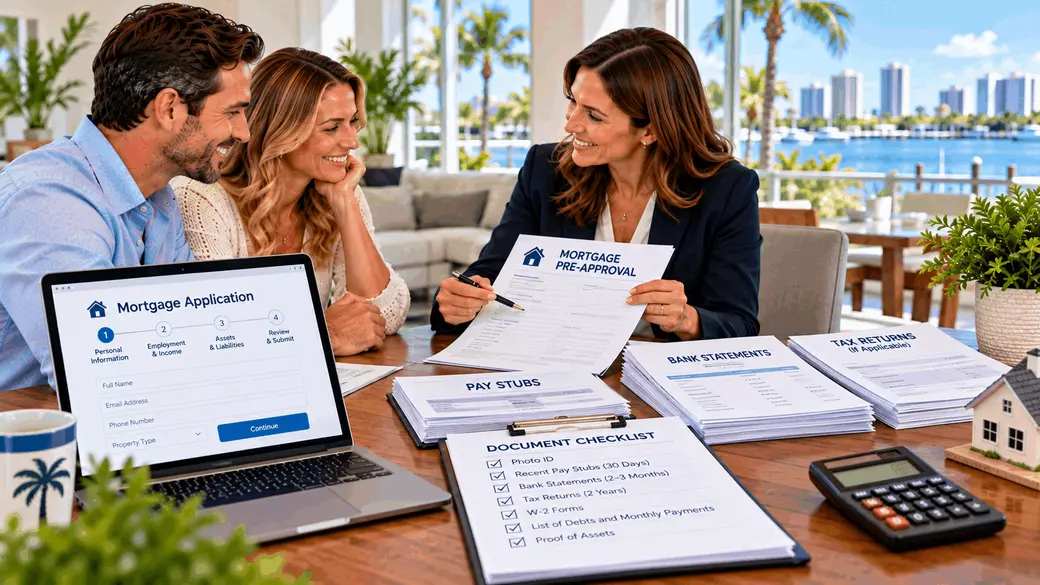
Depending on the lender and your circumstances, you may be asked for recent pay stubs, W-2s, bank and investment statements, identification and information about debts and employment. Self-employed borrowers or buyers using other income sources may need tax returns, business documents or additional records.
Does Mortgage Pre-Approval Require a Credit Check?
Lenders typically check credit before issuing a mortgage preapproval, according to the Consumer Financial Protection Bureau. Ask the lender when the credit inquiry occurs and what information will be reviewed as part of its particular process.
Does Pre-Approval Mean My Mortgage Is Approved?
No. Pre-approval is a preliminary lender assessment, not final mortgage approval. Final financing can still depend on updated borrower information, underwriting, the property, appraisal, title, insurance and other applicable loan requirements.
How Long Does a Mortgage Pre-Approval Last?
Preapproval letters commonly have expiration dates. CFPB says they typically expire in approximately 30 to 60 days, although lender practices can differ. Read Hunt Brothers Realty's guide to how long mortgage preapproval lasts for a closer look at expiration and updating a letter.
What Is Mortgage Pre-Approval?
The Consumer Financial Protection Bureau describes a preapproval letter as a statement from a lender that it is tentatively willing to lend money to a prospective borrower up to a specified amount.
A lender may evaluate information involving your income, assets, debts and credit record. The exact process matters because lenders do not all use the term "preapproval" in exactly the same way.
Some lenders conduct a detailed document review before issuing a letter. Others may use a more streamlined process and leave additional verification for later. Hunt Brothers Realty's mortgage prequalification versus preapproval guide explains why the terminology alone does not tell you how extensively a lender has reviewed your finances.
How Fast Can You Get Pre-Approved for a Mortgage?
There is no federal rule requiring every mortgage lender to complete pre-approval within a specific number of hours or days. The practical timeline depends on the lender's process and the complexity of the borrower's financial profile.
A useful way to think about timing is:
| Situation | Possible Timeline | What Can Affect It |
|---|---|---|
| Straightforward borrower with readily available information | Potentially within hours or the same business day | Lender process, credit review and availability of financial information |
| Application requiring document review | Potentially one or more business days | Document completeness and lender workload |
| More complex income, assets or credit | Potentially several business days or longer | Additional verification, explanations and underwriting questions |
These are practical timing illustrations, not guaranteed lender turnaround times. Ask each lender how long its own preapproval process normally takes and what must be submitted before the lender will issue a letter.
What Information Does a Lender Review for Pre-Approval?
A mortgage preapproval can involve several parts of your financial profile. CFPB explains that lenders preapprove borrowers by looking at income, assets, debts and credit records.
Depending on the lender, relevant information may include:
- Employment history
- Current income
- Bank and investment assets
- Existing monthly debts
- Credit history
- Expected down payment
- Source of funds when relevant
- Potential loan program and loan amount
Fannie Mae's consumer mortgage-document guidance notes that lenders may request documentation covering income sources and assets along with other personal financial information.
What Documents Can You Prepare Before Applying?
Having documents organized before contacting a lender can reduce delays if that lender requires them for its preapproval review.
Fannie Mae identifies examples of mortgage documentation that may be needed during the financing process, including:
- Recent pay stubs
- W-2 forms
- Tax returns when applicable
- 1099 forms when applicable
- Checking and savings account statements
- Retirement and investment account statements
- Photo identification
- Employment information
- Residential history
- Gift documentation if gift funds will be used
- Business information for self-employed borrowers
- Other documentation applicable to your income or financial circumstances
Do not assume every lender will request every item on this list at the preapproval stage. CFPB specifically notes that different lenders request different levels of information and documentation. Ask your mortgage professional for the lender's actual checklist.
Why Can One Pre-Approval Take Longer Than Another?
The more verification a lender needs before issuing its letter, the more opportunities there are for additional questions or documents.
Self-Employment
Self-employed borrowers may need tax returns, business records, profit-and-loss information or other documentation depending on the loan and lender. Income analysis can therefore involve more steps than reviewing a conventional salary.
Variable, Commission or Other Income
Fannie Mae underwriting standards require qualifying income to meet applicable stability, documentation and continuance requirements. A lender may therefore need additional history before determining how much variable income can be used for qualification.
Credit Questions
Credit history can affect both the financing options available and the time needed to evaluate them. A lender may need additional information about particular debts or credit events before issuing a meaningful preapproval.
For more context, read Hunt Brothers Realty's 2026 guide to credit scores for buying a house in Florida.
Large or Unusual Deposits and Gift Funds
When funds used for a transaction require documentation under the applicable loan program, a lender may ask for additional records. Buyers using gift funds should ask early what documentation their lender and loan program require.
Missing Documents
One of the simplest causes of delay is incomplete information. CFPB advises mortgage applicants to be responsive to lender requests and confirm that requested documents have been received.
Does Pre-Approval Always Require Documents?
Not every lender uses the same process. CFPB cautions that some lenders may base a preapproval letter largely on information provided by the borrower, while other lenders conduct a more detailed review and request supporting documents earlier.
This is why two letters both called "preapproval" may represent different levels of lender review.
Useful questions to ask include:
- Did you review my credit?
- Did you verify my income?
- Did you review my assets?
- What assumptions did you use?
- Are there documents you still need?
- What conditions could change the preapproval?
- How long is the letter valid?
Is Pre-Approval the Same as Prequalification?
Not necessarily. Some lenders use prequalification for a preliminary estimate based largely on information supplied by the prospective borrower and reserve preapproval for a more detailed review. Other lenders use the terms differently.
CFPB specifically warns consumers not to rely too heavily on the terminology because lender processes vary widely.
The practical question is not simply, "Am I prequalified or preapproved?" It is, "What did this lender actually review and verify before issuing my letter?"
See Mortgage Prequalification vs. Preapproval: What's the Difference? for a more detailed comparison.
Is the Three-Business-Day Loan Estimate Rule a Pre-Approval Deadline?
No. These are different parts of the mortgage process, and confusing them can create an inaccurate expectation about preapproval timing.
For covered mortgages, CFPB explains that a lender generally must provide a Loan Estimate within three business days after receiving six key pieces of application information:
- Your name
- Your income
- Your Social Security number so the lender can obtain credit information
- The property address
- An estimate of the property's value
- The desired loan amount
Receiving a Loan Estimate does not mean the lender has approved the mortgage. It also should not be interpreted as a federal requirement that every preapproval letter be issued within three business days.
Does Mortgage Pre-Approval Affect Your Credit?
A mortgage lender may obtain your credit report when evaluating preapproval. CFPB describes this type of lender credit check in connection with applying for mortgage credit as a hard inquiry, which can have a small effect on credit scores.
Mortgage shopping is treated differently from repeatedly applying for unrelated types of credit. CFPB's current guidance states that multiple mortgage lender credit checks within a 45-day window are recorded on the credit report as a single inquiry for scoring purposes.
Before authorizing credit checks, ask each lender how its process works. Credit scoring and mortgage qualification are borrower-specific issues, so questions about the effect on your individual credit profile should be discussed with the lender or an appropriate credit professional.
Should You Get Pre-Approved by More Than One Lender?
Comparing lenders can help you understand how different lenders view your financing profile and what loan programs may be available. CFPB's current mortgage-shopping guidance recommends obtaining at least three preapprovals.
A preapproval does not obligate you to use that lender for the eventual mortgage. Once you have a property and are applying for specific financing, compare the actual loan terms and applicable Loan Estimates rather than selecting a lender based only on which company issued a preapproval letter fastest.
Interest rate, annual percentage rate, points, lender fees, mortgage insurance, loan program, estimated payment, cash requirements and service can all matter when evaluating financing.
When Should You Get Pre-Approved?
A practical time to get preapproved is when you are moving from casual market research into serious home shopping and could realistically make an offer if you find the right property.
CFPB notes that many buyers wait until they are ready to shop seriously because lenders typically check credit and preapproval letters have expiration dates. There can also be value in starting earlier when you need time to understand credit, income documentation, down-payment options or other financing questions.
Read Hunt Brothers Realty's guide to getting preapproved before looking at houses for a more complete discussion of timing your home search.
Why Does Pre-Approval Matter When You Make an Offer?
A preapproval can demonstrate that a financed buyer has already taken meaningful steps toward arranging a mortgage. CFPB notes that sellers frequently require a preapproval letter before accepting an offer on a home.
That does not mean a preapproved buyer automatically has the strongest offer. A seller may evaluate purchase price, deposits, financing terms, contingencies, requested credits, closing date and other contract provisions.
The practical advantage is preparation. If you already have a current letter, you are less likely to be organizing basic financing information for the first time while trying to meet an offer deadline.
Does the Pre-Approval Amount Tell You How Much House You Should Buy?
No. A lender's maximum preapproval amount is not automatically the amount you should spend on a home.
CFPB emphasizes that the buyer is the person who must decide what is affordable. A comfortable budget may be below the maximum amount a lender is tentatively willing to finance.
Florida buyers should consider the complete housing expense, including:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- Flood insurance when applicable
- Mortgage insurance when applicable
- HOA or condominium assessments
- CDD or other non-ad valorem assessments when applicable
- Maintenance and reserves for future repairs
Buyers should discuss mortgage qualification and loan affordability with qualified mortgage professionals and make their own spending decisions based on their financial circumstances and priorities.
Does Pre-Approval Include Closing Costs?
Do not assume the amount shown on a preapproval letter represents all of the cash you will need to buy a home. The down payment and closing costs are separate concepts, and a buyer may also need funds for inspections, moving expenses and post-closing reserves.
For preliminary planning, Hunt Brothers Realty's 2026 Florida buyer closing-cost guide discusses the mortgage, title, government, prepaid and escrow expenses buyers may encounter.
Your actual mortgage costs and cash requirements depend on the borrower, lender, loan program, property and transaction. Obtain transaction-specific estimates from your mortgage and closing professionals before making financial decisions.
What Can Change After You Get Pre-Approved?
A preapproval reflects the information and assumptions available when the lender evaluates you. It is not permanent financing approval.
Changes that can require additional lender review may include:
- Changing jobs
- A change in income
- Opening new credit accounts
- Taking on additional debt
- Changes to available cash or assets
- Changing the down payment
- Changing loan programs
- Changes in interest rates
- The purchase price and characteristics of the selected property
- Property-specific underwriting requirements
Before making significant financial changes while pursuing a mortgage, ask your lender how the proposed change could affect your individual qualification.
How Can You Make the Pre-Approval Process Faster?
You cannot control the lender's workload or underwriting procedures, but you can reduce avoidable delays.
- Ask for the lender's document checklist before applying
- Gather recent income and asset documents in advance
- Provide complete documents rather than partial pages
- Respond promptly when the lender asks a question
- Disclose relevant income, debt and asset information accurately
- Ask what additional documentation applies if you are self-employed
- Ask what documentation is needed for gift funds or other sources of cash
- Confirm that the lender received the documents you submitted
Accuracy is more important than speed. A quickly issued letter based on incomplete or incorrect information can create problems later if the lender's subsequent verification produces different results.
Can You Start Looking at Homes While Waiting for Pre-Approval?
Yes. You can research communities, browse listings and attend open houses while learning about financing. The more important issue is being prepared when you become serious enough to make an offer.
For a financed buyer, having a current preapproval before serious house hunting can help connect the property search with a realistic financing range and reduce the chance that financing preparation delays an offer.
Buyers researching Sarasota, Venice and Florida Gulf Coast real estate can explore communities with Hunt Brothers Realty while working with qualified mortgage professionals on financing.
The Bottom Line: How Long Should You Expect Mortgage Pre-Approval to Take?
A straightforward mortgage preapproval may sometimes be completed within hours or the same business day, while a more complex financial profile can require several business days or longer. There is no universal lender deadline for issuing a preapproval letter.
The best way to estimate your timeline is to ask the lender exactly what it reviews before issuing a letter, gather the requested information in advance and respond quickly to follow-up questions.
Most importantly, remember that speed is not the same as certainty. A mortgage preapproval is an important home-shopping tool, but it is not final loan approval and does not guarantee financing for a particular property.
Prepare for Your Home Search With Hunt Brothers Realty
Hunt Brothers Realty can help buyers connect their home-search goals with current Sarasota, Venice and Florida Gulf Coast real estate opportunities. For financing questions and mortgage qualification, buyers should work directly with qualified mortgage professionals who can evaluate their individual financial circumstances.
Continue with Should I Get Preapproved Before Looking at Houses?, Mortgage Prequalification vs. Preapproval, How Long Does a Mortgage Preapproval Last?, and the 2026 Florida Buyer Closing Costs Guide.
You can also explore Florida Gulf Coast communities or contact Hunt Brothers Realty when you are ready to discuss your property search.
This article provides general real estate and educational information only and is not individualized financial, lending, legal, tax, insurance or other professional advice. Mortgage qualification, documentation, credit requirements, interest rates, loan programs and preapproval procedures depend on the individual borrower, lender and transaction. Buyers should have qualified mortgage professionals evaluate their specific financial circumstances and verify current loan requirements before making financing or purchasing decisions.
Sources
- Consumer Financial Protection Bureau, Get a Preapproval Letter
- Consumer Financial Protection Bureau, Prequalification vs. Preapproval
- Consumer Financial Protection Bureau, When Lenders Check Credit
- Consumer Financial Protection Bureau, Mortgage Credit Inquiries
- Consumer Financial Protection Bureau, Shopping for a Mortgage
- Consumer Financial Protection Bureau, Information Required for a Loan Estimate
- Fannie Mae, Documents You Need to Apply for a Mortgage
- Freddie Mac, How Do I Get Pre-Approved for a Mortgage?
- Hunt Brothers Realty, Should I Get Preapproved Before Looking at Houses?
- Hunt Brothers Realty, How Long Does a Mortgage Preapproval Last?
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2112
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1171
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1088
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1280
- Foreclosures 5
- Home Selling 6
- Homeownership 1304
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1244
- Market Updates & Trends 766
- Mortgages & Financing 48
- Move-Up Buyers 22
- Neighborhood Guides 879
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1160
- Relocation to Florida 1200
- Safety Harbor 3
- Sarasota 81
- Sarasota - Downtown 162
- Selling a Home 146
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1353
- Venice 193
- Wellen Park 19
Recent Posts