Should I Find a Realtor or Get Pre-Approved First?
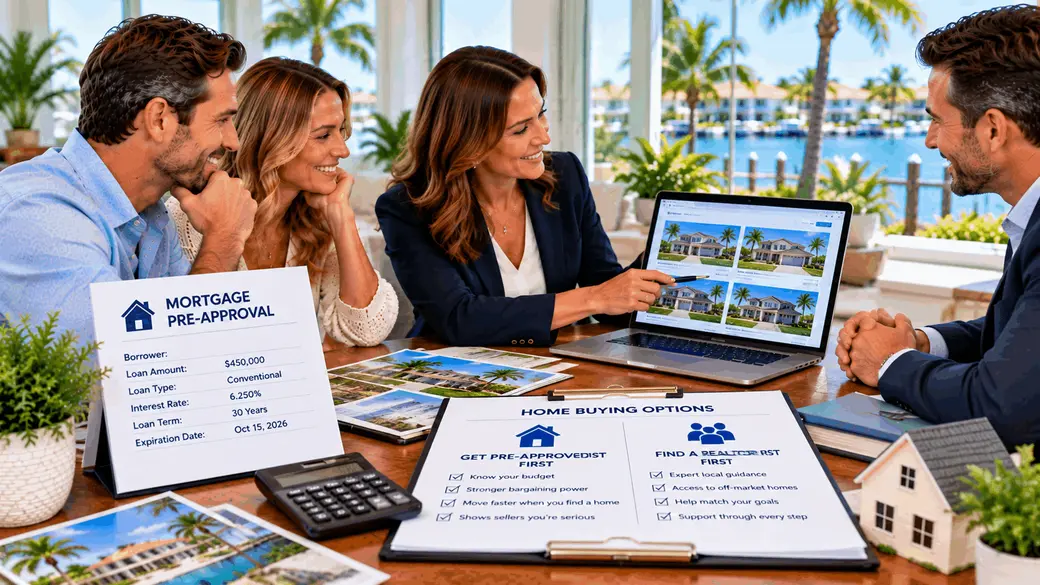
You do not have to choose between finding a Realtor and getting mortgage pre-approved as completely separate steps. For most financed buyers, a practical approach is to interview or select a real estate professional early while beginning the mortgage conversation at roughly the same time, then obtain meaningful pre-approval before serious home touring and before you are ready to make an offer. Your real estate professional helps organize the property search and transaction, while a qualified mortgage professional determines financing. Getting both relationships established early can make the home search more focused and reduce avoidable delays once you find a property you want to pursue.
Quick Answers About Finding a Realtor or Getting Pre-Approved First
Should I Find a Realtor Before Getting Pre-Approved?
You can. Talking with a real estate professional early can help you understand neighborhoods, property types, the buying process and what information you should gather before serious shopping. You do not need mortgage pre-approval simply to interview a Realtor or begin discussing your plans.
Should I Get Pre-Approved Before Seriously Looking at Houses?
For most buyers using mortgage financing, yes. Pre-approval can establish a preliminary financing range, uncover financing questions earlier and provide a lender letter that may be important when you are ready to make an offer.
Can a Realtor Help Me Find a Mortgage Lender?
A real estate professional may be able to identify mortgage professionals buyers can consider, but you remain free to shop for lenders and compare financing. CFPB specifically notes that getting pre-approved does not commit you to using the lender that issued the letter.
Can I Look at Homes Before Getting Pre-Approved?
Yes. You can browse listings, research communities and attend open houses before obtaining mortgage pre-approval. The more important point is to have financing preparation underway before serious touring and before you find a home you are ready to pursue.
Do I Need a Buyer Agreement Before a Realtor Shows Me a House?
Under current industry practice requirements described by Florida Realtors, an MLS participant working with a buyer generally must have a written buyer agreement before touring a home. An unrepresented consumer simply attending an open house hosted by the listing side is treated differently. Because buyer agreements are contracts, review the actual agreement, services, duration, compensation terms and termination provisions before signing.
What Is the Best Order for a First-Time Buyer?
A useful sequence is to establish your personal budget, interview a real estate professional, speak with qualified lenders, obtain pre-approval if financing, complete the applicable buyer representation agreement and then begin serious property tours. These steps can overlap rather than occurring one at a time.
So, Which Should Come First: the Realtor or the Pre-Approval?
If you are asking which professional you are allowed to contact first, either one is fine. If you are asking what should happen before serious home shopping, you generally want both your real estate representation and preliminary financing substantially organized.
There is no need to wait for a preapproval letter before interviewing real estate professionals. In fact, an early buyer consultation can help you understand the local market and clarify the kinds of properties you may want to discuss with a lender.
At the same time, it usually makes little sense for a financed buyer to tour large numbers of homes without understanding whether the financing supports the intended search range.
That is why these steps work best in parallel.
Why Can Finding a Realtor Early Be Helpful?
An early conversation with a real estate professional can help turn a general idea of buying a home into a more organized property search.
A buyer consultation may help you think through:
- Where you want to live
- Your preferred property type
- Essential versus optional home features
- Your expected purchase timeline
- Whether you are considering a condominium, villa, townhome or detached home
- Whether HOA or condominium assessments may be relevant
- Which communities fit your lifestyle priorities
- How the offer and purchase process generally works
For Florida buyers, this early property discussion can also identify issues worth raising with a lender before the search becomes highly specific.
Why Should Mortgage Pre-Approval Happen Before Serious House Hunting?
Mortgage pre-approval connects your property search with the financing a lender is tentatively willing to consider.
The Consumer Financial Protection Bureau describes a preapproval letter as a statement that a lender is tentatively willing to lend up to a specified amount. It is based on assumptions and is not a guaranteed loan offer.
Getting pre-approved before serious shopping can help you:
- Establish a preliminary financing range
- Identify potential mortgage issues earlier
- Discuss appropriate mortgage programs
- Estimate down-payment needs
- Focus the property search
- Prepare financial documentation before an offer creates deadlines
- Have financing documentation available when a seller requests it
CFPB notes that sellers frequently require a preapproval letter before accepting an offer. That makes preapproval particularly useful before you reach the point where you are prepared to compete for a specific home.
For more detail, see Hunt Brothers Realty's guide to getting pre-approved before looking at homes in Florida.
Can You Contact a Realtor Without a Pre-Approval Letter?
Yes. A mortgage preapproval is not a prerequisite for having an initial conversation with a real estate professional.
You may still be at the stage of determining whether you want to buy, comparing communities or learning what different property types cost. Those are reasonable topics for an early buyer consultation.
A productive first conversation should not require you to pretend that your financing is farther along than it actually is. Tell the real estate professional whether you have spoken with a lender, whether you expect to finance the purchase and approximately when you hope to buy.
Can You Research Homes Before Getting Pre-Approved?
Yes. There is a meaningful difference between researching the housing market and becoming an active offer-ready buyer.
Before preapproval, you can:
- Browse online listings
- Compare communities
- Research property types
- Learn what different price ranges offer
- Attend open houses
- Develop your priorities
Buyers researching Florida's Gulf Coast can also explore communities with Hunt Brothers Realty before narrowing the search to individual properties.
Why Is Waiting Until You Find the Perfect Home to Contact a Lender Risky?
Waiting can compress several important financing steps into the moment when you are trying to make an offer.
A lender may need financial information and supporting documentation before issuing a useful preapproval letter. Questions about income, credit, debts, assets or loan programs may also emerge during that review.
Discovering those questions before finding a home gives you more time to understand your options. Discovering them when you want to submit an offer can create unnecessary pressure.
What Does a Realtor Do That a Mortgage Lender Does Not?
The real estate professional and mortgage professional have different roles, which is another reason these relationships can develop at the same time.
On the real estate side, services may include helping you:
- Define your property search
- Evaluate available listings
- Arrange property tours
- Research relevant property information
- Prepare and present an offer
- Negotiate within the scope of the brokerage relationship
- Coordinate transaction milestones
- Navigate the real estate process through closing
The lender separately evaluates your mortgage financing. Your real estate professional should not substitute for a qualified lender when the question involves individual mortgage qualification, rates, loan programs or underwriting.
What Does a Mortgage Professional Do That a Realtor Does Not?
A qualified mortgage professional evaluates the financing side of your purchase based on the lender's requirements and your individual circumstances.
Depending on the lender and loan, that can involve reviewing:
- Income and employment
- Credit history
- Existing debts
- Assets
- Down-payment funds
- Potential mortgage programs
- Estimated mortgage payments
- Property-specific financing requirements once a home is selected
Mortgage qualification is individualized financial and lending work. Buyers should rely on qualified mortgage professionals for borrower-specific financing decisions.
Can Your Realtor Tell You How Much House You Can Afford?
A real estate professional can help you understand what homes are available at different price points and identify property-related ownership expenses, but mortgage qualification should come from a qualified lender.
Even a lender's preapproval amount should not automatically become your personal home-buying budget. CFPB emphasizes that the buyer ultimately decides how much they are comfortable spending.
That distinction becomes important because the same purchase price can produce very different monthly ownership costs depending on the property.
Why Does Pre-Approval Matter So Much for Florida Homebuyers?
Florida buyers should evaluate more than the mortgage principal and interest when deciding what price range makes sense.
Depending on the property, recurring costs may include:
- Property taxes
- Homeowners insurance
- Flood insurance when applicable
- Mortgage insurance when applicable
- HOA assessments
- Condominium assessments
- Special assessments
- CDD or other non-ad valorem assessments when applicable
- Maintenance and repairs
A lender's preliminary assumptions may not match the actual insurance premium, taxes or association expense for the home you ultimately select. Your real estate professional can help identify property-specific costs to investigate, while your lender determines how those expenses affect mortgage qualification.
Insurance availability, premiums, deductibles and coverage can vary substantially by property. Buyers should obtain property-specific quotes and review coverage with a qualified insurance professional before making a purchasing decision.
What If You Are Buying a Florida Condo?
Getting the real estate and financing sides coordinated early can be particularly useful for condominium buyers because borrower qualification is only part of the financing question.
Depending on the loan program and condominium, the lender may need to evaluate the project as well as the borrower. Association assessments, insurance, project characteristics and other factors can affect financing.
A buyer can therefore be pre-approved personally and still encounter a condominium that does not work with the intended mortgage program. Before making a financing-dependent offer, ask the lender about the specific condominium and any project-level requirements.
Do You Need a Written Buyer Agreement Before Touring Homes?
Current buyer-representation practices make the consultation with your real estate professional more important than it once may have seemed.
Florida Realtors explains that an MLS participant who is working with a buyer generally needs a written buyer agreement before touring a home. The requirement distinguishes an agent providing services for a buyer from a listing agent simply providing an unrepresented consumer access to the listing side's open house.
The agreement should not be treated as an insignificant formality. Florida Realtors emphasizes that buyer agreements are contracts.
Before signing, understand the specific agreement you are being offered, including:
- Services being provided
- Whether the relationship is exclusive
- Geographic or property scope
- Duration
- Broker compensation
- Buyer payment obligations, if any
- Termination provisions
Compensation and agreement terms can be negotiable and vary by brokerage and transaction. Questions about contractual rights or legal obligations under a buyer agreement should be reviewed with a qualified Florida real estate attorney or other appropriate legal professional.
Can You Attend an Open House Without a Buyer Agreement?
An unrepresented buyer can generally attend an open house being hosted on behalf of the seller without automatically entering a buyer representation agreement with the listing side. Florida Realtors specifically distinguishes that situation from an MLS participant who is already working with a buyer and takes that buyer to the property.
Be clear about whom the real estate professional at the open house represents and do not assume that attending an open house creates representation for you.
Should Your Realtor Choose Your Mortgage Lender?
No. A real estate professional may provide names of mortgage professionals or companies buyers can investigate, but the financing decision belongs to the buyer.
CFPB advises buyers to shop for mortgage financing and notes that receiving a preapproval does not obligate the buyer to ultimately use that lender.
Compare current loan options, rates, fees and qualification requirements with qualified mortgage professionals before choosing financing. Your Realtor can coordinate transaction information with the lender when appropriate, but should not make the individualized lending decision for you.
What If You Already Have a Realtor but Are Not Pre-Approved?
That is not inherently a problem. Tell your real estate professional where you are in the financing process and begin speaking with qualified lenders before the property search becomes offer-driven.
Your Realtor can continue helping you refine locations, property types and priorities while you investigate financing. Once preapproval is available, the search can be aligned more closely with both your personal budget and the lender's preliminary financing range.
What If You Are Already Pre-Approved but Do Not Have a Realtor?
You can begin interviewing real estate professionals immediately. Bring the relevant financing information to your buyer consultation so the property search can start with realistic assumptions.
Also check the expiration date on your preapproval letter. CFPB says preapproval letters typically have expiration periods of about 30 to 60 days, although the actual period depends on the lender.
If the letter is approaching expiration, ask your mortgage professional what must be updated before relying on it for an offer.
What If You Are a Cash Buyer?
A true cash buyer does not need mortgage preapproval because the purchase is not dependent on obtaining mortgage financing. The buyer may instead need to demonstrate available funds when appropriate to the transaction.
Cash buyers still benefit from organizing their real estate representation, property search and due diligence before making an offer. Paying cash does not eliminate questions involving inspections, title, insurance, association documents, surveys, property condition or other transaction-specific matters.
For more information, read Hunt Brothers Realty's 2026 guide to cash buyers versus financed buyers in Florida.
What Is the Best Step-by-Step Order for a Financed Homebuyer?
The process is not perfectly linear, but this sequence works well for many financed buyers:
- Establish your personal budget. Decide what level of monthly housing expense and upfront cash feels appropriate before focusing on a lender's maximum amount.
- Interview a real estate professional. Discuss your goals, location, timeline, property type and how buyer representation works.
- Speak with qualified mortgage professionals. Learn about potential financing and what documentation is needed.
- Obtain meaningful pre-approval. Understand what the lender reviewed, the assumptions used and what conditions remain.
- Review and execute the appropriate buyer agreement before touring when required. Understand the contract before signing it.
- Begin serious property tours. Focus on homes that fit both your financing and personal budget.
- Verify property-specific costs. Investigate taxes, insurance, HOA or condominium expenses and other relevant ownership costs.
- Coordinate with the lender before an offer when appropriate. Make sure the specific property and proposed terms remain consistent with the financing plan.
- Prepare the offer with your real estate professional. Evaluate price, deposits, contingencies, timing and other terms based on the specific transaction.
What Questions Should You Ask a Realtor Before Choosing One?
The first real estate professional you speak with does not automatically have to become the professional you hire. A buyer consultation is an opportunity to understand the proposed working relationship.
Useful questions include:
- Which areas and property types do you regularly work with?
- What services will you provide during the home search?
- What buyer agreement do you use?
- How long does the agreement last?
- Is it exclusive?
- How is your brokerage compensated?
- Could I have a payment obligation under the agreement?
- How do you help buyers evaluate HOA and condominium information?
- How do you communicate during an active search?
- What happens when I find a property I want to offer on?
What Questions Should You Ask a Lender Before Serious Home Shopping?
A useful preapproval is more than a number at the top of a letter. You should understand the assumptions behind it.
- What information did you verify?
- Which mortgage programs appear available to me?
- What down payment did you assume?
- What interest-rate assumption did you use?
- What might my estimated payment look like at my target price?
- How could taxes and insurance affect qualification?
- How will HOA or condominium assessments affect the calculation?
- Are there property types I should discuss with you before making an offer?
- How much cash might I need for the transaction?
- How long is the preapproval letter valid?
- What financial changes should I report before closing?
Because lenders use the terms differently, buyers should also ask what the lender means by prequalification versus preapproval. Hunt Brothers Realty's mortgage prequalification versus preapproval guide explains why the actual review matters more than the label.
The Bottom Line: Realtor First or Pre-Approval First?
You can contact a Realtor before getting pre-approved, and doing so can be useful when you want help understanding the market, communities and buying process. You can also begin with a lender if financing is your biggest uncertainty.
For most financed buyers, however, the strongest answer is not Realtor first or lender first. It is to establish both relationships early and have the financing substantially organized before serious home touring and offer writing.
Your real estate professional helps you find and evaluate properties and navigate the real estate transaction. Your mortgage professional evaluates your individual financing. Keeping those roles coordinated can help you search for homes that fit both your real estate goals and your actual financing circumstances.
Start Your Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty helps buyers organize the real estate side of a Florida Gulf Coast home purchase, from defining the search and comparing communities to evaluating properties, preparing offers and coordinating transaction milestones.
Continue with Should I Get Pre-Approved Before Looking at Homes in Florida?, Mortgage Prequalification vs. Preapproval, What Credit Score Do I Need to Buy a House in Florida?, and Cash Buyer vs. Financed Buyer in Florida.
You can also explore Florida Gulf Coast communities or contact Hunt Brothers Realty to discuss your home search.
This article provides general real estate and educational information only and is not individualized legal, financial, lending, tax, insurance or other professional advice. Mortgage qualification, loan programs, rates and documentation depend on the individual borrower and lender. Buyer representation agreements are contracts, and their terms vary. Buyers should review mortgage decisions with qualified mortgage professionals and consult an appropriate Florida real estate attorney regarding individualized legal questions or contract rights before making decisions that require professional guidance.
Sources
- Consumer Financial Protection Bureau, Get a Preapproval Letter
- Florida Realtors, NAR Settlement and Buyer Agreement FAQs
- Florida Realtors, Mastering Buyer Representation in Today's Market
- Hunt Brothers Realty, Should I Get Pre-Approved Before Looking at Homes in Florida?
- Hunt Brothers Realty, Mortgage Prequalification vs. Preapproval
- Hunt Brothers Realty, Cash Buyer vs. Financed Buyer in Florida
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2112
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1171
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1088
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1280
- Foreclosures 5
- Home Selling 6
- Homeownership 1304
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1244
- Market Updates & Trends 766
- Mortgages & Financing 48
- Move-Up Buyers 22
- Neighborhood Guides 879
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1160
- Relocation to Florida 1200
- Safety Harbor 3
- Sarasota 81
- Sarasota - Downtown 162
- Selling a Home 146
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1353
- Venice 193
- Wellen Park 19
Recent Posts