How Much Does It Really Cost to Own a Waterfront Home in Florida?
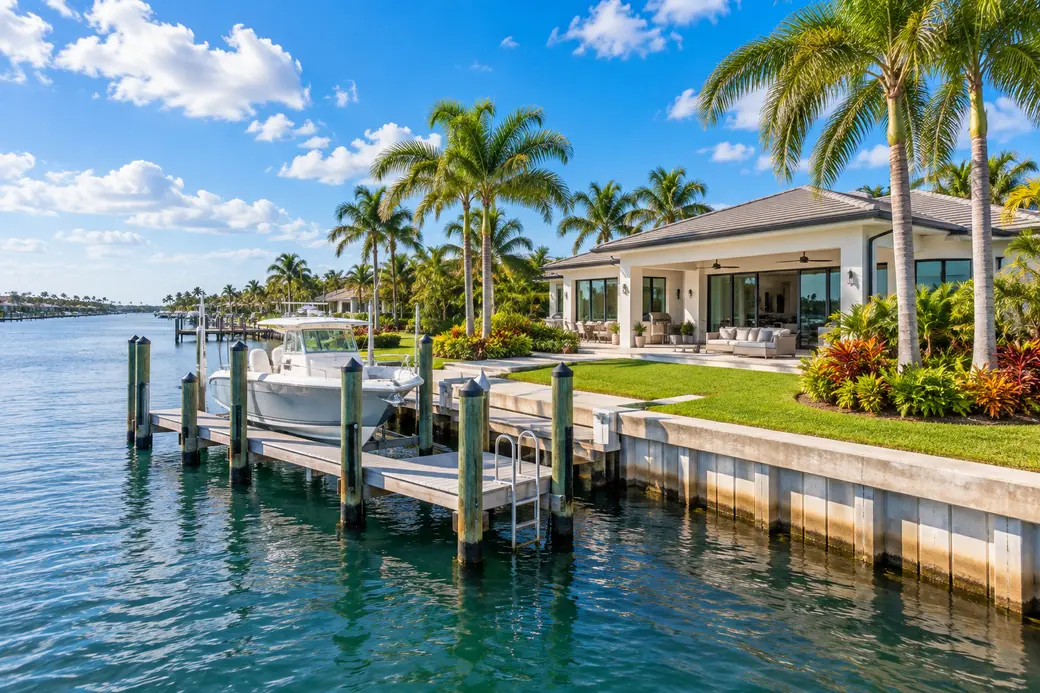
The real cost of owning a waterfront home in Florida extends well beyond the mortgage and property taxes. Depending on the property, owners may need to budget for homeowners and flood insurance, seawall and dock maintenance, boat-lift service, salt and moisture exposure, landscaping, storm preparation, association expenses and eventual capital projects. These costs can vary substantially between two homes with similar purchase prices. Buyers considering waterfront property in Florida should therefore evaluate the total cost of ownership for the individual property before deciding what is affordable.
Quick Answers About the Cost of Owning a Waterfront Home in Florida
Does a Waterfront Home Cost More to Maintain?
It can. Florida waterfront homes may have docks, seawalls, boat lifts and other infrastructure that inland properties do not have. Salt, moisture, wind and storm exposure can also increase maintenance demands on exterior building components and waterfront equipment.
How Much Is Insurance on a Florida Waterfront Home?
There is no reliable statewide price that applies to every waterfront property. Premiums and coverage availability can differ based on the specific structure, location, elevation, construction characteristics, roof, coverage selected and other underwriting factors. Buyers should obtain property-specific homeowners, wind and flood insurance information from a qualified Florida insurance professional before making a purchasing decision.
Does Homeowners Insurance Cover Flooding?
Standard homeowners insurance generally does not cover flooding from rising water or storm surge. Flood insurance is a separate coverage consideration, and requirements can depend on the property, lender and insurance situation.
Who Pays to Maintain a Seawall?
Responsibility depends on the property and ownership arrangement. A seawall may be an individual owner's responsibility, an association responsibility or subject to another arrangement. Buyers should verify ownership, maintenance obligations, condition and available repair history rather than assuming responsibility based on the property's appearance.
Do Docks and Boat Lifts Add Ongoing Expenses?
Yes, when the property includes them. Pilings, decking, hardware, electrical service, water connections and lift components can require inspection, maintenance and eventual repair or replacement. Saltwater exposure can make regular monitoring particularly important.
Is a Waterfront Condo Cheaper to Maintain Than a Waterfront House?
The owner's direct maintenance responsibilities may be different, but the expenses do not disappear. Condominium fees can fund building maintenance, insurance and common waterfront infrastructure, depending on the association. Buyers should review current fees, reserves, assessments, insurance responsibilities and governing documents for the specific condominium.
What Is the Biggest Financial Mistake Waterfront Buyers Make?
One major mistake is treating the purchase price and mortgage payment as the complete affordability calculation. Insurance, flood exposure, seawalls, docks, association expenses and future capital projects can materially change the real cost of ownership.
What Costs Should Be in a Florida Waterfront Home Budget?
A realistic waterfront budget should separate predictable recurring expenses from less frequent capital projects. The exact list depends on whether the property is Gulf-front, bayfront, Intracoastal, riverfront, canal-front or another type of waterfront.
- Mortgage principal and interest, when financed
- Property taxes
- Homeowners and applicable wind-related insurance
- Flood insurance when applicable or selected
- Seawall inspection, maintenance and eventual repair or replacement
- Dock maintenance and repairs
- Boat-lift inspection, service and repairs
- Pool and landscaping expenses when applicable
- Exterior maintenance associated with coastal exposure
- Storm preparation and post-storm maintenance
- HOA, condominium or other association expenses when applicable
- Long-term capital reserves for waterfront infrastructure and major building systems
The important point is that there is no single "waterfront premium" that can simply be added to an inland home's annual budget. A newer elevated residence with recently completed waterfront infrastructure can have a very different expense profile from an older home with an aging seawall, dock and building systems.
How Much Should You Budget for Waterfront Insurance?
Insurance should be priced for the individual property rather than estimated using a generic percentage of the purchase price. A seller's existing premium also should not be assumed to represent what a new owner will pay. Coverage, underwriting conditions and the buyer's insurance circumstances may differ.
Waterfront buyers may need to investigate homeowners coverage, wind-related coverage and separate flood insurance. Citizens Property Insurance Corporation states that its standard policies do not cover storm surge and other flood losses. Citizens also has phased flood-insurance requirements for many personal residential policies that include wind coverage. In 2026, its requirement generally extends to qualifying properties with a dwelling replacement cost of $400,000 or more outside the Special Flood Hazard Area, as well as qualifying properties within designated Special Flood Hazard Areas. Different rules and exemptions can apply depending on policy type.
Insurance availability, premiums, deductibles, limits and exclusions can vary substantially by property. Before committing to a waterfront purchase, obtain current quotes for the actual address and have a qualified insurance professional explain what is and is not covered. Hunt Brothers Realty's guide to when Florida buyers should shop for homeowners insurance explains why this research is useful early in the purchase process.
How Can a Seawall Affect the Real Cost of Ownership?
A seawall can become one of the most important capital items associated with a waterfront property. Buyers should investigate its age, construction, visible condition, repair history and who is responsible for maintaining it. Cracking, leaning, separation, deterioration or evidence of soil loss can justify further evaluation.
There is no responsible universal estimate for seawall repair or replacement. Cost can depend on dimensions, material, site access, engineering, permitting, environmental requirements, existing conditions and the scope of work. A property-specific evaluation from an appropriate qualified contractor, engineer or waterfront specialist is more useful than a generic online cost estimate.
Before purchasing, buyers can request available permits, invoices, engineering information, warranties and previous repair documentation. Hunt Brothers Realty's guide to Florida Gulf Coast seawalls, docks and flood zones covers additional waterfront due-diligence questions.
What Does a Dock or Boat Lift Really Cost to Own?
A private dock and boat lift create convenience for a boating-oriented property, but they also create additional systems to maintain. Dock pilings, decking, fasteners, electrical components, lighting, water connections and lift equipment can deteriorate or require service over time.
Buyers should also distinguish maintenance costs from potential modification or replacement costs. If the existing lift cannot accommodate the intended boat, or if a dock requires substantial work, the future expense can become part of the real acquisition budget.
Existing waterfront improvements should not automatically be assumed to be permitted or suitable for future modification. Permitting and environmental requirements can depend on the location and proposed work. Buyers planning dock, lift or shoreline improvements should verify feasibility and requirements with the appropriate local government, Florida environmental authority, marine contractor or other qualified professional before relying on a planned project.
Why Does Saltwater Exposure Matter to Your Maintenance Budget?
Florida waterfront property can expose building components and equipment to salt, moisture, intense sun, wind and storms. The degree of exposure varies by location, but coastal conditions can affect exterior finishes, metal components, railings, windows, doors, mechanical equipment, docks and outdoor electrical systems.
Maintenance therefore should not be viewed only as an annual percentage of the home's purchase price. The age, materials and condition of the individual property are more informative. A detailed inspection can help identify components that may need near-term attention, while specialists can evaluate systems outside the scope of a general home inspection.
Owners and buyers in the Sarasota area can also review Hunt Brothers Realty's Sarasota waterfront home maintenance guide for a closer look at coastal maintenance issues.
How Do Property Taxes Fit Into Waterfront Ownership Costs?
Property taxes are another recurring expense, but buyers should not assume that the seller's current tax bill will become their future tax bill. Florida property taxation involves assessed values, exemptions and other property-specific circumstances, so historical taxes are not necessarily a reliable estimate of a buyer's future obligation.
Tax consequences and future property-tax obligations depend on the individual owner and property. Buyers should use current official county property information as a starting point and consult the appropriate property appraiser, tax authority or qualified tax professional regarding their specific circumstances.
Does Flood Zone Determine What a Waterfront Home Will Cost to Own?
Flood-zone designation is important, but it does not provide a complete ownership-cost or flood-risk analysis. Elevation, building characteristics, drainage, proximity to tidal water, previous flooding information and insurance requirements can also matter. Properties outside designated high-risk flood areas can still experience flooding.
Buyers should investigate the current FEMA flood information for the specific address and review available elevation documentation when relevant. Hunt Brothers Realty's questions to ask before buying a Florida coastal home provides a broader checklist for evaluating flood, insurance and storm-related considerations.
What About Storm Preparation and Post-Storm Expenses?
Storm preparation can become part of the practical ownership budget for Florida waterfront property. Depending on the home, owners may have expenses related to shutters or other protective systems, securing outdoor items, landscaping, boats and waterfront equipment, as well as inspections or cleanup after significant weather events.
After a storm, the residence is not the only component that may require evaluation. Docks, lifts, seawalls, landscaping, electrical systems and shoreline areas can experience damage independently of the house. Insurance coverage for individual components should be confirmed with the owner's insurance professional rather than assumed.
Are Waterfront Condominiums Different?
Yes. With a waterfront condominium, many building and waterfront expenses may be managed through an association rather than paid directly by the unit owner. That does not make those expenses irrelevant. They can be reflected in regular assessments, special assessments, reserves and other association financial obligations.
A condominium buyer should investigate current association fees, reserves, assessments, insurance responsibilities, structural information and responsibility for waterfront infrastructure. Boat-slip rights, parking, storage and marina expenses can also be unit-specific and should not be assumed from a listing description or the existence of a community marina.
Association documents and financial information should be reviewed carefully. Questions involving legal rights, ownership, assessments or contractual obligations should be reviewed with the appropriate association, qualified Florida real estate attorney or other relevant professional before a purchasing decision is made.
How Can Buyers Estimate the True Annual Cost Before Purchasing?
The most useful approach is to build a property-specific ownership budget before the applicable due-diligence deadlines expire. Separate recurring annual expenses from major capital items that may arise over a longer ownership period.
- Insurance: Obtain actual homeowners, wind and flood quotes appropriate to the property.
- Taxes: Research current property information and investigate how a purchase may affect future taxes.
- Seawall: Determine age, condition, maintenance responsibility and potential future work.
- Dock and lift: Evaluate condition, permits, capacity and anticipated service or repairs.
- Home condition: Investigate roof, windows, doors, HVAC, electrical, plumbing and other major systems.
- Association expenses: Review current fees, reserves, assessments and applicable responsibilities.
- Coastal maintenance: Account for the property's materials, age and actual environmental exposure.
- Capital reserve: Consider how future waterfront infrastructure and major home components will be funded.
Inspection findings should be evaluated with the appropriate licensed inspector, contractor, structural engineer, marine contractor or other qualified specialist. Estimates for repairs and replacements should be based on the actual property and proposed scope of work.
Is a Florida Waterfront Home Worth the Additional Cost?
Whether the additional ownership costs make sense depends on the property, the buyer's finances and how much value the buyer places on the specific waterfront features. Direct boating access, Gulf frontage, bay views and a private dock offer different benefits, and they can come with different responsibilities.
For buyers interested in the Sarasota area, waterfront options range from barrier-island properties to bayfront condominiums and canal-front boating homes. Hunt Brothers Realty's guide to the best Sarasota areas for waterfront living explains how different locations can support different waterfront lifestyles. Buyers can also explore Florida Gulf Coast communities to compare Sarasota, Siesta Key, Longboat Key, Lido Key, Bird Key, Casey Key and other coastal markets.
The Bottom Line on Florida Waterfront Ownership Costs
The true cost of a Florida waterfront home is the purchase and financing cost plus the expenses required to insure, maintain and preserve both the residence and its waterfront infrastructure. Insurance, seawalls, docks, boat lifts, coastal maintenance, storm exposure, taxes and association obligations can make two similarly priced properties very different financial commitments.
The best time to understand those differences is before purchasing. A property-specific budget supported by current insurance quotes, inspections, association information, permit research and specialist evaluations can help a buyer understand what the waterfront lifestyle will actually cost.
Considering a Waterfront Home on Florida's Gulf Coast?
Hunt Brothers Realty can help buyers compare waterfront properties based on more than the view. When evaluating Sarasota and Florida Gulf Coast waterfront real estate, understanding the type of water access, waterfront infrastructure and property-specific ownership considerations can help focus the search on homes that fit both your lifestyle and budget.
Important: This article provides general real estate information for educational purposes and is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction, title, permitting or other professional advice. Insurance costs and coverage should be verified with a qualified insurance professional. Tax matters should be reviewed with the appropriate tax professional or government authority. Seawalls, docks, structures and other property conditions should be evaluated by appropriately qualified inspectors, contractors, engineers or other specialists, and legal or ownership questions should be reviewed with a qualified Florida real estate attorney or other appropriate professional.
Sources
- Citizens Property Insurance Corporation, Flood Insurance Requirements
- Citizens Property Insurance Corporation, Flood and Storm Surge Information
- Hunt Brothers Realty, Buying Waterfront Property in Florida: 10 Things to Know Before You Buy
- Hunt Brothers Realty, A Buyer's Guide to Waterfront Homes on Florida's Gulf Coast
- Hunt Brothers Realty, Waterfront Home Maintenance in Sarasota
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 1526
- Anna Maria Island 68
- Bird Key 3
- Bradenton 102
- Buying a Home 669
- Casey Key 2
- Clearwater 5
- Condos & HOA Living 575
- Ellenton 4
- Englewood 5
- First Time Homebuyers 748
- Foreclosures 3
- Homeownership 729
- Lakewood Ranch 15
- Lido Key 24
- Longboat Key 65
- Luxury/Waterfront Properties 666
- Market Updates & Trends 334
- Mortgages & Financing 33
- Move-Up Buyers 20
- Neighborhood Guides 486
- New Construction 26
- Palmetto 2
- Parrish 4
- Port Charlotte 7
- Punta Gorda 11
- Real Estate Investing 600
- Relocation to Florida 650
- Safety Harbor 2
- Sarasota - Downtown 133
- Selling a Home 136
- Siesta Key 87
- St. Petersburg 3
- Tierra Verde 4
- Vacation & Second Homes 782
- Venice 21
- Wellen Park 7
Recent Posts