How Long Is a Mortgage Pre-Approval Good For?
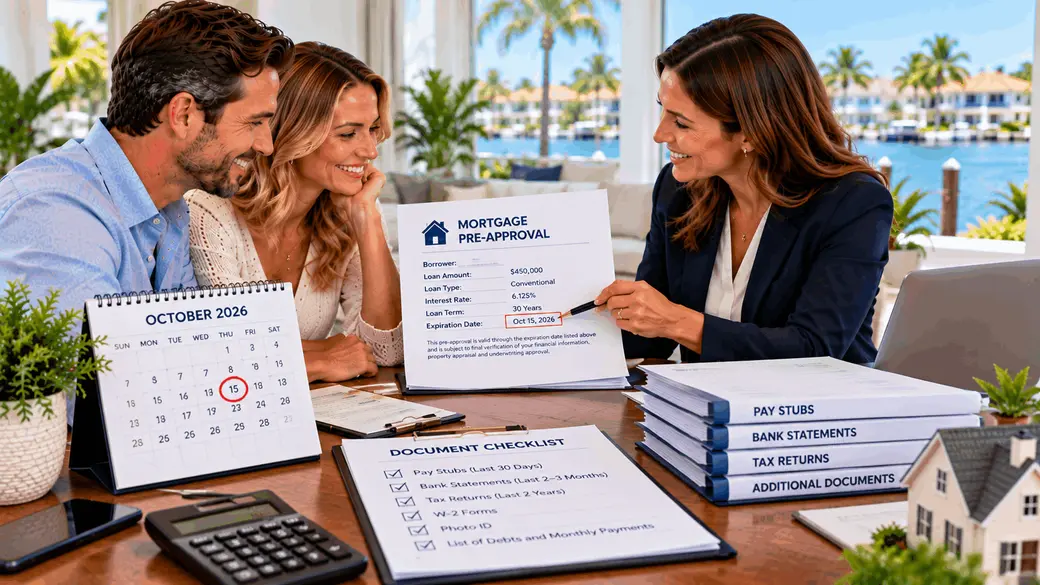
A mortgage pre-approval letter is typically good for about 30 to 60 days, according to the Consumer Financial Protection Bureau, but there is no universal expiration period that applies to every lender. Your actual expiration date depends on the lender and should appear on the letter or be confirmed directly with the mortgage professional. If your home search continues beyond that date, the lender may ask for updated financial information before issuing a new letter. A pre-approval can also need reconsideration sooner if your employment, income, debts, credit, assets, down payment or other material financing circumstances change.
Quick Answers About How Long a Mortgage Pre-Approval Is Good For
How Long Does a Mortgage Pre-Approval Last?
The Consumer Financial Protection Bureau says preapproval letters typically have an expiration period of about 30 to 60 days. That is a general range, not a rule requiring every lender to use the same period.
What Happens When My Mortgage Pre-Approval Expires?
Expiration does not necessarily mean starting the mortgage process from the beginning. Your lender may be able to update the file after reviewing current financial information, but the exact requirements depend on the lender and your circumstances.
Can I Renew an Expired Pre-Approval?
Usually, a lender can reevaluate your current information and issue an updated letter if you still meet its requirements. Ask what documents, credit review and other verification will be required before assuming renewal will be automatic.
Can a Pre-Approval Change Before It Expires?
Yes. A pre-approval is based on your financial profile and the lender's assumptions at a particular point in time. Changes to income, employment, debts, credit, assets, down payment, loan program or interest-rate assumptions can affect the financing even while the original letter remains within its stated date range.
Does Pre-Approval Expiration Mean My Credit Score Is No Longer Good?
No. The expiration of the letter does not by itself mean there is a problem with your credit. It means the lender's preliminary financing assessment has reached the end of the period for which that lender was willing to rely on the information and assumptions used to issue it.
Should I Get Pre-Approved Months Before I Plan to Buy?
You can start discussing financing early, especially if you want time to investigate credit, income, debt or down-payment questions. However, because preapproval letters expire and lenders typically check credit before issuing them, CFPB notes that many buyers wait until they are ready to begin serious home shopping.
Why Does Mortgage Pre-Approval Expire?
Mortgage pre-approval expires because the information used to evaluate a borrower can change. A lender is making a preliminary financing assessment based on your financial circumstances and certain assumptions at a particular time.
Those circumstances may include:
- Income
- Employment
- Credit history
- Outstanding debts
- Bank and investment assets
- Available down payment
- Loan program
- Interest-rate and payment assumptions
A letter that accurately reflected your situation weeks ago may no longer represent your current financial position. Expiration gives the lender an opportunity to determine whether the original assessment remains appropriate.
Is 30 to 60 Days a Rule or Just a Typical Pre-Approval Period?
It is a typical period identified by CFPB, not a universal rule. There is no requirement that every mortgage lender make every preapproval letter valid for exactly 30, 45 or 60 days.
That distinction matters because buyers sometimes see a general timeframe online and assume their own letter follows the same schedule. Instead, look at your actual preapproval letter and ask your lender:
- What date does this letter expire?
- What will you need to update it?
- Will another credit review be required?
- Will I need new income or asset statements?
- What changes should I report before expiration?
What Happens When a Mortgage Pre-Approval Expires?
An expired preapproval does not automatically mean you no longer qualify for a mortgage. It means you should contact the lender before continuing to rely on the old letter for an offer or financing decision.
The lender may ask you to provide updated information and then issue a new preapproval letter. If your financial circumstances have remained stable, updating the letter may be relatively straightforward. If something material has changed, the lender may need to reevaluate the amount, loan program or other assumptions.
Do not assume that an old letter remains acceptable simply because you were previously approved for the same amount.
What Might a Lender Need to Update Your Pre-Approval?
Update requirements vary by lender, borrower and loan program. Depending on how much time has passed and what information is outdated, the lender may request current versions of documents previously reviewed.
Examples can include:
- Recent pay statements
- Updated bank statements
- Updated investment or retirement account statements
- Current employment information
- Updated information about debts
- Additional self-employment documentation when applicable
- Updated information about down-payment funds
- A new or updated credit review when required by the lender
These are examples, not a universal renewal checklist. Ask the lender handling your preapproval what is required for your individual file.
Will Renewing a Pre-Approval Require Another Credit Check?
It can. CFPB states that lenders typically check credit before issuing a preapproval letter. Whether an updated preapproval requires another credit inquiry depends on the lender, how much time has passed and the lender's requirements.
Do not assume that updating a letter automatically requires a new inquiry or that it never will. Ask the lender before authorizing an update if the potential credit inquiry matters to you.
Credit scoring and mortgage qualification are borrower-specific. Buyers with questions about how an additional inquiry may affect their individual credit profile should discuss the issue with the lender or an appropriate credit professional.
Can Your Mortgage Pre-Approval Change Before the Expiration Date?
Yes. The printed expiration date should not be interpreted as a guarantee that nothing can affect your financing until that day.
A preapproval is preliminary and conditional. Changes during your home search can cause the lender to reconsider the original analysis.
Changing Jobs or Income
A change in employment, compensation structure, hours, commission income or other income can affect mortgage qualification. Tell your lender about a contemplated or actual employment change rather than assuming the existing preapproval remains unchanged.
Taking on New Debt
A new car loan, personal loan, financed purchase or larger credit-card balance can change your monthly obligations. Because debt is part of mortgage qualification, new obligations can affect the original preapproval calculation.
Opening New Credit
Opening additional credit accounts can change the information available to the lender. Before applying for new credit while shopping for a home, ask your mortgage professional how the proposed account could affect your financing.
Changing Available Cash or Assets
Your preapproval may assume a particular down payment, amount of available cash or reserve position. Significant changes to those assets can require another lender review.
Changing the Down Payment or Loan Program
A different down payment can change the loan amount, mortgage insurance, available loan programs and other financing characteristics. Similarly, changing from one mortgage program to another can produce a different qualification result.
Can Interest Rates Affect a Current Pre-Approval?
Potentially. A preapproval may use an assumed interest rate to estimate the mortgage payment and financing amount. If market rates change materially before you purchase, the lender may need to update its calculations.
A higher interest rate can increase the principal-and-interest payment on the same loan amount. Depending on the borrower's financial profile and underwriting requirements, that can affect qualification.
Also, do not assume that a preapproval letter means your interest rate is locked. Preapproval and rate locking are separate concepts. Ask the lender whether any rate is actually locked, how long the lock lasts and what conditions apply.
Does a Pre-Approval Guarantee You Can Buy Any Home Within the Approved Amount?
No. A current preapproval does not guarantee final mortgage approval for you or for a particular property.
CFPB describes a preapproval letter as a lender's statement that it is tentatively willing to lend up to a certain amount. The letter is based on assumptions and is not a guaranteed loan offer.
After you select a home, final financing may depend on additional borrower verification and property-specific matters such as:
- Appraised value
- Property type
- Property condition when relevant to the mortgage program
- Insurance requirements
- Title requirements
- Condominium project eligibility when applicable
A buyer can therefore have a valid preapproval letter and still encounter a property that does not qualify for the intended financing. Property-specific mortgage eligibility should be verified with the lender.
Does the Pre-Approval Amount Tell You What You Should Spend?
No. A current preapproval tells you something about what a lender may be willing to finance under its criteria and assumptions. It does not determine what purchase price is personally comfortable for you.
This distinction is especially important when comparing Florida homes because two properties with identical prices can have very different total ownership costs.
Depending on the property, your budget may need to include:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- Flood insurance when applicable
- Mortgage insurance when applicable
- HOA or condominium assessments
- CDD or other non-ad valorem assessments when applicable
- Maintenance and future repairs
Hunt Brothers Realty's guide to the true cost of buying a home in Florida explains why buyers should evaluate the complete ownership budget rather than relying only on a lender's maximum financing amount.
When Is the Best Time to Get Pre-Approved?
A practical time to obtain preapproval is when you are transitioning from general research into serious home shopping and would be prepared to make an offer if the right property becomes available.
CFPB notes that many buyers wait until they are ready to shop seriously because lenders typically check credit and preapproval letters can expire. Starting earlier can still be useful when you want time to identify potential credit, income, debt or documentation issues.
For a more complete discussion of timing, read Hunt Brothers Realty's guide to getting pre-approved before looking at homes in Florida.
What If Your Pre-Approval Will Expire While You Are House Hunting?
Contact your lender before the expiration date rather than waiting until you are preparing an offer. Ask what information will need to be refreshed and how much time the lender needs to issue an updated letter.
This can be particularly useful when you are actively touring homes. CFPB notes that sellers frequently require a preapproval letter before accepting an offer, so having a current letter available can prevent an avoidable financing-document delay.
Buyers can continue researching Florida Gulf Coast communities with Hunt Brothers Realty while coordinating the timing of their financing documentation with their mortgage professional.
Do You Need a New Pre-Approval Letter for a Different Purchase Price?
Potentially. If the property you want to offer on differs materially from the assumptions used for your existing preapproval, ask the lender whether it should issue an updated letter.
Purchase price is not the only variable. Property taxes, insurance, association assessments and other recurring housing expenses can affect the overall payment and potentially the lender's qualification analysis.
Before submitting an offer, give the lender the actual property information and proposed purchase terms when appropriate so the mortgage professional can identify whether the original financing assumptions still work.
Why Can Florida Property Expenses Affect an Existing Pre-Approval?
A preliminary preapproval may be issued before you have selected a specific property. That means the lender may initially be working with estimated taxes, insurance or association expenses rather than the actual costs of the home you eventually choose.
For Florida buyers, the difference can be significant. One property may have a condominium assessment, another may have an HOA and CDD expense, and another may have substantially different insurance costs.
Insurance availability, coverage, premiums and deductibles can vary substantially by property. Buyers should obtain property-specific quotes and review coverage with a qualified insurance professional before making a purchasing decision.
The lender should separately confirm how the actual property expenses affect mortgage qualification.
Does an Updated Pre-Approval Mean You Have Final Loan Approval?
No. Updating an expired or aging preapproval still does not turn the letter into final mortgage approval.
The mortgage process continues after you identify a property and enter into a purchase contract. The lender may need updated borrower documentation, underwriting, appraisal and property-specific information before the loan can receive final approval.
This is also why buyers should distinguish between mortgage prequalification and preapproval and the later stages of formal mortgage underwriting.
Should You Avoid Financial Changes While Pre-Approved?
Rather than assuming that every financial change is prohibited, discuss significant changes with your mortgage professional before acting when possible. The effect depends on the borrower, mortgage program and transaction.
Examples worth discussing with the lender include:
- Changing jobs
- Becoming self-employed
- Financing a vehicle
- Opening a new credit card
- Making a major financed purchase
- Moving substantial funds between accounts
- Receiving or using gift funds
- Changing the planned down payment
Mortgage consequences are individual. A qualified mortgage professional should evaluate how a proposed change affects your particular financing rather than relying on a general rule from an online checklist.
Should You Compare Lenders Again When Updating Pre-Approval?
An expiring preapproval can be a useful reminder that preapproval does not commit you to the lender that issued the original letter. Buyers can compare lenders and financing options as their home search progresses.
When comparing mortgage options, consider more than the maximum loan amount. Depending on the financing, relevant factors can include:
- Interest rate
- Annual percentage rate
- Lender fees
- Discount points
- Mortgage insurance when applicable
- Required down payment
- Estimated monthly payment
- Estimated cash needed to close
Financing terms and qualification are borrower-specific. Compare current proposals with qualified mortgage professionals before selecting a loan.
How Much Cash Should You Plan for Beyond Pre-Approval?
Keeping your preapproval current is only one part of financial preparation. Buyers also need to understand the cash required for the transaction and the amount they want to retain after closing.
Potential cash needs can include the down payment, earnest money deposit, inspections, appraisal when applicable, closing costs, prepaid expenses, escrow funding, moving expenses and immediate post-closing costs.
Hunt Brothers Realty's 2026 Florida buyer closing-cost guide explains the expenses financed buyers may encounter in addition to their down payment.
Mortgage Pre-Approval Expiration Checklist
If your preapproval is approaching its expiration date, consider confirming the following with your mortgage professional:
- The exact expiration date
- Documents that need to be updated
- Whether another credit review is required
- Whether your income or employment information needs reverification
- Whether your current assets still support the planned down payment and closing funds
- Whether interest-rate assumptions have changed
- Whether the maximum loan amount has changed
- Whether your target property type creates additional requirements
- How quickly the lender can issue an updated letter when you need to make an offer
The Bottom Line: How Long Is Mortgage Pre-Approval Good For?
Mortgage preapproval letters are typically good for approximately 30 to 60 days according to CFPB guidance, but the lender determines the actual expiration period. Check the date on your letter rather than relying on a generic online timeframe.
If your search continues beyond expiration, contact the lender before you need to make an offer and ask what information must be updated. In many situations, an expired letter can be refreshed after the lender reviews current information rather than requiring the buyer to treat the process as if no prior review occurred.
Most importantly, remember that the expiration date is not a guarantee of financing through that date. Material changes to your financial profile or the assumptions behind the preapproval can affect qualification sooner, and final mortgage approval still depends on the lender's complete underwriting and the specific property.
Prepare for Your Florida Home Search With Hunt Brothers Realty
Hunt Brothers Realty can help buyers turn a realistic home-buying budget and current financing information into a focused Sarasota and Florida Gulf Coast property search.
Continue with Should I Get Pre-Approved Before Looking at Homes in Florida?, Mortgage Prequalification vs. Preapproval, What Credit Score Do I Need to Buy a House in Florida?, Florida Buyer Closing Costs in 2026, and The True Cost of Buying a Home in Florida.
You can also explore Florida Gulf Coast communities or contact Hunt Brothers Realty when you are ready to discuss your property search.
This article provides general real estate and educational information only and is not individualized financial, lending, legal, tax, insurance or other professional advice. Preapproval validity, credit review, mortgage qualification, documentation, interest rates, loan programs and renewal requirements vary by lender and borrower. Buyers should have qualified mortgage professionals review their individual circumstances and confirm current financing requirements before making purchasing or financing decisions.
Sources
- Consumer Financial Protection Bureau, Get a Preapproval Letter
- Consumer Financial Protection Bureau, Prequalification vs. Preapproval
- Consumer Financial Protection Bureau, Mortgages
- Hunt Brothers Realty, Should I Get Pre-Approved Before Looking at Homes in Florida?
- Hunt Brothers Realty, Mortgage Prequalification vs. Preapproval
- Hunt Brothers Realty, Florida Buyer Closing Costs in 2026
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
Contact Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2112
- Anna Maria Island 86
- Bird Key 4
- Bradenton 236
- Buying a Home 1171
- Casey Key 2
- Clearwater 11
- Condos & HOA Living 1088
- Ellenton 5
- Englewood 11
- First Time Homebuyers 1280
- Foreclosures 5
- Home Selling 6
- Homeownership 1304
- Lakewood Ranch 25
- Lido Key 28
- Longboat Key 80
- Luxury/Waterfront Properties 1244
- Market Updates & Trends 766
- Mortgages & Financing 48
- Move-Up Buyers 22
- Neighborhood Guides 879
- New Construction 34
- Palmetto 3
- Parrish 6
- Port Charlotte 10
- Punta Gorda 17
- Real Estate Investing 1160
- Relocation to Florida 1200
- Safety Harbor 3
- Sarasota 81
- Sarasota - Downtown 162
- Selling a Home 146
- Siesta Key 91
- St. Petersburg 8
- Tierra Verde 5
- Vacation & Second Homes 1353
- Venice 193
- Wellen Park 19
Recent Posts