What Should Luxury Buyers Know Before Buying in Florida?
Luxury buyers in Florida should investigate much more than architecture, finishes, views and purchase price. High-end properties can introduce specialized issues involving homeowners and flood insurance, coastal exposure, seawalls, docks, condominium reserves, association assessments, title, surveys, renovation permits, hurricane protection and substantial long-term maintenance. Buyers should also determine whether the property's location and infrastructure actually support the lifestyle they expect. A multimillion-dollar home is not automatically easier to insure, maintain, renovate or resell. The most informed buyers assemble the appropriate real estate, legal, insurance, inspection, tax, lending and technical professionals early enough to investigate material issues before making final decisions.
For waterfront purchases in particular, Hunt Brothers Realty's guide to what luxury buyers should evaluate in Sarasota waterfront homes explains why the waterfront itself deserves as much attention as the residence.
Quick Answers About Buying Luxury Real Estate in Florida
What is the biggest mistake luxury buyers can make in Florida?
One major mistake is assuming a high purchase price means the property has already been thoroughly vetted. Luxury homes can have complicated insurance, waterfront, structural, mechanical, title, association and permitting considerations. Due diligence should generally become more detailed as the property's complexity increases.
Should luxury buyers get insurance quotes before closing?
Yes. Florida insurance is property-specific. Buyers should investigate homeowners, wind and flood coverage as applicable, along with deductibles, exclusions, replacement-cost assumptions and coverage for valuable personal property. Obtain property-specific quotes early enough for the results to inform the purchasing decision.
Does homeowners insurance cover flooding in Florida?
Standard homeowners insurance does not cover flood damage. Flood coverage is separate. Luxury buyers should investigate the property's flood exposure and obtain property-specific insurance guidance rather than assuming that a high elevation, newer construction or a particular flood-zone designation eliminates the issue.
Should a luxury waterfront buyer inspect the seawall and dock?
Yes, when those features exist. The seawall, dock, boat lift and shoreline can represent substantial infrastructure. Buyers should investigate condition, permits, maintenance history, responsibility for repairs and whether the boating setup actually works for the intended vessel.
Are luxury Florida condos different from buying a luxury house?
Yes. A luxury condominium purchase requires evaluating both the residence and the association. Reserves, special assessments, insurance, capital projects, applicable structural inspections, governing documents, parking, storage and renovation restrictions can all materially affect ownership.
Do cash buyers still need detailed due diligence?
Absolutely. Paying cash removes lender underwriting from the transaction, but it does not remove property risk. A lender's absence makes it especially important that the buyer independently evaluates insurance, title, survey, inspections, flood considerations, association information and other material issues.
Should luxury buyers use specialized inspectors?
Often, yes. Depending on the property, appropriate specialists may be needed for the roof, structure, seawall, dock, pool, elevators, generators, sophisticated HVAC, electrical systems, smart-home equipment or other complex components. A general inspection should not automatically be assumed to cover every specialized system.
Can foreign buyers purchase luxury real estate in Florida?
International purchases can involve additional federal and Florida legal, tax, ownership and reporting considerations. Buyers should obtain individualized advice from qualified U.S. legal and tax professionals before deciding how to acquire, hold or later transfer Florida real estate.
Luxury Florida Buyer Due Diligence at a Glance
| Issue | What to Investigate | Professional to Consider |
|---|---|---|
| Insurance | Availability, limits, deductibles, wind, flood and replacement cost | Qualified insurance professional |
| Property condition | Structure, roof, systems, pool and specialized equipment | Inspector, engineer and appropriate contractors |
| Waterfront | Seawall, dock, lift, water depth, bridges, permits and shoreline | Marine contractor, engineer, surveyor and permitting authorities |
| Condominium | Reserves, assessments, inspections, insurance and capital projects | Attorney, CPA, insurance professional and relevant technical specialists |
| Title and survey | Ownership, easements, encroachments, boundaries and exceptions | Title professional, surveyor and real estate attorney |
| Taxes and ownership structure | Property-specific tax consequences and ownership objectives | CPA or tax professional and attorney |
| Renovation plans | Permits, association approval, coastal restrictions and feasibility | Architect, engineer, contractor, association and permitting authority |
1. The Purchase Price Is Only the Beginning
Luxury buyers often focus first on price per square foot, architecture, location, views and finishes. Those factors matter, but they do not reveal the complete ownership cost.
Depending on the property, the annual or long-term budget can also include:
- Homeowners and flood insurance
- Property taxes
- Condominium or HOA assessments
- Special assessments
- Club or golf expenses
- Property management
- Pool and landscape maintenance
- Seawall, dock and boat-lift maintenance
- Elevator and generator service
- Sophisticated HVAC and smart-home systems
- Storm preparation
- Exterior maintenance in a coastal environment
- Periodic major capital projects
A luxury property that comfortably fits the acquisition budget can still be a poor financial fit if its recurring expenses and future capital requirements were not investigated before closing.
2. Get Property-Specific Insurance Information Early
Florida homeowners insurance should be investigated before the purchase becomes difficult to unwind.
The Florida Department of Financial Services explains that insurers can evaluate factors including the home's age, construction, roof, plumbing, electrical systems, location, occupancy, prior claims and wind-mitigation characteristics.
For a luxury residence, also discuss whether the proposed coverage appropriately addresses:
- Replacement cost
- Hurricane and other deductibles
- Ordinance and law coverage
- Detached structures
- Pools and outdoor improvements
- High-value contents
- Jewelry, art, antiques or collections
- Liability coverage
- Flood coverage
Insurance availability, coverage, exclusions, deductibles and premiums can vary substantially by property and insurer. Luxury buyers should obtain property-specific quotes and review proposed coverage with a qualified insurance professional before making a final purchasing decision.
3. Understand the Hurricane Deductible
The premium is not the only insurance number worth examining.
Florida policies can have a hurricane deductible separate from the standard all-perils deductible. The Florida Department of Financial Services hurricane deductible guide explains the available deductible structures and when the hurricane deductible applies.
This deserves particular attention on a high-value residence because a percentage-based deductible can translate into a substantial dollar amount.
Ask the insurance professional to state each deductible in actual dollars based on the proposed coverage, then evaluate whether that potential out-of-pocket exposure fits your risk tolerance.
4. Flood Risk Requires Its Own Analysis
Standard homeowners insurance does not cover flood damage.
That distinction is especially important when evaluating waterfront and coastal luxury property.
Do not reduce flood due diligence to one map designation. Depending on the property, investigate:
- Current flood-zone information
- Available elevation documentation
- Seller flood disclosure
- Known prior flooding information
- Drainage around the property
- Finished-floor elevation
- Lower-level construction and use
- Flood openings or other mitigation features when applicable
- Property-specific flood insurance options
Flood maps and insurance classifications are important pieces of information, but they are not substitutes for property-specific evaluation. Buyers should review current information with the appropriate insurance, surveying, engineering and other qualified professionals when flood exposure could materially affect the decision.
5. A Waterfront Home Is Really Two Purchases
When buying luxury waterfront property, you are effectively evaluating both a residence and a waterfront system.
The kitchen, architecture and view may be spectacular while the seawall, dock, lift or boating access creates a very different financial picture.
Hunt Brothers Realty's 2026 Florida waterfront home buyer guide recommends investigating the complete waterfront environment rather than relying on a listing description.
Important questions include:
- What type of waterfront is it?
- Who owns and maintains the seawall?
- What is the seawall's condition?
- Are dock and boat-lift permits available?
- What is the usable water depth?
- How do tides affect access?
- Are there fixed bridges?
- Will the intended vessel clear those bridges?
- Is the lift appropriately rated for the intended boat?
- How long is the actual route to open water?
- Are shoreline restrictions relevant?
For a deeper luxury-specific checklist, see How to Evaluate a High-End Waterfront Property in Florida.
6. Do Not Assume the Dock Works for Your Boat
A waterfront listing can accurately advertise boating access while still being unsuitable for a particular vessel.
Boat length is only one consideration. Draft, beam, height, lift capacity, tidal depth, bridge clearance, canal dimensions and navigation routes can all matter.
Do not rely solely on descriptions such as "deep water," "sailboat water," "no bridges" or "minutes to the Gulf" when those characteristics are material to your purchase.
Verify the route and infrastructure against the vessel you intend to use, with appropriate marine, surveying and other professional assistance when necessary.
7. Investigate Coastal Construction Restrictions Before Planning Renovations
A luxury buyer may purchase a property with plans for a substantial addition, pool renovation, guest structure, seawall project or complete redevelopment.
Coastal property can require additional investigation before assuming those plans are feasible.
The Florida Department of Environmental Protection explains that construction and excavation seaward of Florida's Coastal Construction Control Line generally require a DEP permit unless an exemption applies. Coastal projects can also involve local requirements and other state or federal approvals depending on the work.
If a renovation, demolition, shoreline improvement, dock, seawall or expansion is important to the purchase, investigate feasibility with the appropriate architect, engineer, contractor, association and government permitting authorities before relying on the project in your purchasing decision.
8. Luxury Condos Require Building-Level Due Diligence
A spectacular residence on a high floor can still be affected by the finances and physical condition of the entire condominium.
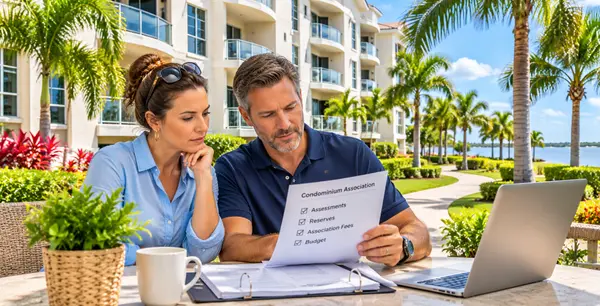
Florida condominium buyers should evaluate both the unit and the association.
Depending on the building, important records can include:
- Declaration and bylaws
- Current rules
- Current budget
- Financial statements
- Reserve information
- Structural Integrity Reserve Study information when applicable
- Milestone inspection information when applicable
- Approved or proposed special assessments
- Association insurance and deductibles
- Recent meeting minutes
- Major completed and planned projects
- Association loans
- Rental and pet rules
- Renovation restrictions
- Parking and storage rights
Current Florida law requires milestone structural inspections for qualifying condominium and cooperative buildings and Structural Integrity Reserve Studies for qualifying residential condominiums. Requirements depend on the building and applicable law.
Hunt Brothers Realty's 2026 Florida condo buyer guide provides a more detailed document and financial checklist. Legal, accounting, structural and insurance issues should be reviewed with the appropriate qualified professionals when they could materially affect the purchase.
9. A High Condo Fee Does Not Automatically Mean a Poorly Run Building
Luxury condominium fees can be substantial, particularly in buildings with extensive staffing and amenities.
The important question is what the assessment funds and whether the association's financial resources align with its responsibilities.
Luxury buildings may fund services and facilities such as:
- Concierge or staffed reception
- Security
- Valet services
- Pools and spas
- Fitness and wellness facilities
- Elevators
- Common-area air conditioning
- Landscaping
- Building insurance
- Maintenance personnel
- Reserve contributions
Likewise, a comparatively low fee does not establish financial strength. Evaluate the budget, reserves, capital needs and services together rather than judging the association by one monthly number.
10. Special Assessments Deserve Detailed Investigation
A large special assessment is not automatically a reason to reject a luxury condominium, but it is a reason to understand the complete project.
Ask what the assessment funds, whether the scope is final, what amount applies to the residence, what has already been paid and whether additional major projects are being discussed.
Hunt Brothers Realty's Florida condo special assessment guide outlines documents worth investigating, including engineering reports, bids, contracts, reserves, meeting minutes and applicable structural information.
The allocation of assessment obligations between buyer and seller is a contract and legal matter. Buyers should have significant assessment questions reviewed by a qualified Florida real estate attorney and seek appropriate financial or technical review when necessary.
11. Inspect the Systems You Cannot See During a Showing
Luxury finishes can distract from expensive systems operating behind the walls, above the ceilings and outside the residence.
Depending on the property, due diligence may need to address:
- Roof
- Structure
- Windows and exterior doors
- Storm shutters
- HVAC systems
- Electrical service
- Plumbing
- Generators
- Elevators
- Pool and spa systems
- Outdoor kitchens
- Irrigation
- Smart-home and automation systems
- Security and access systems
- Waterproofing and drainage
- Seawall, dock and lift when applicable
Inspection findings should be evaluated by the appropriate licensed inspector, engineer, contractor, electrician, marine contractor or other qualified specialist before the buyer makes a decision. The appropriate inspection team depends on the individual property.
12. Verify Major Renovations and Permits
Luxury properties are frequently remodeled, expanded or substantially customized.
When major work is material to the property's appeal, investigate available documentation for items such as:
- Additions
- Structural alterations
- Roof replacement
- Impact windows and doors
- Electrical upgrades
- Plumbing changes
- Pools
- Generators
- Elevators
- Docks and boat lifts
- Seawall work
Permit requirements and records vary by project and jurisdiction. Questions concerning whether work was properly permitted, completed or approved should be verified with the appropriate local government, association, contractor, engineer or other qualified professional.
13. A Survey Can Matter Even More on a Luxury Property
Do not assume that fences, seawalls, docks, driveways, landscaping or accessory structures accurately define the property's legal boundaries.
A current survey may help identify or document matters involving:
- Property boundaries
- Easements
- Encroachments
- Improvements
- Access
- Waterfront features
Survey and title findings can involve legal rights that should not be interpreted solely from a marketing description or visual inspection. Material questions should be reviewed with a qualified surveyor, title professional and Florida real estate attorney.
14. Review Title and Ownership Structure Carefully
Luxury purchases can involve trusts, business entities, estate-planning structures, multiple owners or international purchasers.
How a buyer takes title can have legal, tax, estate-planning, liability, financing and homestead implications. Those consequences depend on the buyer's individual circumstances.
A real estate brokerage should not select the buyer's legal or tax ownership structure. Buyers considering trusts, LLCs, corporations, joint ownership or other arrangements should discuss the decision with qualified Florida legal and tax professionals before the deed and closing documents are prepared.
15. International Transactions Can Add Another Layer of Complexity
International buyers and transactions involving foreign sellers can create additional tax, reporting, banking and ownership issues.
One important federal issue is the Foreign Investment in Real Property Tax Act, commonly called FIRPTA. The Internal Revenue Service FIRPTA guidance explains that a buyer can have withholding responsibilities when acquiring U.S. real property from a foreign seller, subject to applicable rules and exceptions.
International buyers and buyers purchasing from foreign sellers should obtain transaction-specific guidance from qualified U.S. tax, legal and closing professionals. Do not rely on a general article to determine withholding, tax liability or the appropriate ownership structure.
16. Cash Does Not Eliminate Risk
Luxury buyers sometimes choose cash for convenience or negotiating reasons. Cash can simplify financing, but it does not make inspections, insurance, title, surveys or association review unnecessary.
In a financed transaction, a lender may impose its own requirements concerning title, insurance, appraisal or condominium eligibility. A cash buyer does not have that additional institutional review.
Cash buyers should decide which due-diligence protections are appropriate based on the property and contract, with guidance from their licensed real estate professional and Florida real estate attorney when contract or legal questions arise.
17. Financing a Luxury Property Can Be Different
Luxury financing can involve jumbo loans, portfolio lending and underwriting requirements that differ from more conventional transactions.
Condominium financing can introduce another layer because the lender may evaluate the condominium project in addition to the borrower.
Buyers planning to finance should discuss loan structure, liquidity requirements, appraisal considerations, condominium eligibility and timing with a qualified mortgage or lending professional before relying on a particular financing strategy.
18. Do Not Assume a Luxury Appraisal Works Like a Typical Appraisal
Highly distinctive homes can be difficult to compare because truly similar recent sales may be limited.
Waterfront orientation, lot quality, architectural significance, renovation quality, view, dockage, privacy, condominium floor and building characteristics can make superficially similar properties meaningfully different.
Buyers using financing should understand the lender's appraisal requirements with their loan professional. Cash buyers who want an independent valuation opinion can discuss appropriate appraisal services with a qualified Florida appraiser.
19. Privacy and Security Should Be Evaluated Practically
Luxury marketing often uses terms such as private, gated or secluded. Buyers should determine what those descriptions mean at the individual property.
Consider practical factors such as:
- Sightlines from neighboring homes
- Passing boats on waterfront property
- Public beach or water access nearby
- Gate staffing and access procedures
- Condominium lobby and elevator access
- Garage access
- Landscaping and setbacks
- Smart-home and security equipment
Evaluate the physical characteristics and documented services rather than assuming that a marketing term guarantees a particular level of privacy or security.
20. Understand the Maintenance Demands of Coastal Luxury Homes
Salt air, moisture, strong sun, wind and storm exposure can affect exterior materials and mechanical systems.
Depending on the property, ongoing maintenance may involve:
- Exterior paint and finishes
- Metal railings and hardware
- Windows and doors
- Roof components
- Outdoor appliances
- Pool equipment
- HVAC equipment
- Generators
- Docks and boat lifts
- Seawalls
- Landscaping and irrigation
A well-maintained coastal residence can still require a substantial annual operating budget. Buyers should develop a property-specific maintenance plan rather than relying on a percentage of purchase price alone.
21. Understand What You Are Really Paying a Premium For
Not every luxury feature contributes equally to the ownership experience.
A buyer may be paying a premium for:
- Waterfront location
- A particular view
- Boating access
- Lot size
- Privacy
- Architecture
- Recent construction
- Renovation quality
- Condominium floor and orientation
- Walkability
- Beach access
- Club membership opportunities
Determine which attributes actually matter to you. Paying for a dock has little lifestyle value if you do not boat. Paying a premium for a downtown penthouse may make perfect sense if walkability and a low-maintenance residence are your highest priorities.
22. Choose the Florida Luxury Lifestyle Before Choosing the House
Florida luxury real estate is not one housing category.
On the Sarasota Gulf Coast alone, a buyer might compare:
- A Downtown Sarasota penthouse
- A Sarasota Bay condominium
- A Bird Key waterfront residence
- A Harbor Acres boating property
- A Lido Key beach residence
- A Siesta Key waterfront home
- A Longboat Key condominium or estate
- A Casey Key estate
- A Lakewood Ranch golf or custom home
These properties can occupy similar price ranges while providing dramatically different daily routines, maintenance obligations and ownership structures.
A Florida Luxury Buyer Checklist Before Closing
The appropriate due diligence depends on the property, but luxury buyers should consider whether they have adequately investigated the following items that apply:
- Purchase contract and important deadlines
- Property-specific homeowners insurance
- Flood insurance and flood exposure
- Hurricane deductible
- Replacement-cost assumptions
- Independent property inspection
- Specialized inspections when appropriate
- Roof and storm-protection features
- Major mechanical systems
- Generator and elevator when applicable
- Pool and outdoor-living systems
- Survey
- Title matters
- Easements and access
- Major renovation permits
- Seawall and shoreline condition when applicable
- Dock and boat-lift permits and condition
- Boating route, depth and bridge clearance
- Condominium or HOA documents
- Association budget, reserves and assessments
- Applicable structural inspection information
- Rental, pet and renovation restrictions
- Parking and storage rights
- Property tax considerations
- Ownership structure
- Financing requirements when applicable
- Realistic annual maintenance budget
The Bottom Line for Florida Luxury Buyers
Luxury real estate rewards careful due diligence because the properties themselves can be unusually complex.
An exceptional view does not establish the condition of a seawall. A beautifully renovated condominium does not establish the financial condition of its association. A new roof does not tell you the complete insurance picture. A private dock does not establish that your boat can reach open water. A multimillion-dollar purchase price does not establish that every renovation was properly permitted.
The goal is not to make luxury buying unnecessarily complicated. It is to identify the few issues that could materially change the ownership experience before they become expensive surprises.
For the right buyer, a Florida luxury residence can provide exactly the combination of location, privacy, water access, amenities and lifestyle they want. The strongest purchase is one where the property's physical condition, legal rights, insurance profile, ownership costs and intended use have all been evaluated alongside its beauty.
Buying Luxury Real Estate on Florida's Gulf Coast?
Hunt Brothers Realty helps buyers compare luxury homes, waterfront properties and condominiums throughout Sarasota and Florida's Gulf Coast with attention to both lifestyle and property-specific considerations.
If waterfront property is part of your search, explore Hunt Brothers Realty's luxury waterfront buyer checklist, high-end waterfront property guide and Florida waterfront home buyer guide.
Condominium buyers can also review what to know before buying a Florida condo before comparing high-rise and waterfront residences.
Contact Hunt Brothers Realty when you are ready to compare specific luxury properties on Florida's Gulf Coast.
This article is provided for general informational and educational purposes only and is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction, title, association or other professional advice. Luxury properties can involve highly property-specific issues involving insurance, flood exposure, structural condition, waterfront infrastructure, associations, taxes, title, financing, permitting and ownership structure. Buyers should verify material information for the specific property and consult the appropriate licensed real estate professional, Florida real estate attorney, tax professional or CPA, insurance agent, lender, inspector, engineer, contractor, surveyor, title or closing professional, association and government permitting authority before making decisions requiring individualized guidance.
Sources
- Florida Department of Financial Services, Homeowners Insurance Overview
- Florida Department of Financial Services, Florida's Hurricane Deductible
- Florida Department of Financial Services, Flood Insurance Overview
- Florida Legislature, 2026 Florida Condominium Act
- Florida Legislature, Mandatory Structural Inspections for Condominium and Cooperative Buildings
- Florida Department of Environmental Protection, Coastal Construction Control Line Permitting
- Internal Revenue Service, FIRPTA Withholding
- Hunt Brothers Realty, What Luxury Buyers Look for in Sarasota Waterfront Homes
- Hunt Brothers Realty, How to Evaluate a High-End Waterfront Property in Florida
- Hunt Brothers Realty, Buying a Florida Condo: What to Know in 2026
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2634
- Anna Maria Island 92
- Bird Key 5
- Bradenton 242
- Buying a Home 1656
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1584
- Ellenton 8
- Englewood 15
- First Time Homebuyers 1777
- Foreclosures 4
- Home Selling 9
- Homeownership 1820
- Lakewood Ranch 36
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1761
- Market Updates & Trends 1263
- Mortgages & Financing 85
- Move-Up Buyers 24
- Neighborhood Guides 1391
- New Construction 46
- Palmetto 4
- Parrish 38
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1674
- Relocation to Florida 1702
- Safety Harbor 4
- Sarasota 147
- Sarasota - Downtown 175
- Selling a Home 148
- Siesta Key 94
- St. Petersburg 11
- Taxes and Homestead 3
- Tierra Verde 7
- Vacation & Second Homes 1868
- Venice 224
- Wellen Park 24
Recent Posts