3 Costs Buyers Should Plan For
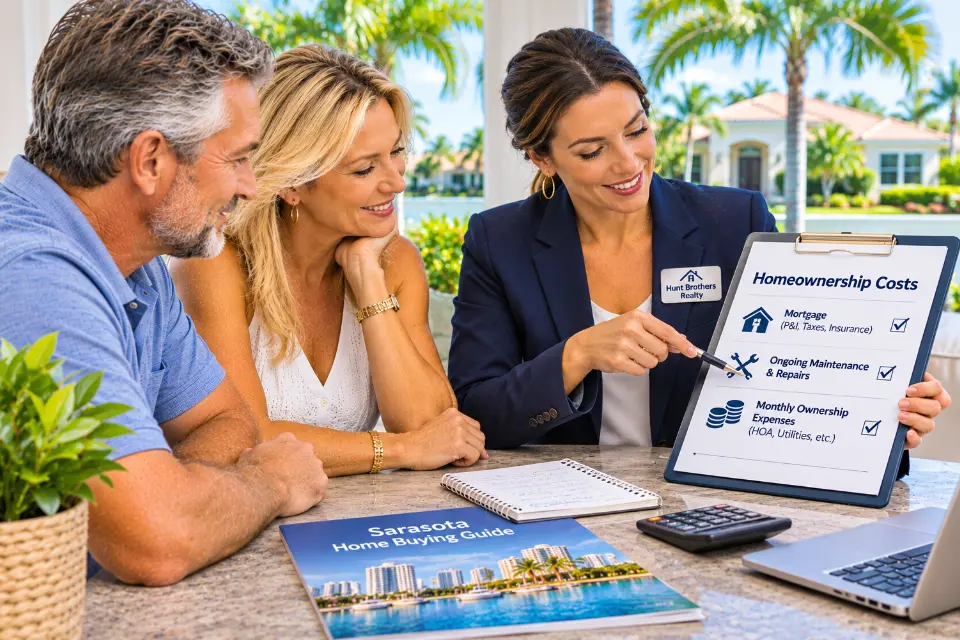
Florida home buyers should plan for three broad cost categories: the cash required to complete the purchase, the recurring cost of owning the specific property, and money for maintenance, repairs, and unexpected expenses after closing. The down payment is only one piece of the first category. Property taxes, insurance, association expenses, utilities, and maintenance can make two similarly priced Sarasota or Gulf Coast homes very different financially. A useful buying budget therefore asks both, "What will it take to buy this home?" and "What will it take to comfortably own it?"
Quick Answers About Costs Florida Home Buyers Should Plan For
What are the three major costs buyers should plan for?
Plan for cash needed before and at closing, recurring ownership expenses after closing, and reserves for maintenance, repairs, and other unexpected home expenses. Each category should be estimated for the specific property rather than from the purchase price alone.
Is the down payment the same as closing costs?
No. The down payment is generally separate from closing costs. Buyers may need money for both, along with inspections, moving expenses, and other transaction-specific costs.
How much should buyers estimate for closing costs?
For early planning, the Consumer Financial Protection Bureau uses approximately 2% to 5% of the purchase price as a broad closing-cost range, excluding the down payment. Actual costs can fall outside that range and depend on the loan, property, insurance, contract, lender, and closing arrangements.
What monthly costs should Florida buyers include?
Depending on the property, buyers may need to include mortgage payments, property taxes, homeowners or condominium insurance, flood insurance when applicable, association or district assessments, utilities, pool or landscaping expenses, and routine maintenance.
Should buyers keep money available after closing?
Buyers should consider how much money they will have available after closing for moving, maintenance, repairs, insurance deductibles, and unexpected expenses. The appropriate reserve is an individualized financial decision and should be discussed with qualified financial or lending professionals when personalized guidance is needed.
Can two Florida homes with the same price have different ownership costs?
Yes. Insurance, taxes, association assessments, property condition, utilities, pools, landscaping, flood considerations, and maintenance responsibilities can create substantial differences between similarly priced homes.
Should I use the seller's current expenses to build my budget?
Use seller-provided information as a starting point when appropriate, not as a guarantee of your future costs. Insurance premiums, taxes, financing, utility consumption, and other expenses can change based on the buyer, property, coverage, use, and future conditions.
Cost 1: How Much Cash Will You Need to Buy the Home?
The first cost category is the total cash required before and at closing, not simply the down payment. Depending on the transaction, buyers may need money for deposits, inspections, appraisal expenses, the down payment, lender charges, title and settlement expenses, prepaid items, escrow funding, and other closing costs.
Hunt Brothers Realty's Florida homebuyer closing-cost guide explains that closing costs are a collection of transaction and financing expenses rather than one standard Florida fee. The exact amount depends on the property, mortgage, lender, insurance, contract, and closing arrangements.
What Can Be Included in a Buyer's Upfront Costs?
Upfront costs vary by transaction, but a Florida buyer's planning worksheet may need to account for several expenses that occur before ownership begins.
- Earnest-money or other contract deposits
- Home inspection and appropriate specialized inspections
- Appraisal expenses when applicable
- Down payment when financing
- Mortgage origination and other lender charges
- Discount points when selected
- Title and settlement expenses as allocated in the transaction
- Recording and applicable mortgage-related charges
- Prepaid homeowners insurance
- Prepaid interest when applicable
- Initial tax and insurance escrow funding when applicable
- Association or property-specific transaction charges when applicable
Some of these costs may be paid before closing rather than at the closing table. That distinction matters because a buyer needs enough liquidity throughout the transaction, not only on closing day.
How Much Should You Estimate for Closing Costs?
For preliminary planning, approximately 2% to 5% of the purchase price, excluding the down payment, can be used as a broad closing-cost estimate. The Consumer Financial Protection Bureau uses this range while emphasizing that actual closing costs depend on factors such as the property, loan, down payment, lender, and location.
For example, 2% to 5% of a $400,000 purchase price would be approximately $8,000 to $20,000. That is an illustration, not a quote or prediction of what a particular Florida buyer will pay.
Once financing becomes property-specific, the lender's Loan Estimate is more useful than a generic percentage. Buyers should review actual loan costs and estimated cash requirements with their lender.
What Is the Difference Between Closing Costs and Cash to Close?
Closing costs and Cash to Close are not the same number. The CFPB explains that closing costs are the upfront costs associated with the loan and real estate transaction, excluding the down payment, while Cash to Close is the actual amount the buyer must provide at closing after applicable deposits, credits, and adjustments are accounted for.
The CFPB Loan Estimate explainer shows buyers where to find Estimated Cash to Close during the mortgage process. Later, the Closing Disclosure provides the final transaction information for covered mortgage loans.
If the cash requirement is different from what you expected, ask the lender or closing professional to explain the calculation rather than assuming the difference is normal.
Is a Bigger Down Payment Always Better?
Not necessarily. A larger down payment can change the loan amount and potentially other financing costs, but using more cash upfront also leaves less money available for closing expenses, moving, repairs, and reserves after the purchase.
Hunt Brothers Realty's guide to how much to put down on a house explains why buyers should compare financing scenarios rather than automatically committing the largest possible amount of available cash to the down payment.
Down-payment strategy, mortgage insurance, interest rates, qualification, and required reserves depend on the buyer and loan program. Buyers should review those decisions with a qualified mortgage professional and seek individualized financial guidance from an appropriate professional when needed.
Cost 2: What Will the Home Cost to Own Each Month?
The second cost category is the recurring expense of owning the specific home. Principal and interest may be the most visible number for a financed buyer, but the complete housing budget can include several additional property-specific expenses.
The CFPB's mortgage disclosures separate principal and interest from other housing expenses such as property taxes and homeowners insurance. Association assessments and other costs may also need to be paid separately, depending on the property and escrow arrangements.
Hunt Brothers Realty's guide to the true cost of buying a home in Florida recommends evaluating the complete ownership budget instead of stopping at the mortgage payment.
Which Recurring Costs Should Florida Buyers Compare?
The relevant expenses depend on the property. A Sarasota condominium, mainland pool home, newer planned-community residence, and coastal property can have very different cost structures even when their purchase prices are similar.
- Mortgage principal and interest when financed
- Mortgage insurance when applicable
- Property taxes
- Homeowners or condominium insurance
- Flood insurance when applicable or selected
- HOA or condominium assessments
- Community Development District or other district assessments when applicable
- Utilities
- Pool service and equipment expenses
- Landscaping and irrigation
- Pest control
- Routine property maintenance
Some expenses are monthly, while others may be billed quarterly, annually, or on another schedule. Converting them into a monthly planning figure can make different homes easier to compare, while recognizing that many of these costs can change over time.
Why Is Property-Specific Insurance Important in Florida?
Insurance can materially change the ownership cost of a Florida property, so buyers should investigate it before relying on a monthly housing budget. Coverage availability, premiums, deductibles, and underwriting considerations can differ between properties.
A seller's existing premium or a neighbor's insurance cost is not a reliable substitute for a quote on the home you intend to buy. Property characteristics such as roof information, construction, wind-mitigation features, electrical and plumbing systems, location, flood exposure, and other underwriting factors may be relevant depending on the carrier.
Insurance availability, coverage, deductibles, and premiums can vary substantially by property. Buyers should obtain property-specific quotes and review coverage with a qualified insurance professional before making a purchasing decision that depends on estimated insurance costs.
Should Buyers Use the Seller's Property-Tax Bill?
The seller's current property-tax bill should not automatically be treated as the buyer's future tax bill. The current owner's assessed value, ownership history, and exemptions may differ from what applies after a change in ownership.
Buyers should obtain a buyer-oriented property-tax estimate using information from the applicable county property appraiser rather than simply copying the seller's existing tax expense into the new budget.
Tax consequences and exemption eligibility depend on the individual owner and property. Buyers who need individualized tax guidance should consult the appropriate government office and a qualified tax professional or CPA.
How Can HOA, Condo, and CDD Expenses Change the Budget?
Association and district expenses can make similarly priced homes substantially different to own. A community assessment may fund services or amenities that an owner would otherwise pay for independently, but buyers need to understand both the amount and what it covers.
Depending on the property, investigate current HOA or condominium assessments, Community Development District assessments, applicable special assessments, and other required community expenses. Current amounts should be verified through appropriate association, management, closing, or government sources rather than assumed from an older listing.
Condominium buyers may also need to review association financial information, reserves, insurance, approved or proposed assessments, and applicable building information. Legal interpretation of association documents should be obtained from a qualified Florida attorney when individualized legal guidance is needed.
Cost 3: What Should You Plan for After Closing?
The third cost category is money needed for maintenance, repairs, replacements, moving, and unexpected expenses after the buyer becomes the owner. Closing does not end the spending associated with a home purchase, and some expenses can arrive almost immediately.
The CFPB recommends considering money needed for moving, renovations, furnishings, and an emergency cushion when deciding how much cash is available for a home purchase. That is one reason a buyer's entire savings balance should not automatically be treated as available for the down payment.
What Expenses Can Appear Soon After Closing?
Even a home that does not require major renovation can create a series of smaller expenses during the first weeks of ownership. The exact list depends on what the property includes and what the buyer already owns.
- Moving expenses
- Utility deposits or setup charges
- Locks and security updates
- Window coverings
- Furniture
- Appliances not included in the purchase
- Paint and minor repairs
- Lawn or pool equipment
- Storm-preparation supplies
- Projects identified during inspection
Hunt Brothers Realty's guide to expenses that can surprise people after moving to Florida also identifies costs such as air-conditioning, pool and landscaping service, pest control, storm preparation, and ongoing exterior maintenance as items relocating buyers may need to incorporate into their budgets.
How Much Should Buyers Budget for Maintenance?
There is no single maintenance percentage that accurately describes every Florida home. Property age, condition, construction, size, location, pool ownership, landscaping, waterfront features, and association responsibilities can all change the maintenance profile.
A newer inland home with association-maintained landscaping may have different near-term needs from an older Sarasota pool home. A waterfront property with a dock or seawall creates different considerations from a condominium where portions of the building are maintained collectively through the association.
Instead of relying exclusively on a generic percentage, buyers can use inspection findings and available property records to identify major components and likely near-term work. Repair costs and remaining useful life should be evaluated by qualified inspectors, contractors, engineers, or other appropriate professionals before a buyer relies on an estimate.
Which Major Home Components Deserve Long-Term Planning?
Major components do not necessarily fail on a predictable schedule, but understanding their condition can help buyers recognize future expenses that may be more significant than ordinary monthly maintenance.
Depending on the property, long-term planning may include the roof, HVAC equipment, water heater, plumbing, electrical components, appliances, exterior finishes, windows and doors, pool equipment, irrigation, driveways, fencing, and drainage. Waterfront homes can add docks, seawalls, lifts, and other marine infrastructure to that list.
Age alone should not be treated as a professional conclusion about a component's condition or remaining life. Inspection findings should be evaluated with the appropriate licensed inspector, contractor, engineer, or qualified tradesperson before the buyer makes a decision that depends on technical condition or anticipated repair costs.
Why Do Post-Closing Reserves Matter?
Cash remaining after closing gives a homeowner resources for expenses that were not part of the purchase transaction. An appliance can fail, an optional repair can become more urgent, or an insurance deductible can become relevant after a covered event.
That does not mean there is one reserve amount every buyer should keep. A buyer's appropriate emergency savings and financial reserves depend on income, other obligations, property condition, financing requirements, risk tolerance, and broader financial circumstances.
Buyers should discuss required mortgage reserves with their lender and consult a qualified financial professional when they need individualized guidance about emergency savings or broader financial planning.
How Can Buyers Compare Two Homes Using These Three Costs?
Compare each property using the same three categories: cash needed to purchase it, recurring ownership expenses, and anticipated maintenance or reserve needs. This can reveal differences that are hidden when buyers compare only list prices and mortgage payments.
For example, one home might have a lower asking price but higher insurance and near-term repair needs. Another might cost more initially but have newer major systems. A condominium may reduce some individual maintenance responsibilities while introducing association assessments and potential building-related expenses.
Hunt Brothers Realty helps buyers compare these real estate characteristics as part of the property search. Financing, insurance, taxes, inspection findings, association financial matters, and repair estimates should still be verified with the professionals qualified in those areas.
What Should Buyers Know Before Setting Their Maximum Price?
A buyer's maximum purchase price should not be evaluated in isolation from the costs that follow it. Two homes at the same price can require different amounts of cash at closing and create different ongoing ownership budgets.
Hunt Brothers Realty's Florida home-buying process guide recommends building the budget around the complete cost of owning a particular property rather than the listing price or estimated mortgage principal and interest alone.
A lender can explain loan qualification and financing scenarios. The amount a buyer qualifies to borrow, however, is not automatically the same as the purchase price that best fits that buyer's complete financial circumstances.
A Better Buyer Budget Goes Beyond the Down Payment
Buying a Florida home involves more than saving for a down payment. Buyers need to understand the cash required to complete the transaction, the recurring expenses associated with the individual property, and the money they may need after closing for maintenance and unexpected costs.
Thinking in these three categories makes it easier to compare homes that look similar on a listing page but have different ownership profiles. Insurance, taxes, association expenses, property condition, pools, landscaping, and other factors can materially change the complete budget.
The goal is not to predict every future expense. It is to identify the major cost categories early enough to investigate them before deciding whether a particular home fits.
Plan Your Florida Home Purchase With Hunt Brothers Realty
Hunt Brothers Realty helps Sarasota and Florida Gulf Coast buyers compare properties using more than purchase price alone. Buyers can review HBR's guide to the true cost of buying a Florida home, explore Florida homebuyer closing costs, learn how down-payment choices fit into the larger budget, or contact Hunt Brothers Realty to discuss a Gulf Coast home search.
Informational notice: This article provides general real estate information for educational purposes and is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction, title, association, or other professional advice. Purchase costs, financing, insurance, taxes, association obligations, maintenance needs, and appropriate financial reserves vary by buyer and property. Buyers should work with a licensed real estate professional for property-specific real estate guidance and verify financing with a qualified lender, insurance with a qualified insurance professional, tax matters with the appropriate government office or tax professional, inspection findings with qualified inspectors and appropriate contractors or engineers, association information with the applicable association or management source, and legal or title questions with qualified legal or title professionals.
Sources
- Consumer Financial Protection Bureau, Figure Out How Much You Want to Spend
- Consumer Financial Protection Bureau, Loan Estimate Explainer
- Consumer Financial Protection Bureau, Closing Disclosure Explainer
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
- Hunt Brothers Realty, Florida Homebuyer Closing Costs
- Hunt Brothers Realty, How Much Should You Put Down on a House?
- Hunt Brothers Realty, What Expenses Surprise People After Moving to Florida?
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2654
- Anna Maria Island 92
- Bird Key 5
- Bradenton 242
- Buying a Home 1675
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1603
- Ellenton 8
- Englewood 15
- First Time Homebuyers 1795
- Foreclosures 4
- Home Selling 10
- Homeownership 1840
- Lakewood Ranch 36
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1781
- Market Updates & Trends 1283
- Mortgages & Financing 85
- Move-Up Buyers 24
- Neighborhood Guides 1410
- New Construction 46
- Palmetto 4
- Parrish 38
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1694
- Relocation to Florida 1722
- Safety Harbor 4
- Sarasota 157
- Sarasota - Downtown 175
- Selling a Home 149
- Siesta Key 94
- St. Petersburg 11
- Taxes and Homestead 3
- Tierra Verde 7
- Vacation & Second Homes 1888
- Venice 225
- Wellen Park 24
Recent Posts