What Does $300,000 Buy in Florida?
A $300,000 budget can still buy real estate in Florida in 2026, but what you get depends heavily on location and property type. Statewide, $300,000 is below the recent median price for existing single-family homes but close to the median for condos and townhouses. That means buyers may find the broadest selection among condos, villas and townhomes, while select single-family homes can also fall near or below $300,000 in certain markets. Purchase price is only the starting point. Insurance, property taxes, association fees, assessments, flood considerations, financing and property condition can substantially change the true cost of ownership.
Quick Answers About What $300,000 Buys in Florida
Can you buy a house in Florida for $300,000 in 2026?
Yes. Single-family homes sell below $300,000 in Florida, although availability varies considerably by city, neighborhood, condition and property characteristics. Florida's October 2026 statewide single-family median was $420,000, so a $300,000 detached-home search generally requires more location and property flexibility than the statewide midpoint suggests.
Is $300,000 a realistic budget for a Florida condo?
Yes. Florida Realtors reported a statewide condo and townhouse median sale price of $290,000 in October 2026, making $300,000 a meaningful price point in that segment. Individual buildings and communities can still vary dramatically in price and ownership costs.
Can $300,000 buy a home near the Florida coast?
Potentially, but “near the coast” is different from direct beachfront or waterfront ownership. Buyers may find inland condos, villas, townhomes and select houses within coastal metropolitan areas at this price, while direct Gulf-front and premium waterfront properties frequently occupy very different price ranges.
What property type gives a $300,000 Florida buyer the most choices?
Condos and townhomes are a logical place to start because the statewide median for that category has recently been near $300,000. Buyers should compare association finances and recurring expenses carefully, however, because a lower purchase price does not automatically produce a lower total ownership cost.
Does a $300,000 purchase price mean the homes are equally affordable?
No. Two $300,000 Florida properties can have substantially different insurance premiums, taxes, HOA or condominium assessments, CDD assessments, maintenance requirements and repair needs. Buyers should compare the complete property-specific budget.
How much should a buyer budget for closing costs on a $300,000 home?
For early planning only, a broad 2% to 5% illustration equals approximately $6,000 to $15,000 on a $300,000 purchase, excluding the down payment. Actual closing costs depend on the financing, title and settlement arrangements, insurance, prepaid expenses, property and negotiated contract terms.
Should buyers spend the full $300,000 if that is their maximum budget?
Not automatically. Buyers should account for cash needed at closing, recurring ownership expenses and reserves for repairs or unexpected costs. Financed buyers should establish a comfortable purchase range with a qualified mortgage professional rather than treating their maximum loan qualification as an automatic spending target.
Is $300,000 Still a Realistic Florida Home-Buying Budget in 2026?
Yes, but $300,000 sits in a very different position depending on the property type. According to Florida Realtors' October 2026 statewide market data, the median sale price was $420,000 for existing single-family homes and $290,000 for condos and townhouses.
The third-quarter numbers tell a similar story. Florida's Q3 2026 median was $420,000 for single-family homes and $295,000 for condos and townhouses. A median is the midpoint of sales, not the minimum price required to enter the market, so homes sell both above and below these figures.
For a $300,000 buyer, this means the condo and townhome market generally deserves serious attention. Detached homes can still be available at this budget, but location, size, condition and other property characteristics become especially important.
What Kind of Condo Can $300,000 Buy in Florida?
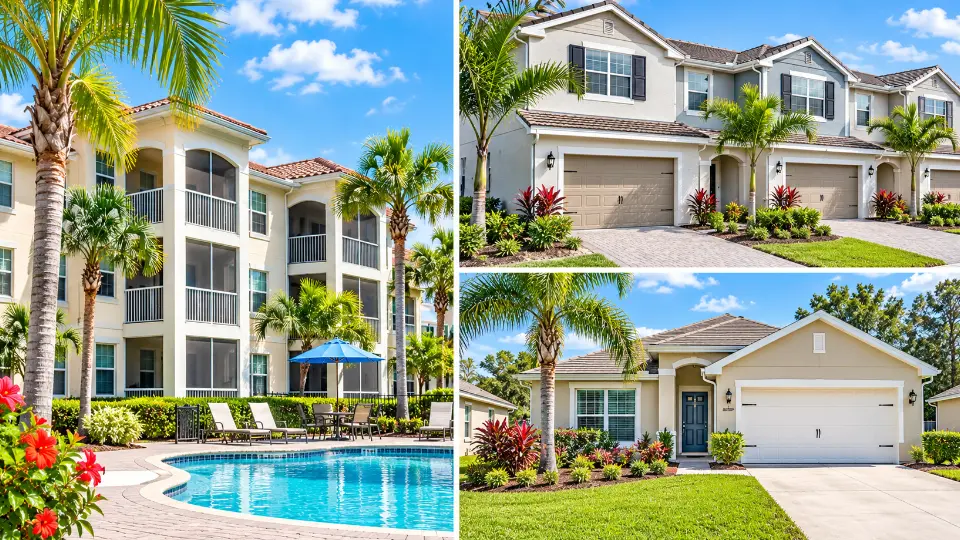
A $300,000 budget can place buyers squarely within Florida's condo and townhome market, but the residence and building can look completely different from one location to another. The recent statewide median near this price confirms that $300,000 is an active condo and townhome price point rather than an unusual exception.
Depending on the local market, buyers may encounter low-rise condominiums, units in established amenity communities, inland condos within coastal metropolitan areas, smaller units in higher-cost locations or larger residences farther from premium waterfront and downtown locations.
The critical mistake is comparing condos only by sale price and monthly fee. Hunt Brothers Realty's Florida condo reserve guide explains why buyers should also investigate reserves, association insurance, assessments, building condition and future capital obligations.
What Can $300,000 Buy in Florida's Townhome and Villa Market?
Townhomes and villas can provide a useful middle ground between condominium and detached-home ownership. At approximately $300,000, buyers may encounter attached residences with multiple bedrooms, private entrances, garage parking or community amenities, depending on the market and development.
Ownership structures and maintenance responsibilities vary. A villa may be legally organized as a condominium in one community and under an HOA structure in another. The exterior appearance alone does not tell a buyer who maintains the roof, landscaping, exterior walls or other components.
Before comparing two attached properties, determine exactly what the owner maintains and what the association maintains. Then compare the current fees, reserves, insurance responsibilities and any assessments alongside the purchase price.
Can $300,000 Still Buy a Single-Family Home in Florida?
Yes. Florida continues to record single-family sales below $300,000, even though the statewide median is substantially higher. In Q3 2026, Florida Realtors continued to report transactions in the $200,000 to $299,999 single-family price range.
The tradeoff is that buyers searching for detached homes around $300,000 may need to be more flexible about geography, age, square footage, finishes, lot characteristics or renovation needs. A newer detached home in one inland market and an older home within a coastal metropolitan area can have the same asking price for very different reasons.
Property condition becomes especially important when stretching a budget. An apparently inexpensive home that soon needs a roof, HVAC system, plumbing work or other major repairs can have a higher effective cost than a somewhat more expensive property in stronger condition.
What Does $300,000 Buy Around Sarasota and Florida's Gulf Coast?
Around Sarasota and the central Gulf Coast, $300,000 generally requires buyers to distinguish carefully between property types and submarkets. Sarasota County's Q3 2026 median sale price was approximately $485,000 for single-family homes and $324,380 for condos and townhomes, according to current market data summarized by Hunt Brothers Realty's Southwest Florida relocation guide.
Manatee County's Q3 2026 medians were approximately $490,000 for single-family homes and $307,000 for condos and townhomes. These countywide figures do not describe every neighborhood, but they illustrate why a $300,000 Gulf Coast search may produce substantially more attached-housing choices than detached homes in some locations.
Buyers can use Hunt Brothers Realty's Florida Gulf Coast community guides to compare Sarasota-area locations before narrowing the search by current inventory and price.
Does $300,000 Buy More if You Move Farther Inland?
It can, but buyers should verify the actual local market rather than assuming every inland location is less expensive. Coastal proximity, downtown access, new construction, employment centers, community amenities and local supply can all influence pricing.
A useful search strategy is to decide how much location flexibility you have before deciding which property characteristics are negotiable. Moving the search radius may create options for more square footage, a garage, a larger lot or a detached home, but it may also change commute times and access to beaches, boating, restaurants or other destinations.
The correct comparison is not simply coast versus inland. It is the complete combination of property, location, ownership cost and daily routine.
Can You Buy Near a Florida Beach for $300,000?
Potentially, particularly if “near the beach” means living within a coastal area rather than directly on the Gulf. A $300,000 buyer may encounter inland condominiums, older attached housing or other properties within driving distance of beaches in some Florida markets.
Direct beachfront and premium waterfront real estate is a different category. Location, water views, direct access, building characteristics and land value can create substantial price differences even between properties only a short distance apart.
Coastal buyers should also evaluate insurance and flood considerations early. A lower asking price should not be interpreted as evidence that a coastal property will have low recurring ownership costs.
Why Can Two $300,000 Florida Homes Cost Very Different Amounts to Own?
Purchase price is only one component of affordability. Two properties purchased for exactly $300,000 can produce materially different monthly expenses and long-term financial obligations.
As explained in Hunt Brothers Realty's guide to the true cost of buying a Florida home, a complete budget may need to include:
- Mortgage principal and interest when financing
- Property taxes
- Homeowners or condominium-unit insurance
- Flood insurance when applicable or desired
- HOA or condominium assessments
- CDD or other applicable district assessments
- Utilities
- Pool and landscaping expenses where applicable
- Routine maintenance
- Future major repairs and replacements
This is why buyers should compare properties using total ownership cost rather than simply sorting listings from lowest to highest asking price.
How Much Can HOA or Condo Fees Change a $300,000 Budget?
Association expenses can materially change affordability because the same $300,000 purchase price can come with very different recurring fees. The amount alone also does not tell the full story, because associations provide different services and maintain different common property.
A condominium assessment might contribute toward building insurance, exterior maintenance, reserves, landscaping, amenities or selected utilities, while another community may allocate expenses differently. A detached HOA property may have a lower association fee while leaving substantially more maintenance and insurance responsibility with the homeowner.
Review what the fee covers, current reserve information, recent and proposed assessments, association insurance and known capital projects. A low monthly assessment should not automatically be interpreted as evidence that an association is financially stronger or that the property will cost less to own.
Why Does Insurance Matter So Much at This Price Point?
Insurance can materially affect the affordability of a Florida property even when two homes have the same purchase price. Roof age, construction characteristics, wind mitigation features, location, flood exposure and other property-specific factors can affect coverage and premiums.
A buyer who focuses only on finding the lowest-priced home may discover that another property with a somewhat higher purchase price has a more manageable total ownership budget. That conclusion cannot be made from the listing alone because insurance is property-specific.
Hunt Brothers Realty's guide to Florida insurance questions to ask before making an offer explains why buyers should investigate insurability early. Obtain property-specific quotes and review coverage, deductibles and premiums with a qualified insurance professional before making a purchasing decision that depends on those costs.
How Much Cash Might You Need to Buy a $300,000 Florida Home?
The answer depends on the down payment, loan program, closing costs, prepaid expenses, insurance, deposits and the individual transaction. A $300,000 purchase price does not mean a buyer needs exactly the same amount of cash in every transaction.
For preliminary planning, Hunt Brothers Realty's 2026 Florida buyer closing-cost guide illustrates a broad 2% to 5% range. At a $300,000 purchase price, the arithmetic is approximately $6,000 to $15,000, excluding the down payment.
That range is an illustration, not a quote or guaranteed Florida average. Financed buyers should use their lender's current estimates, and all buyers should obtain transaction-specific figures from the appropriate lender, title or closing professionals before making financial decisions.
Should a Buyer With $300,000 Look Below the Maximum Price?
Often it is useful to compare properties below the maximum budget, particularly when a buyer wants to preserve cash for closing, repairs, renovations or reserves after the purchase. The appropriate amount depends on the buyer's finances and the specific property.
For example, a lower-priced older home may need immediate improvements, while a $300,000 condo may have a special assessment or substantial recurring association expenses. Conversely, another property closer to the maximum price may require less immediate work. Price alone does not reveal which is the more manageable purchase.
Financed buyers should discuss loan qualification, monthly payment scenarios and cash requirements with a qualified mortgage professional. The maximum amount a lender may approve should not automatically become the buyer's personal spending target.
What Should You Inspect Carefully on a Lower-Priced Florida Home?
Property condition deserves careful attention at every price point. Buyers should not assume a home priced below the local median necessarily needs work, nor should they assume a renovated property has no significant maintenance issues.
Depending on the individual home, relevant areas may include the roof, electrical system, plumbing, HVAC equipment, windows and doors, moisture conditions, structure, pool equipment, sewer or septic systems and other property-specific components.
Inspection findings should be evaluated with the appropriate licensed inspector, contractor, engineer or other qualified professional before the buyer makes a decision requiring technical expertise. Repair costs should be investigated rather than estimated from appearance alone.
What Should a $300,000 Condo Buyer Review Before Making an Offer?
A condo buyer is evaluating both the individual unit and the condominium association. This distinction is especially important when comparing properties near the same price because association finances and building obligations can materially change the ownership picture.
- Current condominium assessments
- Current budget and applicable reserve information
- Current, recent or proposed special assessments
- Master insurance information
- Maintenance responsibilities
- Recent association meeting information
- Rental and pet restrictions
- Applicable inspection and reserve-study information
- Financing eligibility for the specific condominium project
Condominium laws, documents and financing requirements can be technical. Buyers should obtain current information for the specific association and use qualified legal, lending, insurance, inspection and other professionals when individualized guidance is required.
Is a Condo or Single-Family Home the Better Value at $300,000?
Neither property type is automatically the better value. A condo can offer a lower purchase price and association-managed common elements, while a detached home may provide more private space and control but leave more maintenance directly with the owner.
The comparison becomes especially relevant around Sarasota, where the recent condo and townhome median has been materially below the single-family median. Hunt Brothers Realty's Sarasota condo versus single-family home guide explains how ownership responsibilities differ between the two.
Compare what you own, what you maintain, what the association maintains, how much insurance may cost and which expenses are likely to continue after the mortgage is paid.
Does a Lower Purchase Price Mean Lower Property Taxes?
Purchase price is relevant to a property's value, but buyers should not simply use the seller's current tax bill as a prediction of their future taxes. Florida property taxes depend on property-specific assessments, taxing authorities, exemptions and the owner's circumstances.
A change in ownership can affect assessed value, and a qualifying owner who establishes a permanent Florida residence may be eligible for homestead-related benefits. Buyers should obtain property-specific information from the applicable county property appraiser rather than assuming the current owner's bill will continue unchanged.
Tax consequences depend on the individual owner and property. Buyers should consult the appropriate property appraiser and a qualified tax professional or CPA regarding their specific circumstances.
What Can Surprise Buyers After Purchasing a $300,000 Florida Home?
The biggest surprises often come from expenses that were not included in the original home-search budget. Hunt Brothers Realty's guide to expenses that can surprise people after moving to Florida highlights insurance, taxes after ownership changes, association assessments, storm preparation, air-conditioning, pool care, landscaping and exterior maintenance among the costs buyers should investigate.
The practical lesson is simple: a $300,000 purchase price should be treated as the beginning of the budget analysis, not the end. Property-specific recurring expenses can matter as much as a modest difference in asking price.
How Should Buyers Search Florida With a $300,000 Budget?
Start by deciding which variables can change. A buyer who is flexible about property type may discover more locations, while someone committed to a detached house may need a wider geographic search or greater flexibility on age and condition.
- Set a comfortable total ownership budget, not just a purchase-price ceiling.
- Decide whether a condo, villa, townhome or detached house can work.
- Identify which Florida locations are essential and which are flexible.
- Speak with a qualified mortgage lender early if financing.
- Investigate insurance before committing to a property where coverage or cost may affect the decision.
- Review HOA or condominium expenses before comparing affordability.
- Evaluate property condition through appropriate inspections.
- Keep sufficient cash available for closing and post-closing needs.
Buyers who are beginning the process can use Hunt Brothers Realty's 2026 Florida home-buying guide to organize financing, community research, touring, insurance, inspections, title and closing.
What Is the Bottom Line on a $300,000 Florida Home Budget?
A $300,000 budget remains a meaningful Florida real estate budget in 2026, particularly for condos and townhomes, while select single-family homes are also available below that price depending on the market. The recent statewide data makes the distinction clear: the condo and townhome median has been around $300,000, while the single-family median has been substantially higher.
The better question is not simply, “Can I buy something for $300,000?” It is, “What combination of property, location, condition and recurring costs can I comfortably own for $300,000?”
Answering that question requires current local inventory and property-specific due diligence. Florida is not one housing market, and two homes with identical prices can produce very different ownership experiences and costs.
Explore Florida Homes With Hunt Brothers Realty
Hunt Brothers Realty helps buyers compare Florida Gulf Coast properties based on more than asking price. Start with HBR's Florida Gulf Coast community guides, review the true cost of buying a Florida home, learn how to start the Florida home-buying process, or contact Hunt Brothers Realty to discuss your budget, preferred locations and property priorities.
Informational notice: This article provides general real estate and educational information and is not individualized legal, financial, tax, insurance, lending, inspection, engineering, construction, title, association or other professional advice. Home prices, inventory, financing, insurance, taxes, association expenses, assessments and property conditions vary by location, property and buyer. Buyers should verify current listings and property-specific information, obtain appropriate inspections and insurance quotes, and consult qualified real estate, mortgage, insurance, tax, legal, title, association and technical professionals before making decisions requiring individualized guidance.
Sources
- Florida Realtors, Florida Home Sales Slow in October as Mortgage Rates Rise
- Florida Realtors, Florida Housing Market September and Third Quarter 2026
- Hunt Brothers Realty, The True Cost of Buying a Home in Florida
- Hunt Brothers Realty, Florida Buyer Closing Costs in 2026
- Hunt Brothers Realty, Florida Condo Reserves Explained
- Hunt Brothers Realty, Insurance Questions Before Making an Offer in Florida
Hunt Brothers Realty
46 N. Washington Blvd, Ste 3, Sarasota, FL 34236
Phone: (941) 388-7017
Email: info@huntbrothersrealty.com
Website: HuntBrothersRealty.com
Categories
- All Blogs 2674
- Anna Maria Island 92
- Bird Key 6
- Bradenton 242
- Buying a Home 1692
- Casey Key 3
- Clearwater 16
- Condos & HOA Living 1623
- Ellenton 9
- Englewood 15
- First Time Homebuyers 1813
- Foreclosures 4
- Home Selling 10
- Homeownership 1860
- Lakewood Ranch 36
- Lido Key 29
- Longboat Key 81
- Luxury/Waterfront Properties 1801
- Market Updates & Trends 1302
- Mortgages & Financing 85
- Move-Up Buyers 24
- Neighborhood Guides 1429
- New Construction 47
- Palmetto 4
- Parrish 38
- Port Charlotte 36
- Punta Gorda 165
- Real Estate Investing 1714
- Relocation to Florida 1742
- Safety Harbor 4
- Sarasota 160
- Sarasota - Downtown 175
- Selling a Home 149
- Siesta Key 94
- St. Petersburg 11
- Taxes and Homestead 3
- Tierra Verde 7
- Vacation & Second Homes 1908
- Venice 225
- Wellen Park 24
Recent Posts